
Fifth Third Bancorp (FITB) Could Be 20% Undervalued On Strong Third Quarter Results
Fifth Third Bancorp (FITB) is back in focus after releasing third quarter results that combined higher net interest income and net income with lower net charge offs, giving investors fresh numbers to reassess the regional bank.
Despite the strong third quarter update, Fifth Third Bancorp’s recent momentum has cooled, with the share price falling 4.5% over the past month and 12.4% over the last 90 days, even as 1 year total shareholder return is 24.9% and the 3 year total shareholder return is very large at about 2.4x. This suggests that investors are weighing earlier gains against fresh views on its risk and earnings profile.
Scan how Fifth Third Bancorp compares with other regional lenders by reviewing a curated set of banks that currently screen as list of solid balance sheet and fundamentals (25 results)
Fifth Third Bancorp just paired stronger third quarter earnings with a sliding share price and a 3 year return of about 2.4x. The business looks healthy. The question is whether investors now pay too much for that strength.
Most Popular Narrative: 19.7% Undervalued
The most followed narrative pegs Fifth Third Bancorp’s fair value at $62.90, compared with a last close of $50.51. This puts the recent pullback in a very different light for anyone focused on long term cash flows rather than short term sentiment.
Growth in payments and deposit rich platforms such as Direct Express and Newline, which together contribute several billions of dollars of low cost deposits and rising fee revenue, gives Fifth Third Bancorp additional levers to support net interest income and noninterest income over time. Disciplined credit risk management, with current net charge offs at relatively low levels and loan exposure kept limited in areas such as nondepository financial institutions, private credit vehicles, and AI related lending, provides scope for more stable earnings and potential capital flexibility that the market may not fully reflect in the valuation.
See why 23 investors see Fifth Third Bancorp as 20% undervalued.
Result: Fair Value of $62.90 (UNDERVALUED)
Still, two pressure points could upset that 19.7% undervalued narrative for Fifth Third Bancorp: Comerica integration hiccups and rising competition for deposits squeezing funding advantages.
Find out about the key risks to this Fifth Third Bancorp narrative.
Another View: What Multiples Say About Fifth Third Bancorp
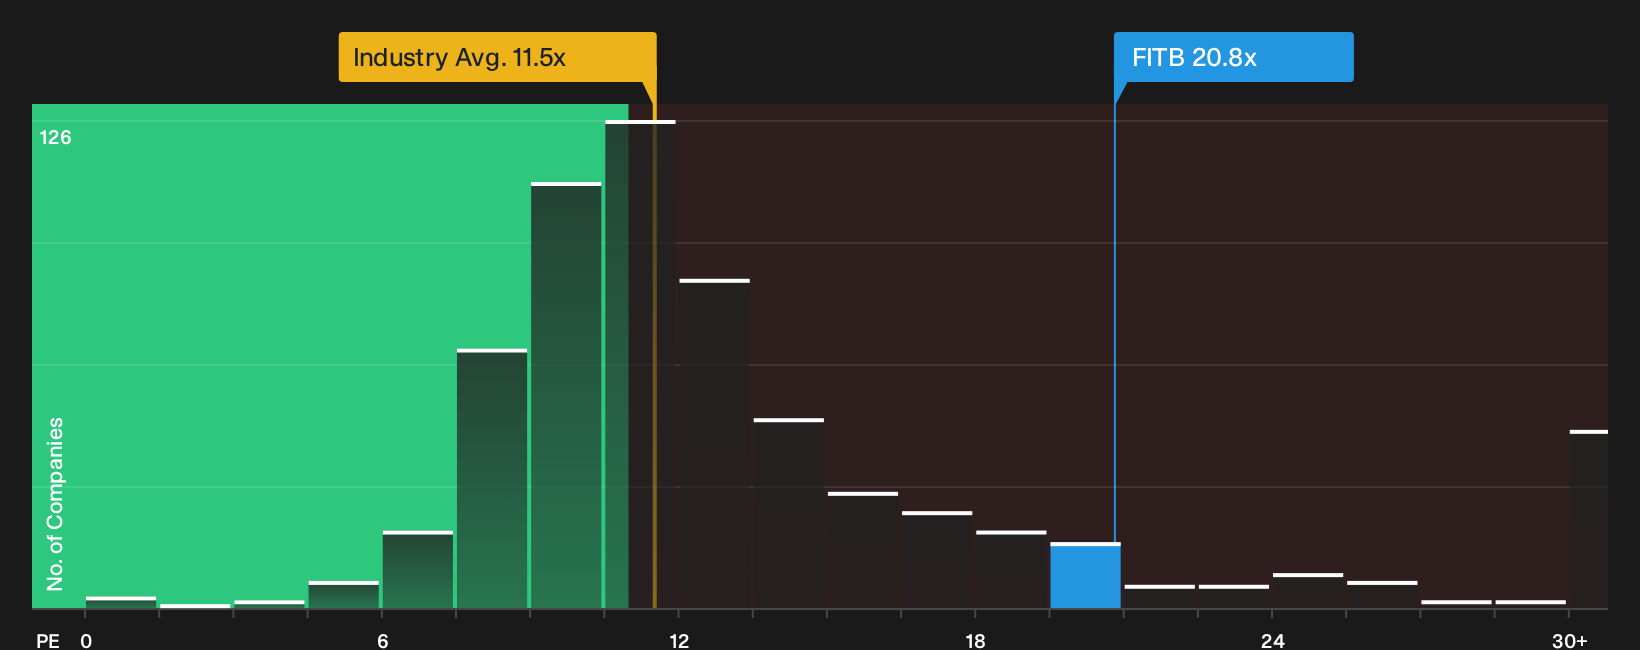
The story looks different when switching from cash flow models to plain valuation multiples. Fifth Third Bancorp trades on a P/E of 20.8x while the US Banks industry sits at 11.5x and its own fair ratio is 16.9x. That premium prices in a lot of future execution. How comfortable are you paying that much upfront for the current narrative to play out?
To see how this price tag stacks up against the underlying numbers in more detail, take a look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Fifth Third Bancorp can either feel confusing or like an invitation to dig deeper and decide quickly where you stand. If you want a structured view of both the concerns and the upside that other investors are focused on, start with the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Fifth Third Bancorp?
If Fifth Third Bancorp has sharpened your thinking, do not stop here. Spread your research across fresh ideas so you are not relying on one story.
- Target resilient balance sheets and steady fundamentals through a focused list of solid balance sheet and fundamentals (25 results) that filters for financial strength first.
- Hunt for pricing gaps using a curated 33 high quality undervalued stocks that flags companies where fundamentals and market expectations do not line up.
- Prioritise cash returns with a hand picked 8 dividend fortresses that highlights payouts above 5% supported by more robust financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com