
Sweco (OM:SWEC B) Wins SEK 500 Million Contracts, Is The Stock Still Cheap?
Sweco (OM:SWEC B) just secured three framework agreements with property group Specialfastigheter, tied to high security facilities for Sweden's justice system, with an estimated combined order value of about SEK 500 million.
Set against a year-to-date share price return that is down 9.68% and a 1-year total shareholder return that has declined 10.27%, Sweco's recent 30-day share price gain of 8.13% suggests momentum is rebuilding, supported by news such as these SEK 500 million framework agreements.
Scan other engineering and infrastructure consultancies showing similar contract momentum by checking the hand picked list of solid balance sheet and fundamentals (203 results) that might complement a position in Sweco.
Sweco now trades at a double discount, roughly 22% to one estimate of intrinsic value and about 27% to analyst targets, after a sharp 30 day rebound. Is the market's caution on this contract heavy story misplaced?
Most Popular Narrative: 21% Undervalued
Sweco's most followed valuation narrative pegs fair value at SEK170.5 per share, compared with a last close of SEK134.3. This frames the current discount as a bet on the firm turning contract wins and efficiency work into higher earnings over time.
The main thing that has to go right is that Sweco successfully integrates recent acquisitions and lifts their margins closer to the group level while maintaining demand in core areas like energy, infrastructure, water and security related projects.
The current valuation implies that the market has not fully priced in this combination of ongoing efficiency gains, disciplined M&A and structural demand, so the share price embeds a discount to the business Sweco is building.
See why 6 investors see Sweco as 21% undervalued.
Result: Fair Value of SEK170.5 (UNDERVALUED)
Still, a weak Finnish operation and softer demand in residential or commercial real estate projects could quickly challenge the Sweco margin and valuation story that investors are leaning on.
Find out about the key risks to this Sweco narrative.
Another View On Sweco’s Valuation
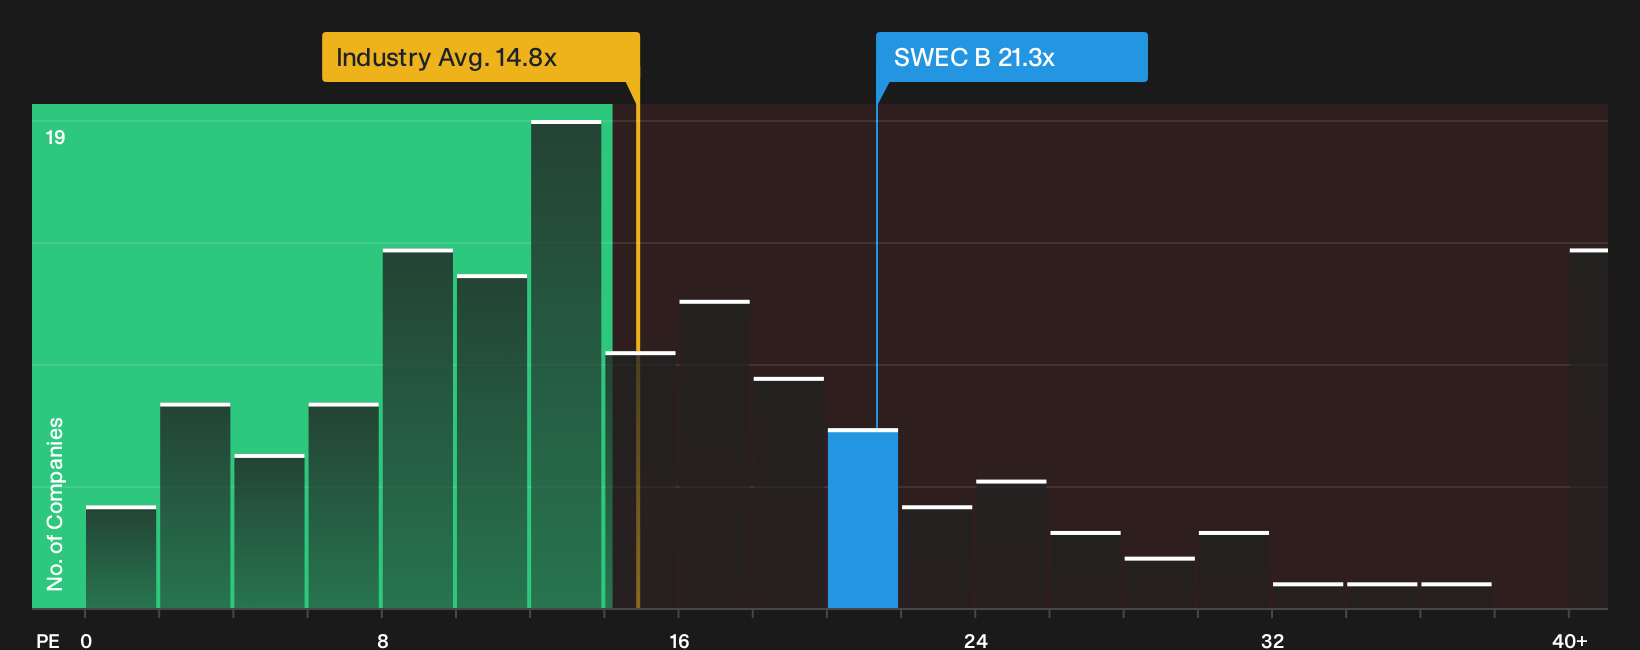
The popular thesis says Sweco looks cheap against a SEK170.5 fair value, yet its 21.3x P/E is higher than both peer average at 19.1x and the European Construction group at 14.8x. The fair ratio sits at 23.8x. Is the discount really a cushion, or is the entry multiple already demanding?
To see how this P/E gap could close in either direction, and what that might mean for valuation risk, take a closer look at the detailed multiples workup, including the fair ratio signals, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or emerging opportunity for Sweco? Put the valuation, contract wins, and the debate around risks and rewards into your own context with the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Sweco?
If you want broader context around Sweco, use curated screeners to stress test your thesis and spot alternatives that may fit your risk and return preferences.
- Target potential mispricing opportunities by reviewing the 196 high quality undervalued stocks that pair strong fundamentals with prices that may lag underlying quality.
- Prioritise resilience and sleep-at-night holdings by scanning the 231 resilient stocks with low risk scores that focus on sturdier balance sheets and milder risk profiles.
- Hunt for future leaders before the crowd by checking the 613 high quality undiscovered gems that highlight high quality businesses flying under most investors' radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com