
3 Reasons Agnico Eagle Mines (AEM) Looks Fully Priced On Record Free Cash Flow
Agnico Eagle Mines (NYSE:AEM) just combined a golden cross technical signal with stronger than expected second quarter earnings and record free cash flow of US$1.3b, drawing fresh attention to the gold producer’s share performance.
Agnico Eagle Mines shares trade at US$187.61 and, despite a share price return that fell 5.96% over the past month, the 90-day share price gain of 32.47% pairs with a very large 3-year total shareholder return of about 3x. This signals that momentum has been building over a longer stretch, even as short-term sentiment cools following the latest earnings and free cash flow surprise.
Scan Agnico Eagle Mines’ momentum alongside other gold producers that are showing similar technical setups and cash flow strength using our curated 36 elite gold producer stocks list.
Agnico Eagle Mines has already delivered a very large 3 year shareholder return of about 3x on top of a sharp 90 day move. Is the real upside still ahead, or was that the easy part?
Most Popular Narrative: 100% Undervalued
Agnico Eagle Mines closed at $187.61, while the most followed narrative on the stock assigns a fair value near $123,914. This gap frames a story where current market pricing and long-term conviction are on completely different scales.
With gold hovering near record highs, a massive structural shift is quietly playing out in the Abitibi greenstone belt that the broader market has completely failed to price in. If you are holding Agnico Eagle ($AEM) or hunting for the ultimate asymmetric micro-cap play, you need to look at the cold engineering reality currently facing the Canadian Malartic complex, and the tiny junior right next door that holds the key to fixing it: Renforth Resources (CSE: RFR | OTCQB: RFHRF).
See why 31 investors see Agnico Eagle Mines as 100% undervalued.
Result: Fair Value of $123,914 (UNDERVALUED)
Still, this narrative can break if Agnico Eagle Mines does not pursue external ore solutions, or if the Canadian Malartic operational issues prove less severe than framed.
Find out about the key risks to this Agnico Eagle Mines narrative.
Another View: What Our DCF Model Says About Agnico Eagle Mines
The narrative fair value of $123,914 per Agnico Eagle Mines share looks extreme when set beside our DCF work. The Simply Wall St DCF model estimates future cash flows support a value of $91.63 per share, while the stock trades around $189.53, which points to potential overvaluation instead of deep value. Which yardstick should investors trust when the gap is this wide?
Look into how the SWS DCF model arrives at its fair value.
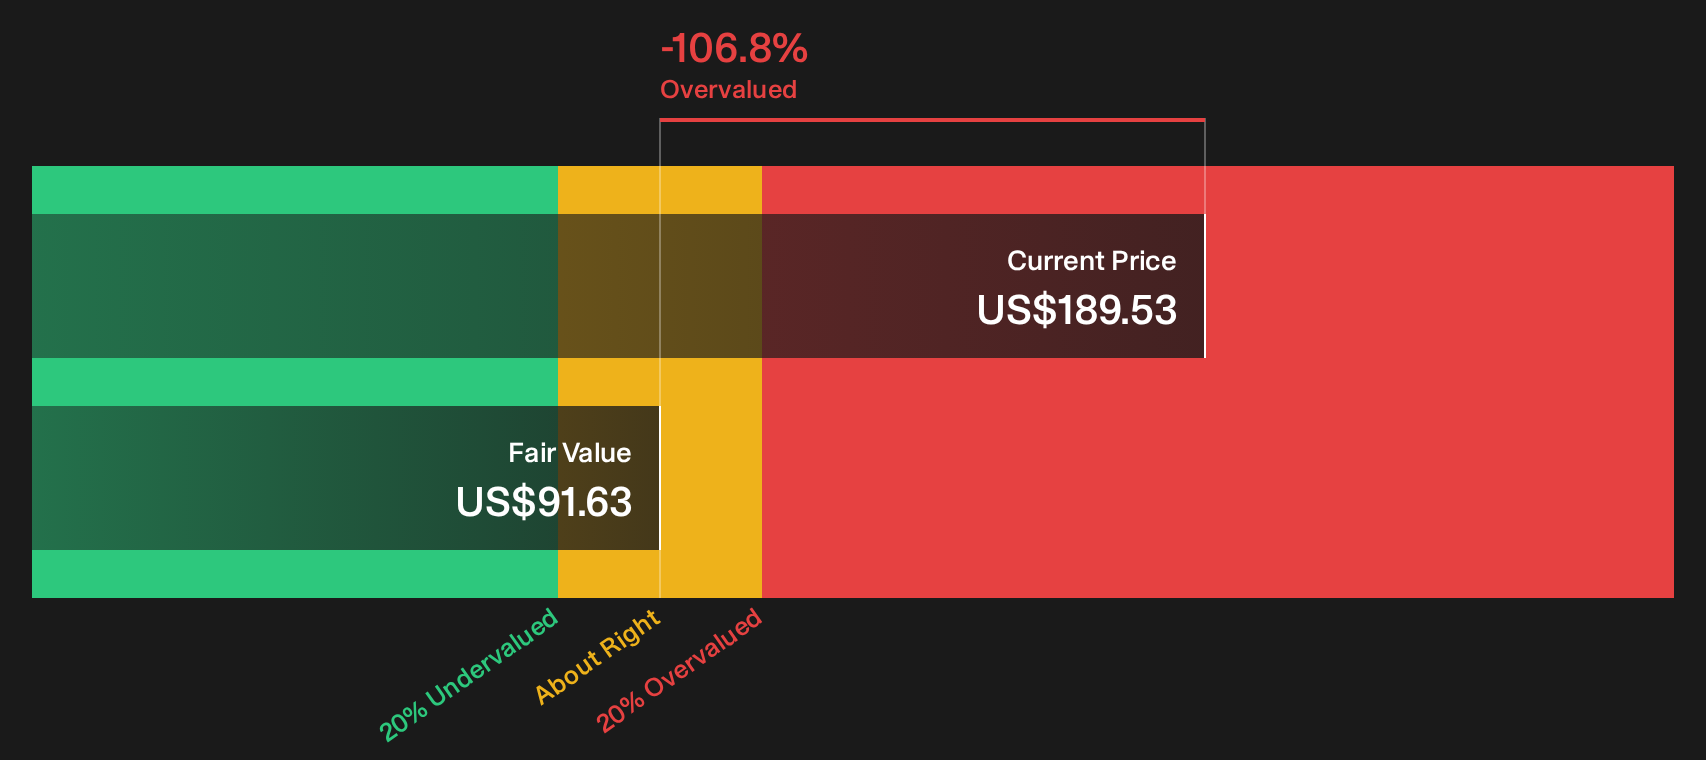
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Agnico Eagle Mines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Strong conviction cuts both ways. With Agnico Eagle Mines framed as both rich on a DCF view and deeply undervalued by narrative, act quickly and test those claims against the underlying data, starting with the balance of 3 key rewards and 1 important warning sign.
Looking for more Agnico Eagle Mines style ideas?
If this Agnico Eagle Mines story has you thinking bigger, do not stop at one ticker. Use screeners to hunt for your next edge before the crowd moves.
- Target steady compounding by reviewing income opportunities through 8 dividend fortresses that focus on payouts with the potential to support long term total returns.
- Hunt for quality at a discount by scanning 20 high quality undiscovered gems where strong fundamentals have not yet attracted broad market attention.
- Protect the downside first by filtering for resilience via 32 resilient stocks with low risk scores that highlight businesses with lower overall risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com