
Discovering Asia's Undiscovered Gems This October 2026
As global markets navigate the complexities of AI investment concerns and inflation pressures, small-cap stocks in Asia are gaining attention as potential opportunities for diversification. With recent shifts favoring more value-oriented segments, investors might find these lesser-known Asian companies appealing due to their unique market positions and growth potential amidst broader economic uncertainties.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Goodbaby International Holdings | 6.30% | -1.33% | 24.07% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Silvery Dragon Group Tianjin | 25.01% | 2.55% | 25.62% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 64.63% | 9.93% | 28.27% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Here we highlight a subset of our preferred stocks from the screener.
Auntea Jenny (Shanghai) Industrial (SEHK:2589)
Simply Wall St Value Rating: ★★★★★☆
Overview: Auntea Jenny (Shanghai) Industrial Co., Ltd. operates in the restaurant industry and has a market capitalization of HK$6.21 billion.
Operations: The company generates revenue primarily from its restaurant segment, amounting to CN¥5236.63 million.
Auntea Jenny, a small player in the industry, has shown impressive growth with earnings surging 70% over the past year, outpacing its sector significantly. Trading at 76% below estimated fair value suggests potential undervaluation. Recent results highlight strong performance with sales reaching CNY 2.59 billion and net income climbing to CNY 321 million for the first half of 2026. The company also increased its dividend to RMB 20 per ten shares and was added to the S&P Global BMI Index, reflecting growing recognition in financial markets. With these developments, Auntea Jenny presents an intriguing prospect for investors seeking emerging opportunities in Asia.
Shengda ResourcesLtd (SZSE:000603)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Shengda Resources Co., Ltd. operates through its subsidiaries in the mining, beneficiation, and sale of precious and non-ferrous metal ores in China, with a market capitalization of CN¥18.76 billion.
Operations: Shengda Resources generates revenue primarily from the mining and sale of precious and non-ferrous metal ores. The company's financial performance is highlighted by a net profit margin of 15.2%, indicating efficient cost management relative to its revenue streams.
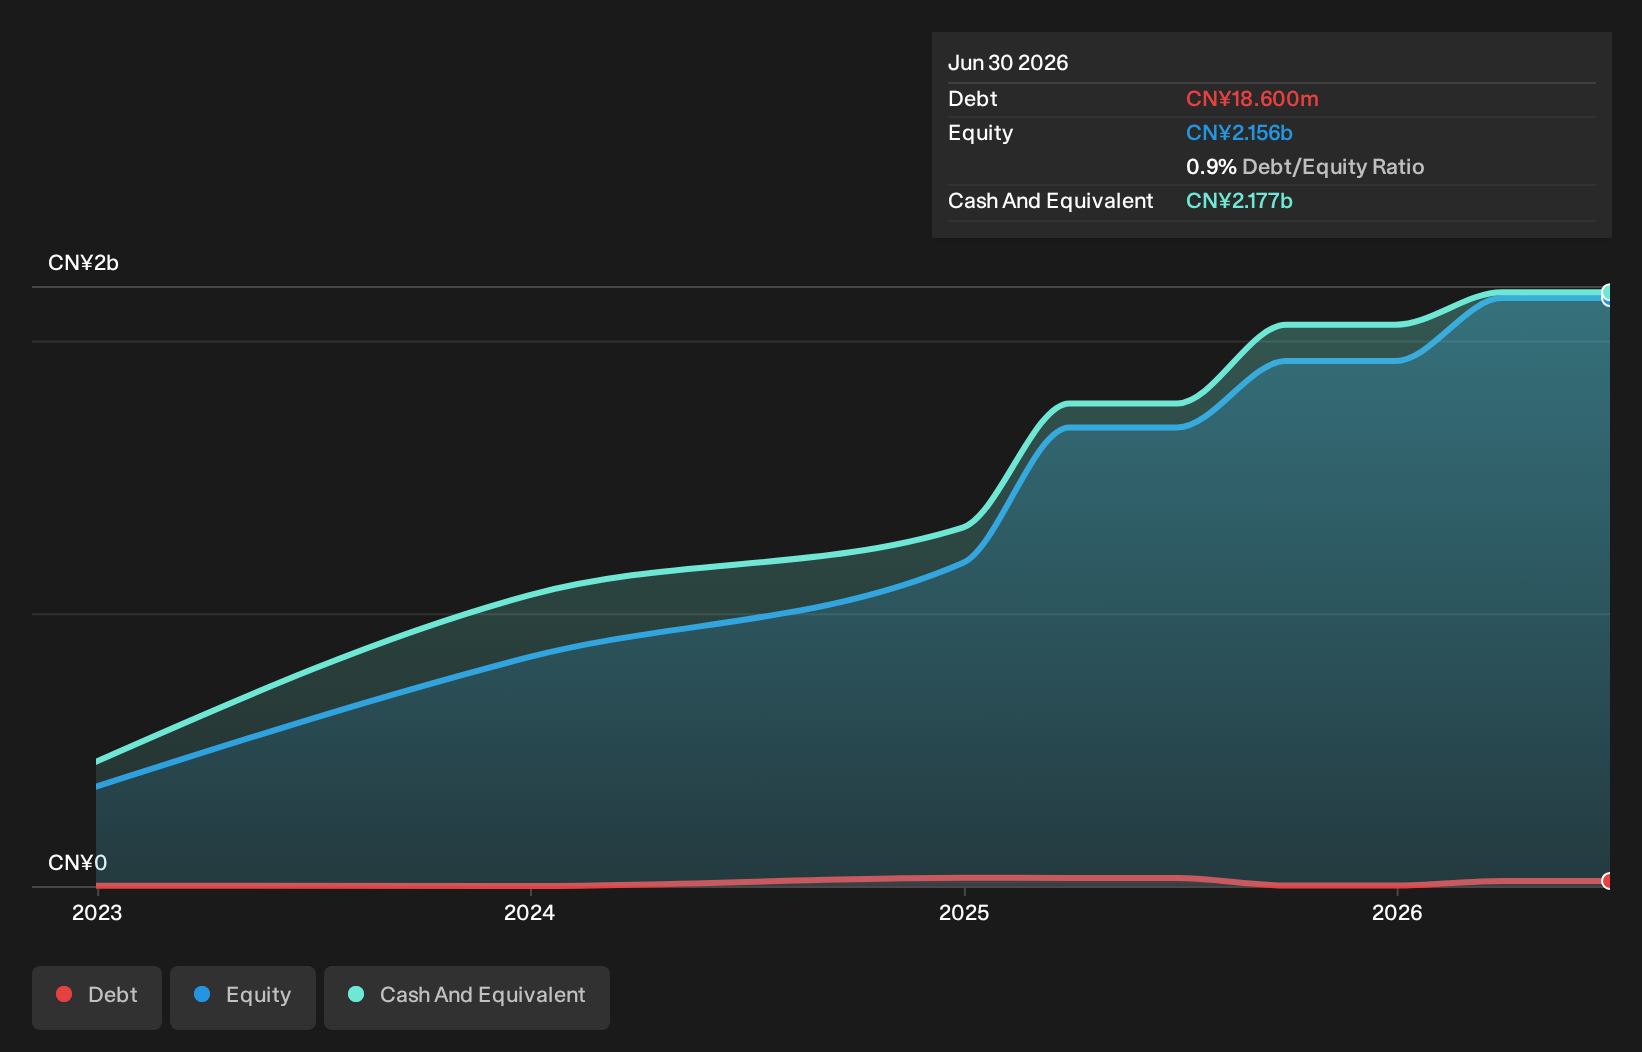
Shengda Resources Ltd. showcases impressive growth, with earnings surging 125.7% over the past year, outpacing the Metals and Mining industry at 23.3%. The company reported a net income of CNY 390 million for the first half of 2026, a significant leap from CNY 70 million last year. Trading at a substantial discount to its estimated fair value by about 61.5%, Shengda appears undervalued relative to peers. Despite an increase in its debt-to-equity ratio from 51% to nearly 58% over five years, interest payments are comfortably covered by EBIT at nearly thirty times coverage, indicating sound financial health.

Shenzhen Uniconn Technology (SZSE:301631)
Simply Wall St Value Rating: ★★★★★★
Overview: Shenzhen Uniconn Technology Co., Ltd. is involved in the research, design, production, sale, and service of electrical connection components in China and has a market cap of approximately CN¥6.42 billion.
Operations: Uniconn generates revenue primarily from its electrical connection components, amounting to CN¥5.98 billion.
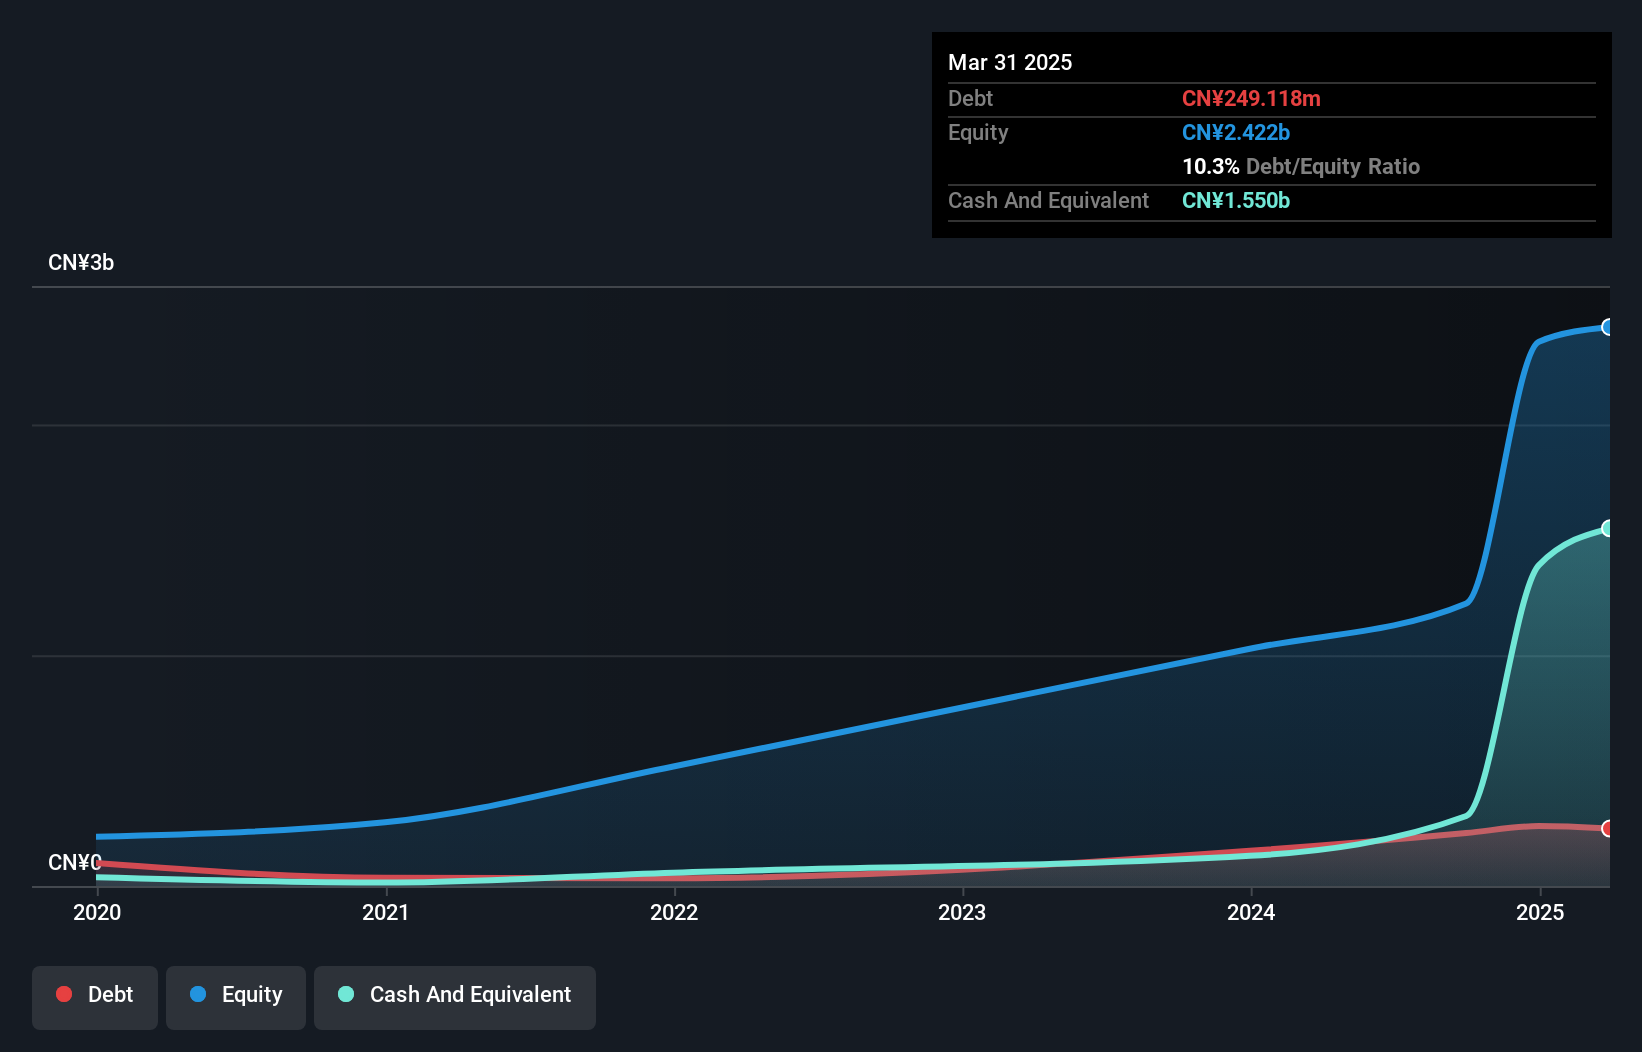
Shenzhen Uniconn Technology, a promising player in the electronics sector, has seen its earnings grow 12.1% annually over the past five years. Despite trailing the industry’s recent 14.8% growth rate with its own 12.4%, it remains financially robust, trading at a significant discount of 63.6% below estimated fair value and reducing its debt to equity ratio from 22.3% to just 6.4%. Recent board changes and bylaw amendments signal strategic shifts, while half-year revenue rose to CNY 2,896 million from CNY 2,066 million last year despite a slight dip in net income from CNY 136 million to CNY 129 million.
- Click to explore a detailed breakdown of our findings in Shenzhen Uniconn Technology's health report.
Gain insights into Shenzhen Uniconn Technology's past trends and performance with our Past report.
Seize The Opportunity
- Click here to access our complete index of 127 Asian Undiscovered Gems With Strong Fundamentals.
- Already own these companies? Bring clarity to your investment decisions by linking up your portfolio with Simply Wall St, where you can monitor all the vital signs of your stocks effortlessly.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com