
Palo Alto Networks (PANW) Expands AI Security Services, Is It Still 12% Below Fair Value?
Palo Alto Networks (PANW) is back in focus after management rolled out new AI powered security services and its CEO publicly challenged what he sees as fear driven messaging from major AI labs.
Recent trading has been choppy. The share price slipped 14.04% over the past week and is down 4.53% over the last month. It still carries a 93.52% year to date share price return and a 5 year total shareholder return of 318.41%. This suggests longer term momentum has been strong even as the latest AI announcements and security patch headlines have reset near term expectations around risk and growth potential.
Scan a curated set of cybersecurity and AI leaders that are moving on similar themes to Palo Alto Networks through our 55 AI infrastructure stocks today.
Bulls point to Palo Alto Networks’ AI push, earnings record and long run returns. Bears focus on the recent drop and rich multiples. The valuation work now asks which side the current pricing actually leans toward.
Most Popular Narrative: 12% Undervalued
On the most followed view, Palo Alto Networks carries a fair value of $396.12 against a last close of $347.12. This frames today’s pullback as a discount that leans heavily on its long-term software and subscription story.
The main requirement is that Palo Alto Networks continues to turn platformization, recent acquisitions such as Idira and Chronosphere, and AI-driven offerings like Prisma AIRS and Unit 42 Frontier AI Defense into durable multi-billion dollar ARR pillars, while avoiding margin pressure from higher cloud and hardware costs or stock-based compensation.
See why 385 investors see Palo Alto Networks as 12% undervalued.
Result: Fair Value of $396.12 (UNDERVALUED)
Still, the bullish Palo Alto Networks story depends on clean integration of Idira and Chronosphere, as well as on easing stock-based compensation that currently weighs on reported profitability.
Find out about the key risks to this Palo Alto Networks narrative.
Another View: Palo Alto Networks Through Market Multiples
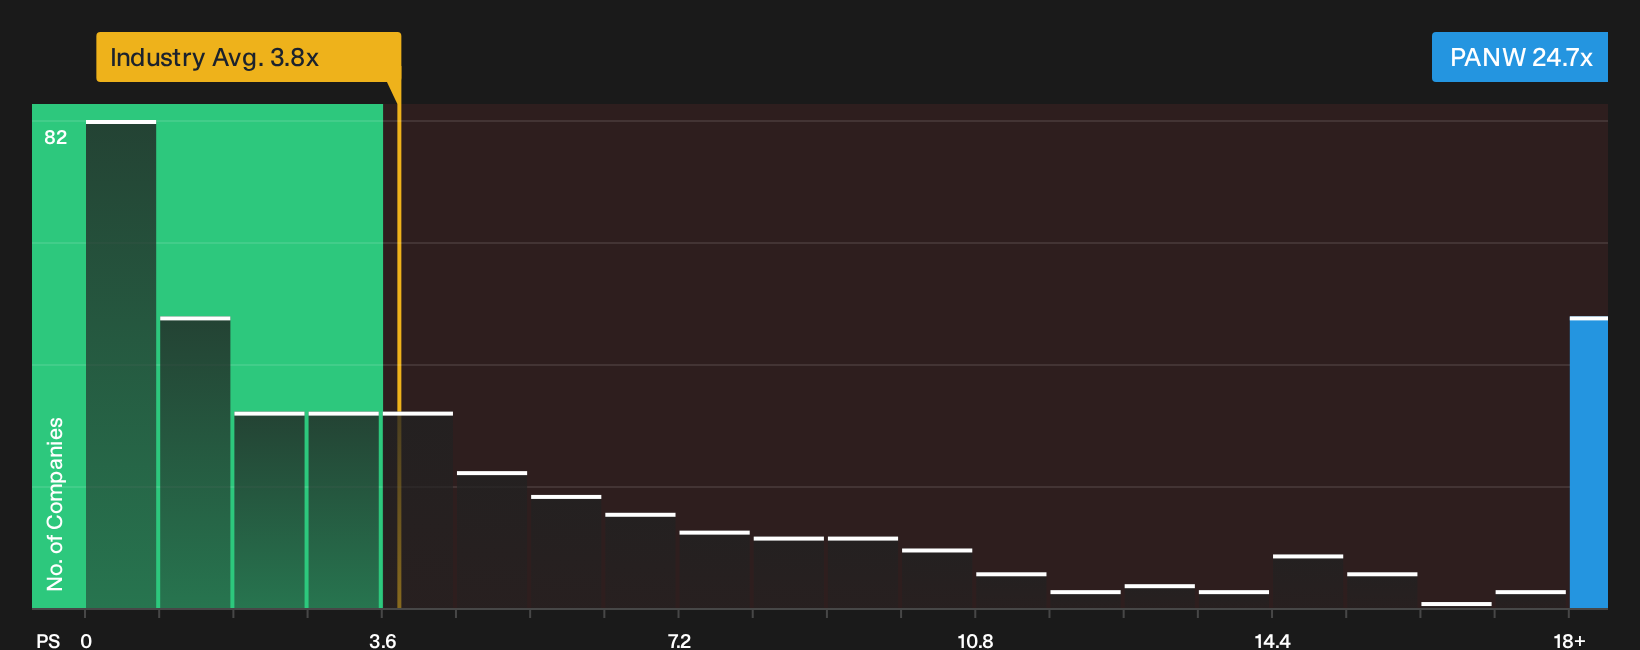
There is a very different reading of Palo Alto Networks when looking at P/S instead of fair value models. The stock trades at 24.7x sales, compared with 3.8x for the wider US Software group and 18.9x for peers, while the fair ratio sits at 14.7x. That gap points to meaningful valuation risk if sentiment cools or execution stumbles.
Investors weighing this richer P/S profile against the earlier fair value work may want to review what the raw numbers imply for upside or downside skew over time. They can then decide which set of assumptions feels more realistic for their own expectations See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these only help if you pressure test them yourself and move before the crowd settles on a story. Start by weighing both sides of Palo Alto Networks using the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Palo Alto Networks?
Palo Alto Networks may be the headline story today, but your portfolio deserves a deeper bench of opportunities that match different goals and risk levels.
- Target potential mispricing by scanning a curated set of quality companies that look cheap on fundamentals with the 35 high quality undervalued stocks.
- Strengthen your income stream by reviewing a focused group of high yield payers screened through the 8 dividend fortresses.
- Dial down portfolio stress by concentrating on financially resilient businesses using the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com