
WD 40 Could Be 26% Undervalued As Duluth Partnership Tests Brand Reach
Duluth Trading Co.'s new co-branded apparel line with WD-40 (WDFC) pushes the lubricant icon into workwear and fan gear, giving investors fresh context for the brand's reach and marketing ambitions.
Recent trading tells a mixed story for WD-40. The 30-day share price return of 6.34% contrasts with a 90-day share price decline of 15.32%, while the 1-year total shareholder return of 6.27% points to modest gains as brand campaigns and regular dividends keep the narrative alive.
Spot other branded consumer stocks aiming to turn loyal customers into long-term shareholders through our hand picked 20 high quality undiscovered gems.The share price climb over the past month, alongside a weaker 90 day and 5 year record, raises a simple tension. Are buyers reacting to WD-40's earnings power, or just resetting sentiment around a familiar brand story?
Most Popular Narrative: 26% Undervalued
WD-40's most followed valuation storyline pegs fair value at $271.67 per share, well above the recent $201.30 close. This frames the current Duluth partnership within a wider debate about long term earnings power and brand monetization.
Further geographic expansion of WD-40 maintenance products, with only about 25% of the estimated US$1.9b attainable market captured and strong double digit growth in countries such as China, India and Latin American markets, can add new volume and support revenue growth.
Continued premiumization of WD-40 Multi-Use Product, where Smart Straw and EZ-REACH already account for about half of revenue in this category with 30% to 45% price uplifts and relatively low penetration in many emerging markets, can keep shifting mix toward higher margin products and support gross margin and earnings.
See why 9 investors see WD-40 as 26% undervalued.
Result: Fair Value of $271.67 (UNDERVALUED)
Still, analysts flag rising petroleum based input costs and any shift toward a lower P/E multiple as two pressure points that could quickly challenge the WD-40 bull story.
Find out about the key risks to this WD-40 narrative.
Another View On WD-40’s Valuation
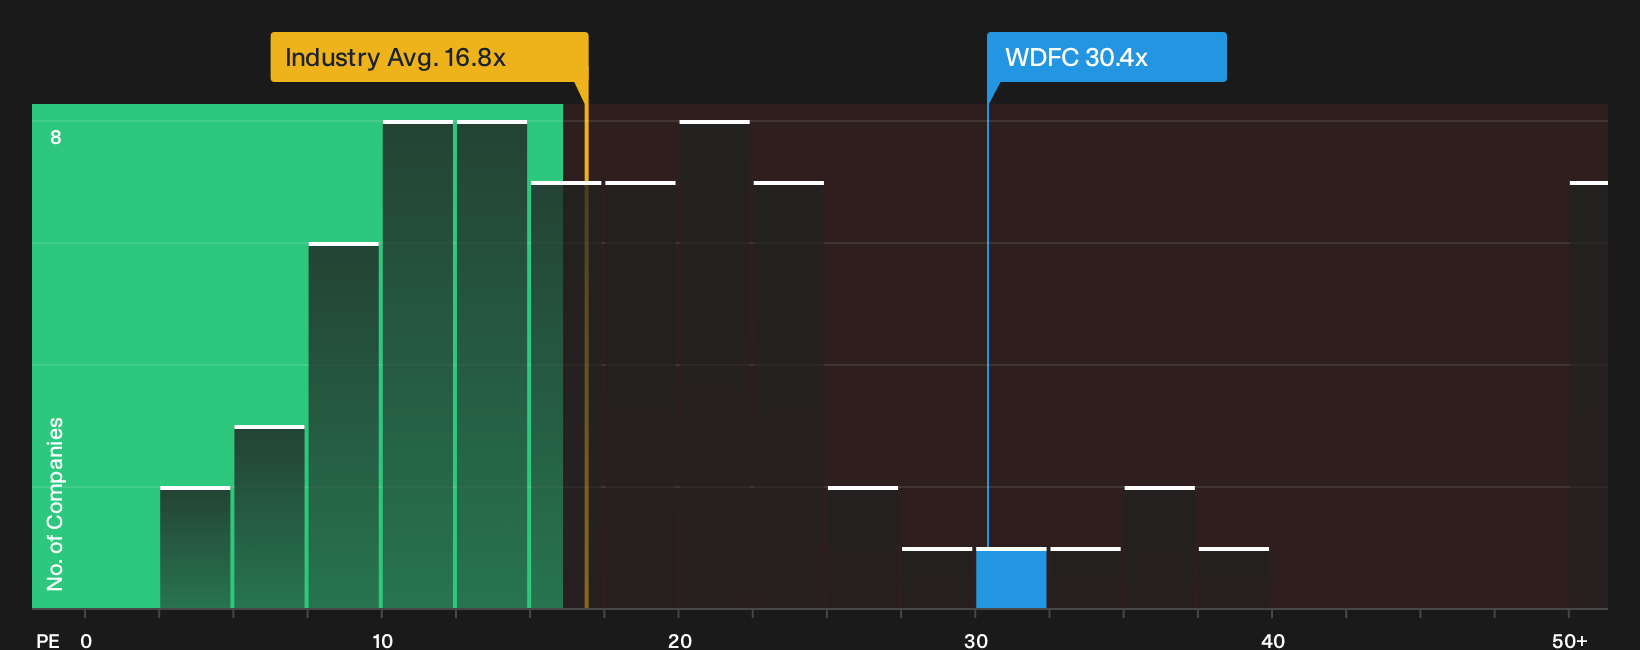
The analyst narrative paints WD-40 as 26% undervalued at $271.67 per share. A simple P/E check tells a different story. The stock trades at 30.4x earnings versus 17.5x for peers, 16.8x for the wider household products group and a fair ratio of 14.1x. That gap points to real repricing risk if sentiment cools.
For investors comparing WD-40 with other premium-priced brands, it helps to see how the current P/E stacks up visually and where it could drift toward the fair ratio over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
After all this optimism around WD-40's brand strength and valuation stories, your verdict matters most. Move quickly, review the upside case, and pressure test the 3 key rewards.
Looking for more investment ideas beyond WD-40?
Do not stop with one ticker. Use the Simply Wall St screener to line up fresh prospects and avoid missing opportunities that fit your playbook.
- Target potential mispricing by scanning a curated pool of quality companies that look cheaper than their fundamentals suggest through the 35 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses screened for sturdier finances and healthier balance sheets using the list of solid balance sheet and fundamentals (25 results).
- Seek out cash return potential by zeroing in on companies that combine higher yields with durability using the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com