
Radware (RDWR) Could Be 46% Above Fair Value Following Its AI Security Launch
Radware (NasdaqGS:RDWR) drew fresh attention after unveiling MCP Server Protection, a new layer in its cloud security platform that is aimed at securing Model Context Protocol infrastructure as enterprises lean further into AI agents.
Recent trading shows that Radware’s share price momentum has cooled slightly in the short term, with the 30 day share price return of 1.75% and 90 day share price return of 4.63%. At the same time, the year to date share price return of 20.35% and 3 year total shareholder return of 84.53% point to a stronger underlying trend that the MCP Server Protection launch could influence as investors reassess growth potential and risk around AI focused security spending.
Surf 55 AI infrastructure stocks to see which other security vendors could benefit if demand for protecting AI agents and MCP-style infrastructure broadens beyond Radware.Radware now trades only modestly below the average analyst target, even after the MCP Server Protection announcement caught fresh attention. Is that discount reflecting healthy caution or mispricing the AI security opportunity?
Preferred P/E of 69.7x: Is it justified?
Valuation on Radware today is being framed by a rich P/E of 69.7x, set against a last close of $28.62 and a relatively small 6.6% gap to the $30.50 average analyst target.
The P/E multiple measures how much investors are currently willing to pay for each dollar of Radware's earnings. For a cybersecurity and application delivery specialist where growth, product relevance and contract visibility matter, this ratio often reflects how durable investors believe earnings power could be, rather than just what has been reported in the latest twelve months.
Radware shows earnings growth of 16% per year over the past 5 years, with profit growth of 21.9% over the last year and net profit margins at 5.4% compared with 4.9% previously. That track record helps explain some of the premium, although reported earnings also include a large one off gain of $4.6m in the last twelve months, which can inflate the P/E without reflecting ongoing performance.
The comparison with peers is stark. Radware trades on a P/E of 69.7x compared with the US Software industry average of 30.8x and a peer group average of 28.5x. Those gaps suggest the market is assigning Radware more than double the earnings multiple of similar software businesses, which points to expectations that are materially higher than what sector averages imply.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 69.7x (OVERVALUED)
Still, the high P/E leaves Radware exposed if AI focused security spending softens or if one off gains fade faster than the market currently assumes.
Find out about the key risks to this Radware narrative.
Another View: What The DCF Says About Radware
A second lens on Radware comes from the SWS DCF model, which points to a future cash flow value of $19.60 per share. With the stock at $28.62, that framework suggests the shares are overvalued, so investors are paying a clear premium to the model assumptions.
For anyone weighing whether that gap is a red flag or a calculated bet on AI security demand, Look into how the SWS DCF model arrives at its fair value.
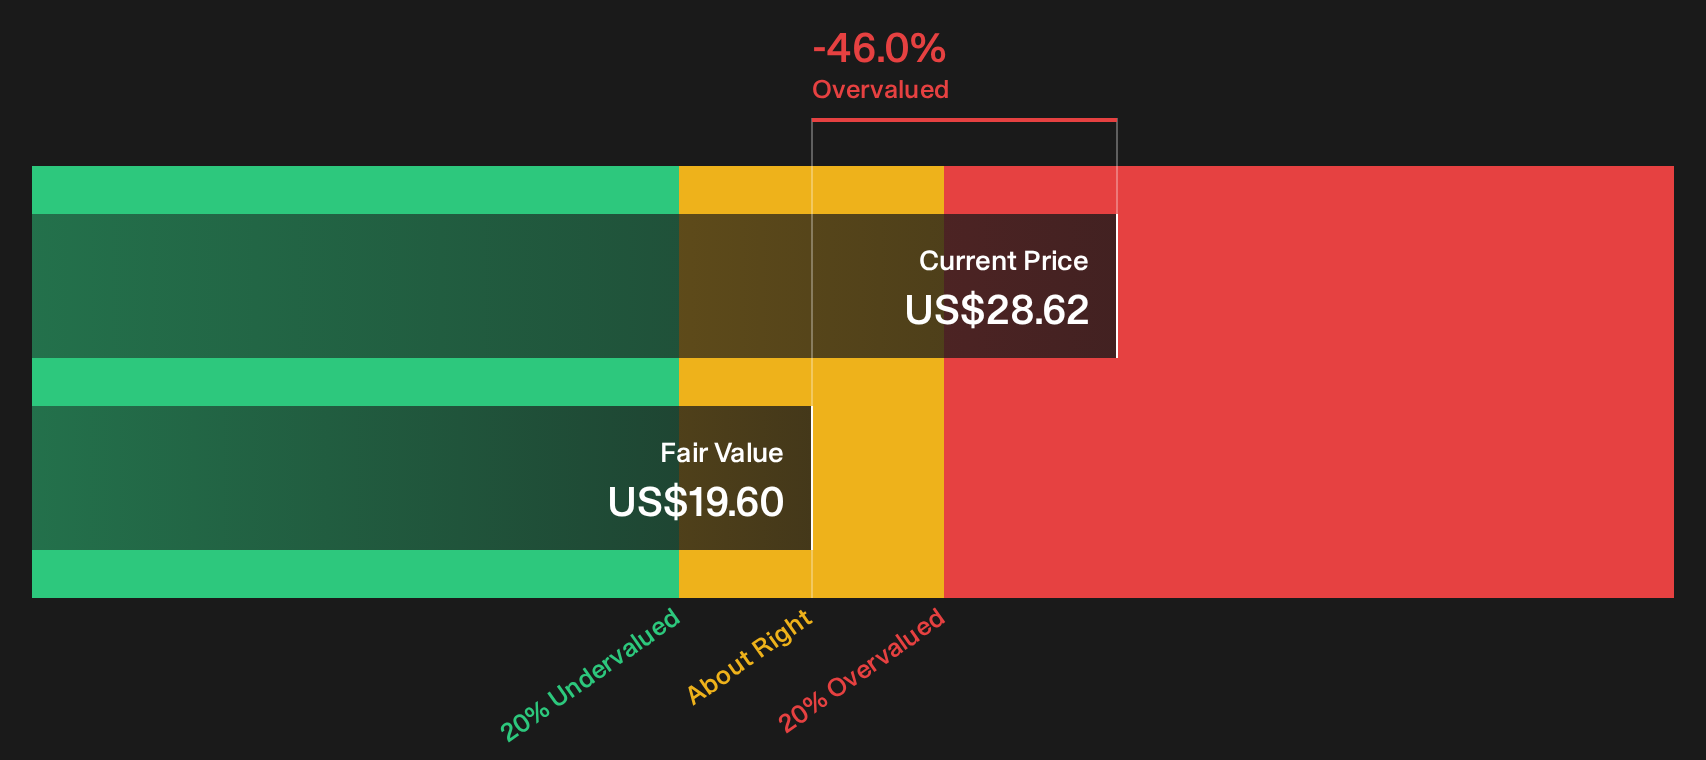
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Radware for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Radware’s valuation and AI security potential can influence sentiment in both directions, so move quickly, review the underlying figures, and weigh the 1 key reward and 2 important warning signs
Ready to act on your next idea beyond Radware?
If Radware has sharpened your thinking on AI security, do not stop there. Use the Simply Wall Street Screener to quickly spot other focused opportunities.
- Target reliable income by zeroing in on companies that show up as 8 dividend fortresses for investors who want yield with substance behind it.
- Hunt for quality at a discount by scanning the 35 high quality undervalued stocks that might align better with your return expectations and risk limits.
- Protect your downside by filtering for 32 resilient stocks with low risk scores so you are not the one chasing excitement while others quietly manage volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com