
Sat Out Stanley Black & Decker's Rally? Here Is What Holders Saw
Stanley Black & Decker spent the year talking about billion dollar US manufacturing and R&D plans, factory closures, and fresh tool launches, yet the real story for investors sits in the payoff that followed. For Stanley Black & Decker shareholders, the return over the past year was 37.6%, including dividends. If you had been weighing a purchase back on 2025-10-19, what exactly would you have needed to believe before any of this news landed?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Stanley Black & Decker has already moved. See which of 35 high quality undervalued stocks still trade below our estimates.
The Argument Stanley Black & Decker Investors Were Really Weighing
The shares cost US$67.85 at the start, and anyone looking at Stanley Black & Decker then had to choose between two very different but reasonable stories.
On the optimistic side, the bullish Narrative put Fair Value at US$86.49, assuming global urbanization and heavier investment in digital tools and software would support tool demand and margins across more regions.
The cautious view set Fair Value at US$64, focused on aging populations and tariff driven cost pressures that could squeeze profit margins even if revenue still grew.
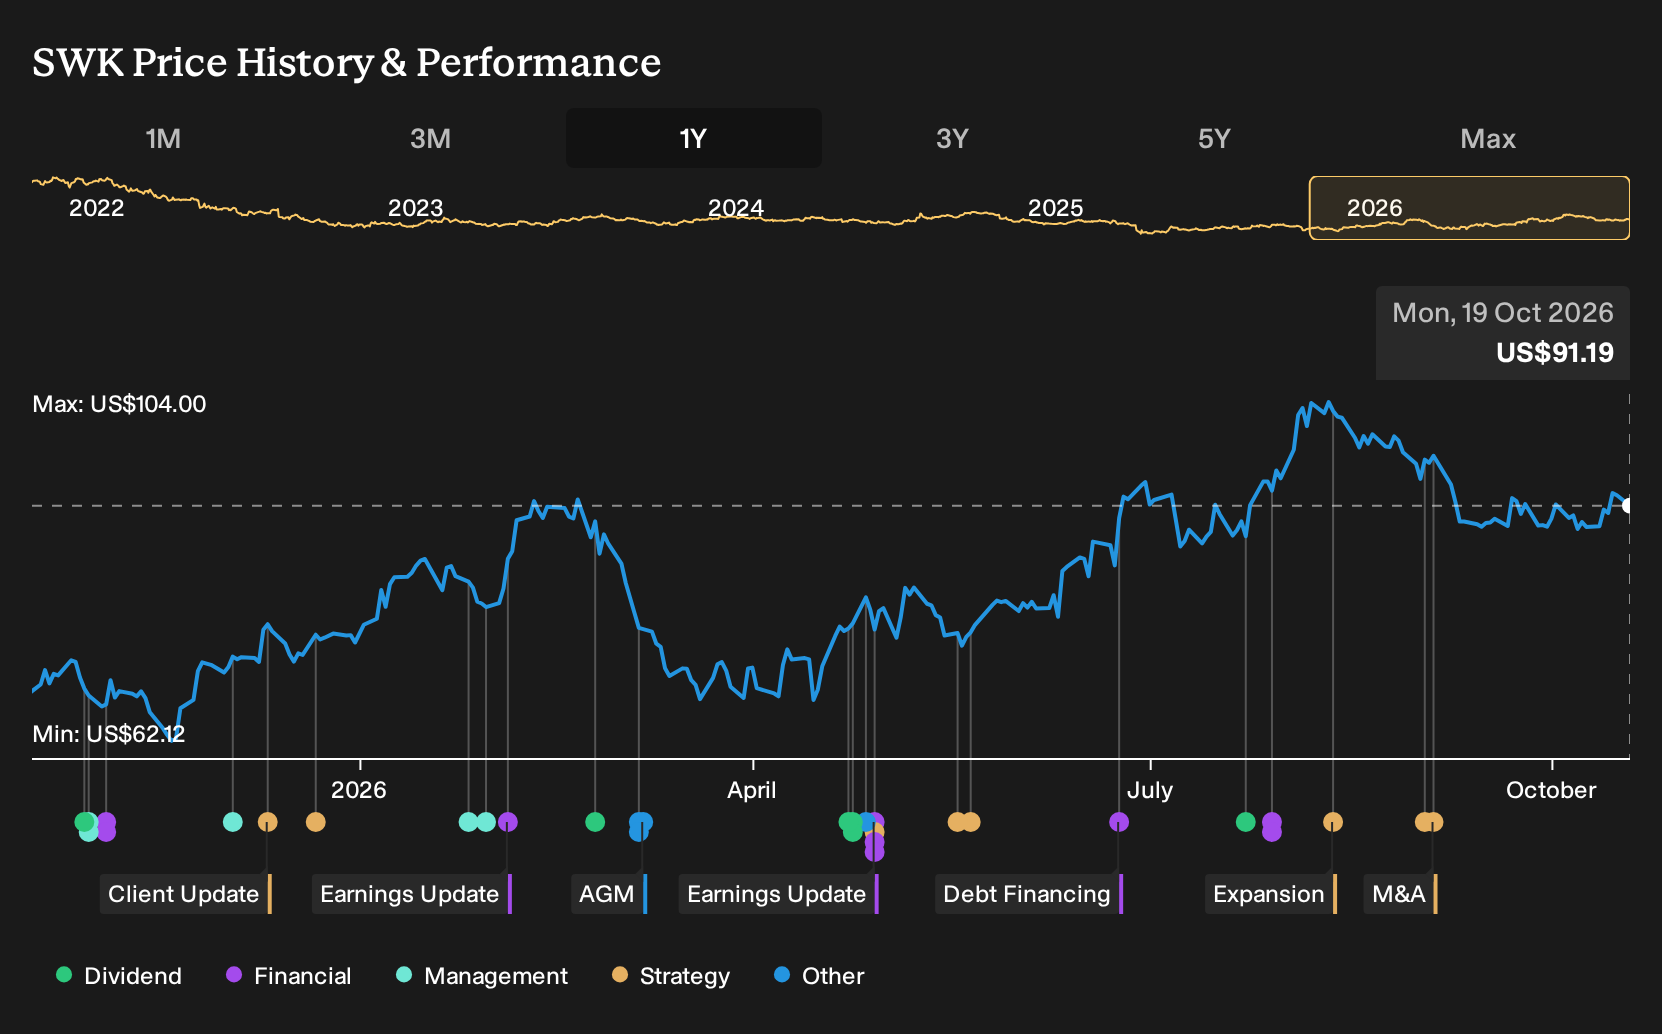
What The Stanley Black & Decker Evidence Actually Tested
Stanley Black & Decker’s Q2 2026 numbers gave the bullish story fresh support. Net income excluding extra items moved from US$101.9 million in Q2 2025 to US$351.3 million, with net margin rising from 2.6% to 8.9% on essentially flat revenue. Factory closures in New Britain and Gallatin, plus a securities lawsuit, pulled in the cautious case on execution risk.
The real hinge was profitability resilience. For any other stock, you would want to check whether margin targets are showing up in the income statement instead of only in speeches and transformation plans.
What Stanley Black & Decker's Price Already Assumes
Stanley Black & Decker now trades at US$91.19 after a 37.6% gain over the past year, so buyers are stepping into a very different story than a year ago. The selected Narrative sees Fair Value above that quote and ties the gap to how far newer projects move the earnings mix.
The focus has shifted to professional users, automation and software layered onto tools rather than broad consumer demand alone. The key question for anyone paying today is whether the push into higher value commercial and industrial channels can keep supporting the higher profitability the Narrative is built around.
"The push by Stanley Black & Decker into U.S. commercial and industrial channels, where power tools revenue in these channels grew at a low double digit rate while management expects this route to approach 10% of Tools & Outdoor sales in 2026, creates room for a higher mix of professional projects such as data centers and power generation work that could lift average selling prices and support revenue growth beyond what a flat broader market implies."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 31% below our estimate - targets data center customers needing high performance GPU racks for AI workloads.
- Company 2 - 45% below our estimate - converts a record backlog of complex mechanical projects into modular manufacturing utilization gains.
- Company 3 - 49% below our estimate - pursues online betting users shifting from offline play using proprietary technology and focused marketing.
Three companies from the same screener. Open every one of the 25 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com