
How Investors May Respond To Argan (AGX) $2.5b Power Backlog
- Argan reports a committed project backlog of about US$2.5b, with roughly 80% tied to natural gas power projects and 11% to renewables, anchoring future work in large scale energy infrastructure for data centers and other electricity intensive facilities.
- The heavy tilt toward dispatchable gas fired plants gives Argan concentrated exposure to how grid spending priorities and project economics evolve over time.
- We will look at how Argan's investment narrative is shaped by this US$2.5b power focused backlog and growing dispatchable demand.
Scan for other power and grid builders that could benefit from the same surge in energy hungry data centers by checking the hand picked 42 power grid technology and infrastructure stocks alongside Argan.
Argan Investment Narrative Recap
To own Argan, you need to be comfortable with a very power heavy story. The US$2.5b backlog tied mostly to gas projects anchors near term activity to data center and grid demand, while exposing you to how utilities and regulators prioritize dispatchable capacity. The key short term swing factor is execution on those large contracts and how that flows through to margins.
The biggest risk right now sits in profitability compression, especially with Industrial segment work already running at thinner 7.3% gross margins and some projects expected to weigh on results for another quarter or two. The latest backlog mix does not fundamentally change that risk, so the impact of the news looks more like confirmation than a reset.
With no fresh company announcements disclosed around this news, the most relevant reference point is Argan’s existing guidance around its ability to run 10 to 12 complex gas jobs at once and its capital light EPC structure with about US$1.0b of cash and investments and no debt. That financial position gives management room to absorb project timing swings.
For you as a shareholder, the link between this power heavy backlog and those earlier comments on execution capacity is important. The more Argan leans into multi gigawatt gas and data center related work, the more project delivery, Industrial margin stabilisation and disciplined use of that cash pile become the practical catalysts to watch rather than any single headline contract win.
Argan's current analyst narrative points to revenues of US$1.8b and earnings of US$233.8 million by 2029, built on an assumed 15.2% yearly revenue growth rate and an earnings increase of about US$54.5 million from the US$179.3 million reported today.
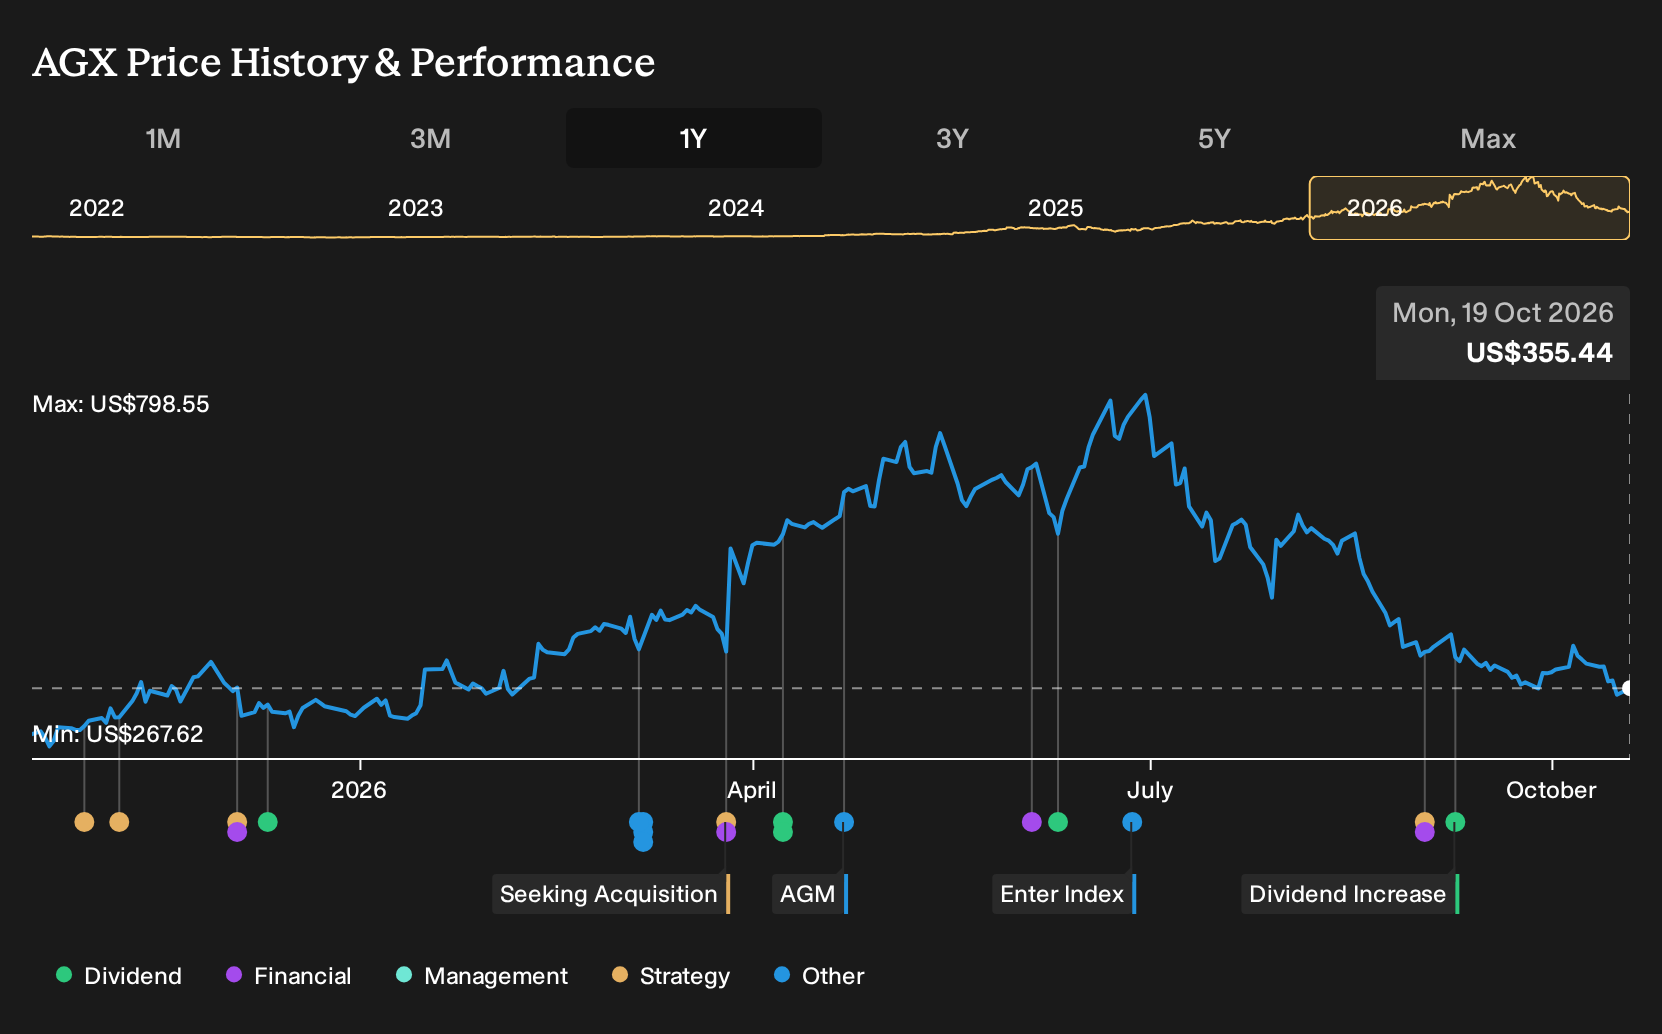
Uncover why Argan's fair value indicates a 61% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Argan focuses less on margin risk and more on a potential upside catalyst if the power buildout proves stronger than consensus. The most optimistic analysts were already modeling revenue of US$2.5b and earnings of US$322.2 million by 2029. Those pre news forecasts could shift meaningfully once this backlog update is fully reflected in estimates.
Explore 3 other Argan fair value estimates, including one that suggests potential upside of up to 61% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Argan research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Argan. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Argan's overall financial health at a glance.
Looking For More Investment Ideas Beyond Argan?
If you want to stress test your thesis on Argan, it helps to compare it with other businesses that share some of the same themes. The Simply Wall St Screener can surface different angles on quality, value and risk, so you can line Argan up against a broader watchlist rather than viewing it in isolation.
- If capital preservation is top of mind, start with companies that screen well on balance sheet strength and fundamentals through the list of solid balance sheet and fundamentals (25 results).
- If income is a priority, broaden your hunting ground beyond Argan by reviewing a curated set of high yield opportunities via the 8 dividend fortresses.
- If you want to hunt for under followed ideas, use the Screener to surface a focused pool of quality prospects with solid fundamentals through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com