
Learn Why The Bull Case For First Hawaiian Stock Could Change Following Earnings Estimate Revision
- First Hawaiian is heading into its September 2026 quarter with a consensus earnings forecast of $0.60 per share and net interest income growth that has trailed sector levels over the past five years.
- The upward 7.5% revision to quarterly EPS estimates highlights how higher expectations are converging with a business that has experienced slower profitability momentum than many peers.
- It remains to be seen how this higher earnings bar for First Hawaiian could influence the broader investment narrative around its future profitability.
First Hawaiian Investment Narrative Recap
For you to be comfortable owning First Hawaiian, you need to believe that a slower growing, community focused bank can still compound earnings through disciplined lending and stable deposits. The key short term catalyst is execution around net interest income, especially given a five year record that has trailed sector trends. The recent 7.5% EPS estimate revision lifts the bar, but it does not fundamentally change that core thesis.
The biggest near term risk is that funding costs or deposit mix move against First Hawaiian while earnings expectations are resetting higher. If profitability momentum stalls again relative to peers, the story of an underappreciated Pacific bank with improving returns becomes harder to support in the next few quarters.
The most relevant piece of information for this earnings reset is the expectation that First Hawaiian will post US$0.60 in EPS for the September 2026 quarter, with that figure now sitting 7.5% above where it was a month ago. That shift indicates that the hurdle on near term profitability is higher even though the bank’s long term balance sheet profile has not changed.
This kind of reset interacts directly with the existing catalysts around revenue growth forecasts and cost efficiency. If the franchise can convert its community banking footprint and low cost deposit base into consistent earnings at or above that US$0.60 level, the broader narrative around forecast revenue and earnings growth remains intact. If not, concerns about net interest margin pressure and dependence on the Hawaiian economy move to the foreground.
First Hawaiian's narrative projects US$1.8b revenue and US$620.2 million earnings by 2029. This projection is based on 27.7% yearly revenue growth and assumes earnings will increase from US$284.9 million today to US$620.2 million by the 2029 forecast year.
Uncover why First Hawaiian's fair value indicates a 19% potential upside to its current price, which could narrow quickly.
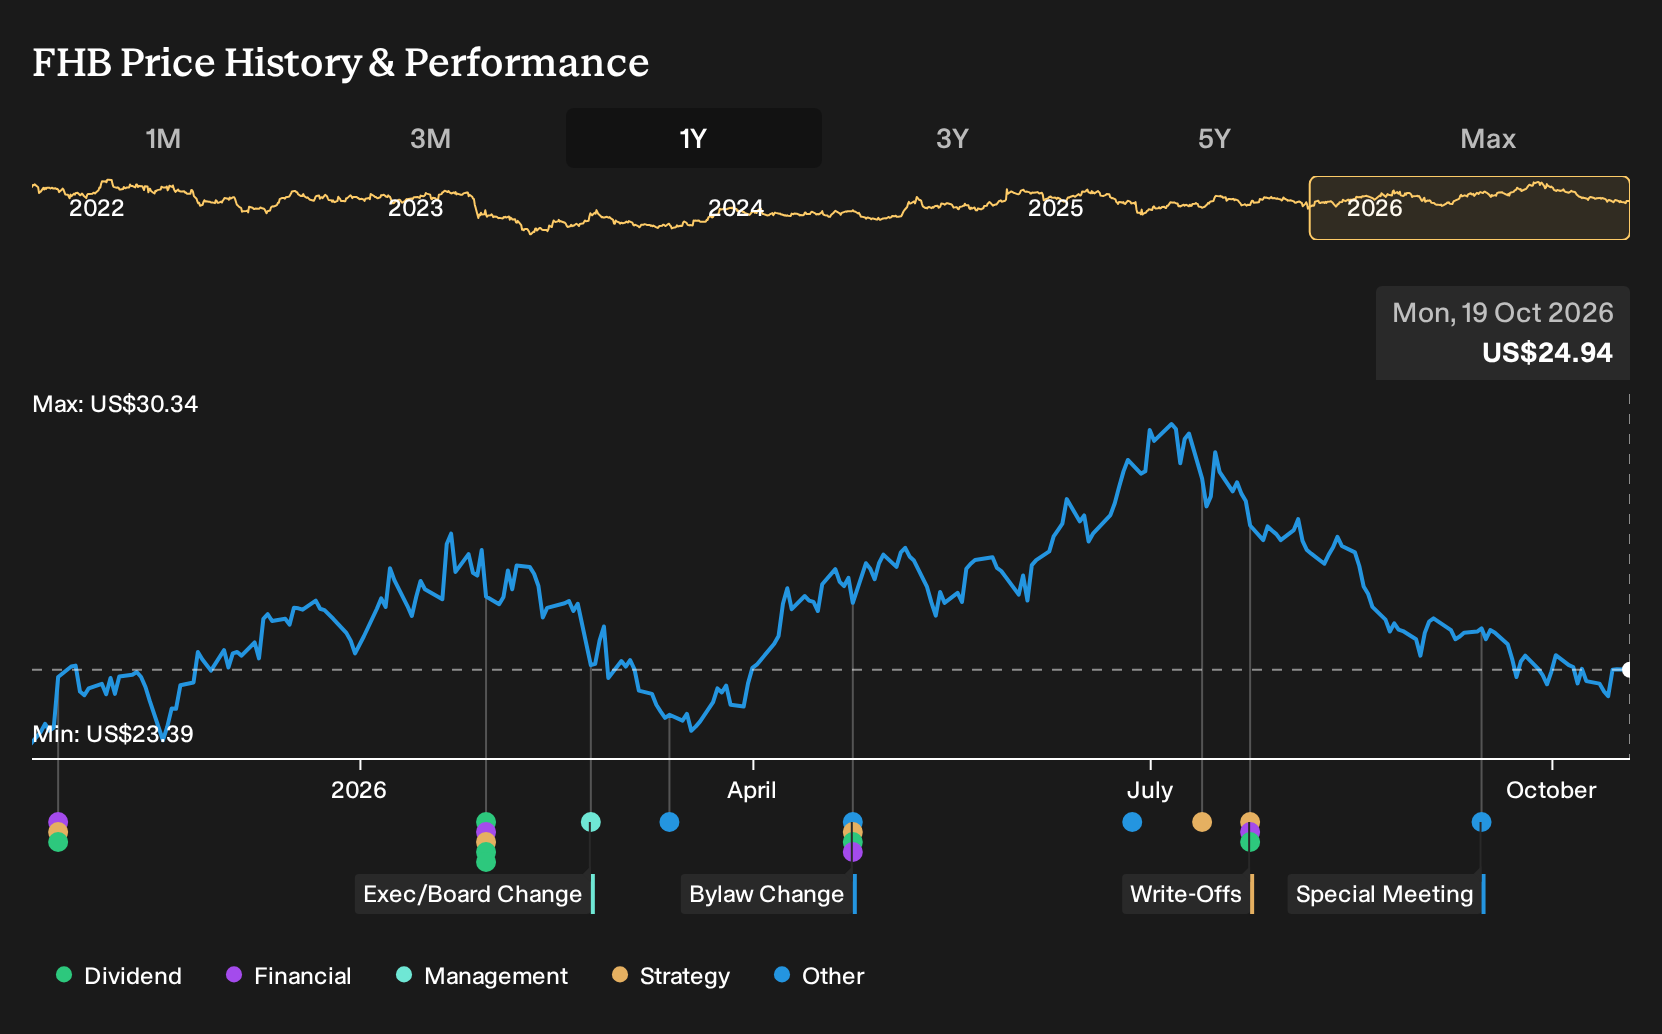
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$29.78 to US$46.49, which shows how far apart retail investors can be on First Hawaiian. You can use that spread as a prompt to stress test your own stance against deposit risk, TriCo integration execution and the wider implications for earnings resilience.
Explore another First Hawaiian fair value estimate, including one that suggests it could be worth just $29.78.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and go with your instincts.
- A great starting point for your First Hawaiian research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for First Hawaiian. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Hawaiian's overall financial health at a glance.
Looking For More Investment Ideas Beyond First Hawaiian?
If the First Hawaiian story has you rethinking where risk, balance sheet strength, and income potential fit in your portfolio, you may want to broaden the search using the Simply Wall St Screener. You can quickly filter for different styles of opportunities and let the data surface ideas that match the type of businesses you want to research next.
- For investors hunting for strong businesses that the market may be overlooking, scan our 20 high quality undiscovered gems and see which companies have fundamentals that warrant a closer look.
- If capital preservation is a priority, narrow the field to steadier candidates by screening for 32 resilient stocks with low risk scores that might better fit a more defensive approach.
- For those who want income while still keeping an eye on quality, shortlist potential yield ideas with our 8 dividend fortresses and check which payouts align with your risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com