
Quantinuum (QNT) Stock Looks Above Fair Value Even After A 42% Fall
Quantinuum has seen its share price fall sharply this year, and that slide throws a spotlight on a simple question for investors who care about fundamentals. Is the current market value still in line with what the company’s book value can support?
- The stock is down 42.1% year to date, which puts extra weight on whether the balance sheet and recorded equity justify where the price now sits.
- A recent breakthrough in quantum error correction, which targets fault tolerant computing by 2029, can shape how investors think about future capital needs and how much today’s book value captures the cost of getting there.
- There is a second opinion on Quantinuum worth weighing. See what analysts think Quantinuum's shares could be worth.
For investors, the debate is whether Quantinuum's current share price fairly reflects the strength and risks embedded in its book value.
If you want a broader starting point for research around quantum hardware and similar themes, take a look at 25 quantum computing stocks.
Does Quantinuum Look Pricey on Book Value?
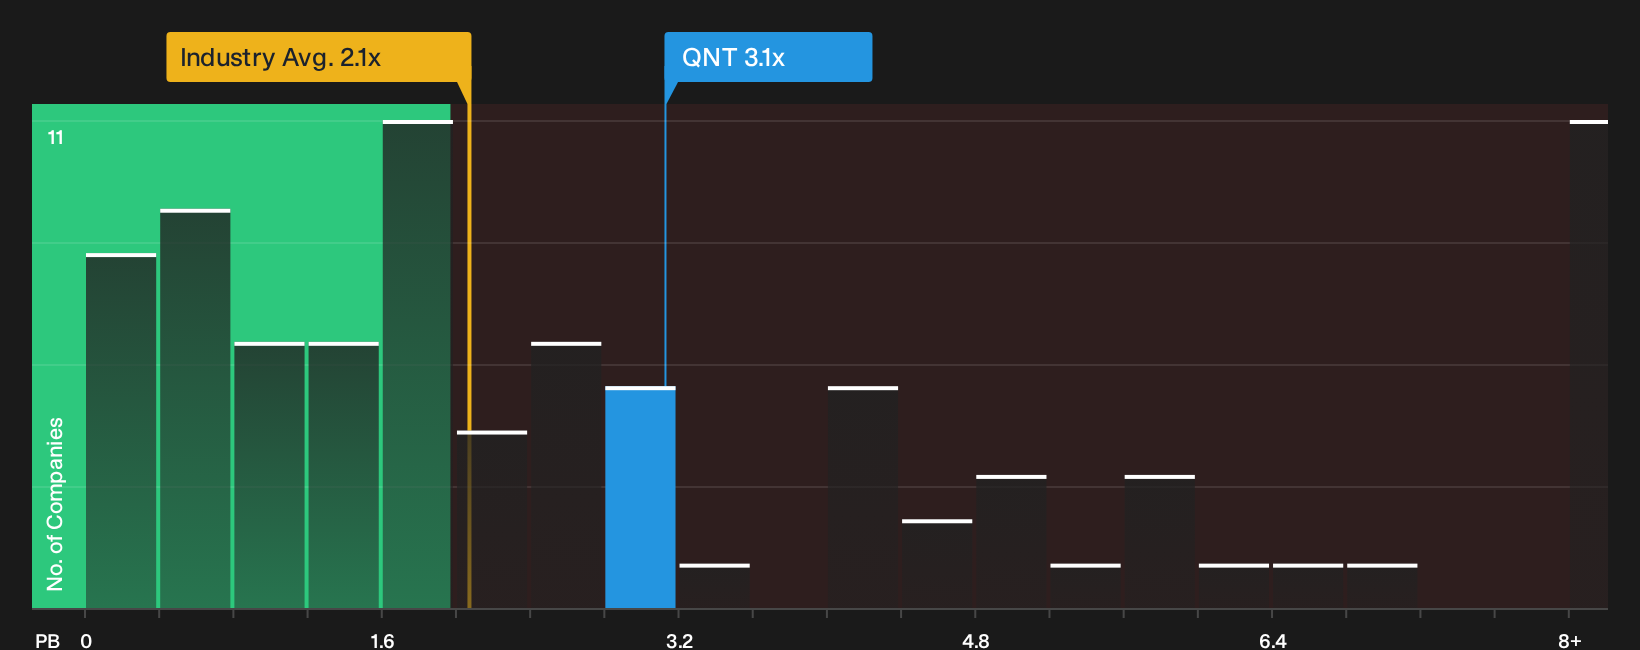
The P/B ratio suits Quantinuum because tangible equity carries more weight than earnings for a quantum hardware player still working through heavy investment. Quantinuum trades on a P/B of 3.1x, which sits above the IT industry average of around 2.1x and above the peer group near 2.1x. That signals investors are currently willing to pay a richer price for each dollar of net assets on the balance sheet than they pay for comparable businesses.
Because the recent quantum error correction breakthrough has sharpened expectations around the Apollo roadmap, the market is treating the existing equity base as more valuable than a typical hardware peer, even after this year’s share price drop. On this simple yardstick the stock screens overvalued against sector norms. You would need to decide whether the quantum roadmap, capital intensity and execution risk justify that premium or argue for a narrower gap. Explore the numbers behind Quantinuum's P/B valuation.
The Quantinuum Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Quantinuum's P/B puzzle leaves off by explaining which combinations of growth, margins and future earnings would need to hold for the stock to be worth materially more or materially less than today's price on the Community page. Each narrative ties a fair value estimate to a specific set of potential catalysts and downside risks so you can track over time which version of Quantinuum's story feels closest to reality.
One of the top community narratives on Quantinuum: 64% undervalued
"Quantinuum is integrating quantum systems with AI and high performance computing through partners such as Oracle and HPE..."
Discover why this Narrative puts Quantinuum at 64% undervalued.
One more Quantinuum check sits outside the balance sheet
There is a final piece that belongs next to Quantinuum's book value and P/B work, which is how professional analysts model the business a few years from now and where those expectations cluster. Explore where analysts expect Quantinuum to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com