
Eton Pharmaceuticals (ETON) Stock May Be Trading At A Premium Following Its Huge Three Year Run
Eton Pharmaceuticals has seen its share price move sharply in recent years, and that kind of run naturally raises a simple question for you as an investor: Is the current stock price still in line with what the business is earning today and what those earnings may reasonably support over time?
- Over the past 3 years, Eton Pharmaceuticals has delivered a very large share price gain, which now puts the focus squarely on whether those returns are backed by earnings power.
- The recent U.S. licensing deal for LIBERVANT, with potential commercial availability targeted for April 2027 and patent protection into 2038, can influence how investors think about the timing and durability of future profit streams that feed into earnings based valuation work.
- Your read on Eton Pharmaceuticals is one view; the desks covering it have another. See what analysts think Eton Pharmaceuticals's shares could be worth.
The stock's next move may depend on whether Eton Pharmaceuticals' current earnings profile can justify where the share price sits today.
If you are weighing Eton Pharmaceuticals against other ideas tied closely to earnings power, a focused screen of 35 high quality undervalued stocks can be a useful next stop in your research.
Is Eton Pharmaceuticals Getting Expensive on Earnings?
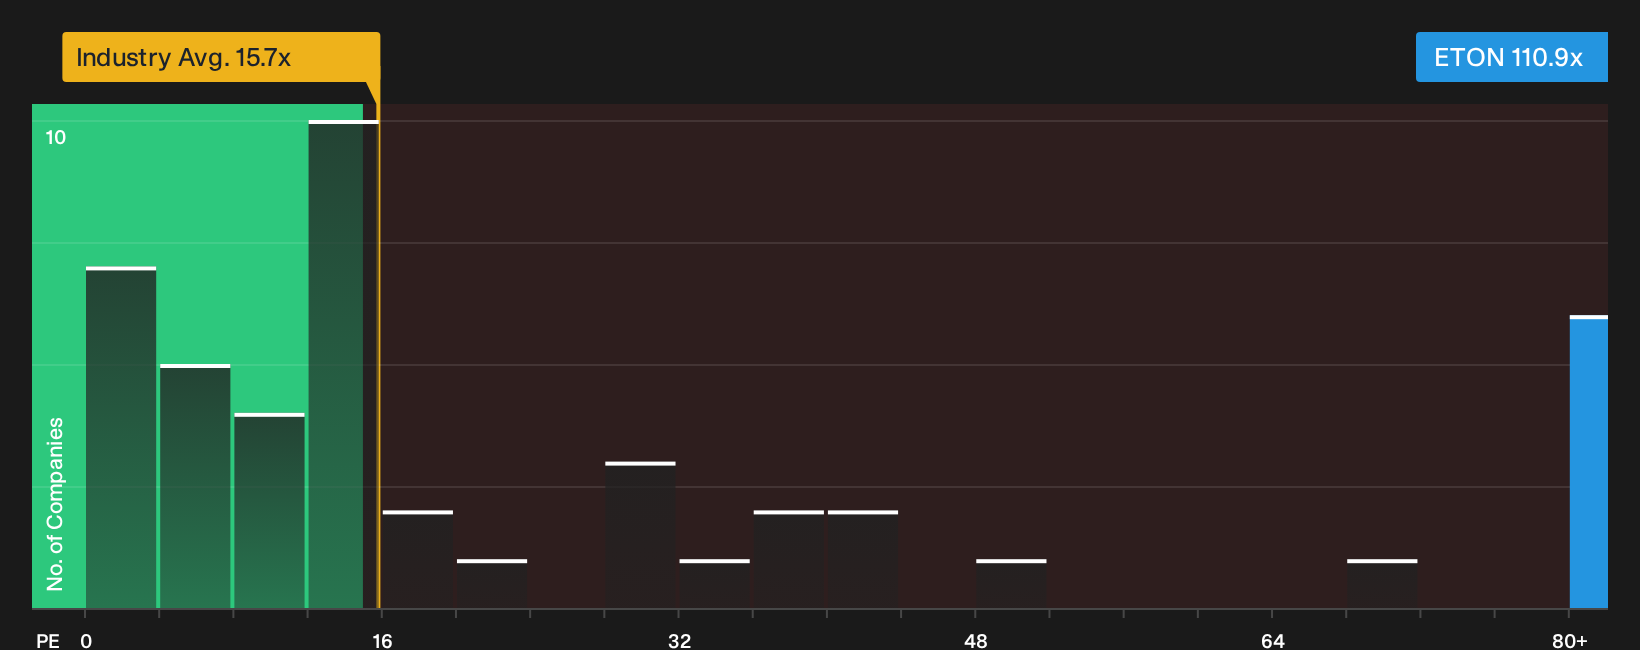
The P/E ratio is a useful way to think about what you are paying today for each dollar of Eton Pharmaceuticals earnings. On this measure, the stock changes hands at about 110.9x, which is far above the broader pharmaceuticals sector average of around 15.7x and also well ahead of the peer group level of roughly 33.7x.
Because the recent LIBERVANT licensing news has sharpened interest in future profit potential, it is important to note that the current P/E already bakes in a rich earnings premium. The tailored fair multiple implied by the valuation framework sits well below the current 110.9x figure, and the gap is large enough that it reflects a model that is heavily penalising the Eton Pharmaceuticals risk profile and current earnings base rather than pointing to a precise target. That leaves you weighing how much of the LIBERVANT opportunity and other pipeline or product execution you believe is already reflected in this very high earnings multiple before committing fresh capital to the stock. Explore the numbers behind Eton Pharmaceuticals's P/E valuation.
The Eton Pharmaceuticals Narrative: What Would Justify Today's Price?
Narratives for Eton Pharmaceuticals pick up where the valuation puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the current share price to look meaningfully too high or too low. Each scenario anchors its number to a specific view on how Eton Pharmaceuticals' growth, margins and risk profile could evolve, giving you a reference point you can revisit as fresh information comes through.
One of the top community narratives on Eton Pharmaceuticals: 31% undervalued
"Eton's investments in digital patient support platforms, targeted education campaigns, and specialist distribution are removing historical barriers to access and supporting higher therapy adoption…"
Discover why this Narrative puts Eton Pharmaceuticals at 31% undervalued.
The next question for Eton Pharmaceuticals sits with the people in charge
Pricing can only tell part of the story for Eton Pharmaceuticals, because the track record and pay structure of the leaders steering the business help shape how that valuation evolves from here. See who runs Eton Pharmaceuticals and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com