
How Investors May Respond To Cadence Stock Ahead Of Earnings Growth
- Cadence Design Systems is preparing to report its September 2026 quarter, with analysts expecting higher earnings per share and revenue supported by an existing record US$8.1b backlog.
- The key consideration is how anticipated earnings strength, driven by demand across EDA, IP and hardware, interacts with a premium P/E and existing AI growth expectations.
- We will now look at how Cadence Design Systems' investment narrative could be affected by the anticipated earnings strength highlighted in these updates.
Scan beyond Cadence Design Systems and see how other potential earnings movers with AI exposure compare in our curated list of 55 AI infrastructure stocks.
Cadence Design Systems Investment Narrative Recap
To own Cadence Design Systems, you effectively need to believe that AI driven chip complexity and tighter design cycles will keep pulling more work into its EDA, IP and hardware platforms. The near term swing factor is how much the October 26 earnings release validates that story around AI super agents, IP at advanced nodes and the large recurring backlog.
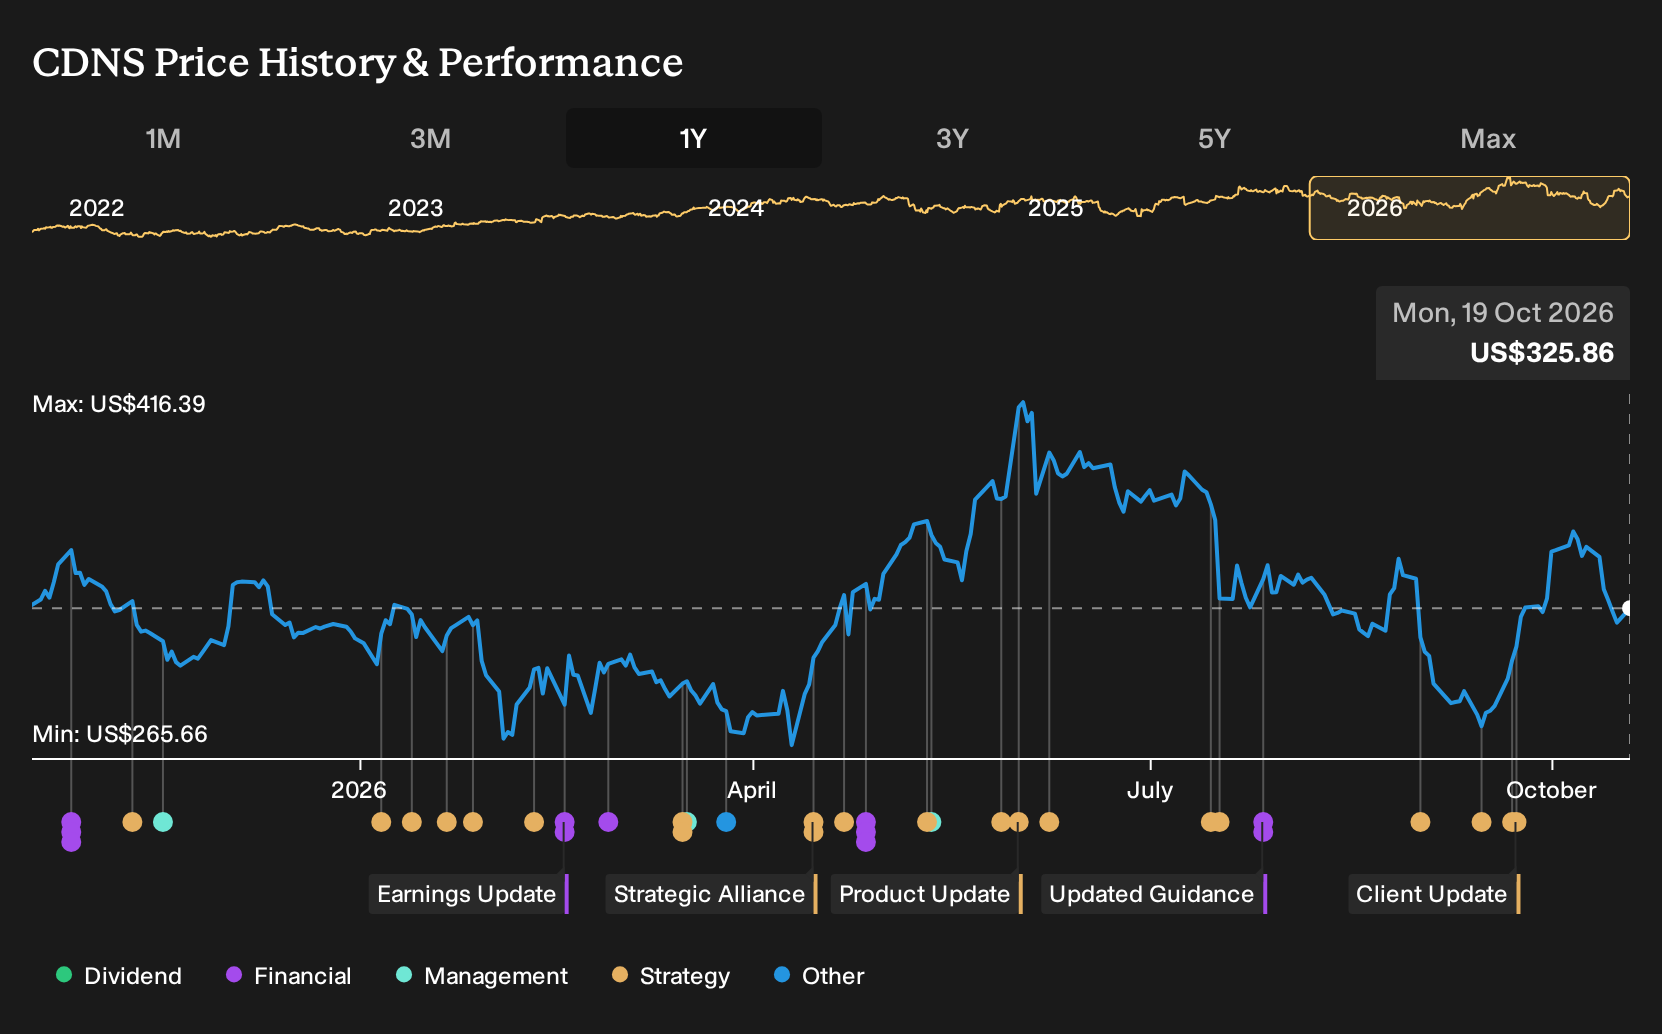
The largest risk right now is execution against that premium P/E and the cost drag from integrating Hexagon Design & Engineering while China exposure stays sensitive to export controls. The recent share price strength and higher estimates raise expectations, but do not materially change those core near term risks and catalysts.
The most relevant recent update is the expectation for a year over year earnings increase for the September 2026 quarter, driven by higher revenue and backed by the US$8.1b backlog. Analyst estimate revisions have moved up into this print, which indicates the market is treating this release as a meaningful check on Cadence Design Systems’ operating momentum.
For investors, the link back to catalysts is straightforward. Stronger earnings would help show that AI super agents, higher value IP content and the Intel Foundry collaboration are converting into revenue, even while Hexagon integration adds US$20m to US$25m of operating expense in the second half of 2026 and China, valuation and margin expectations remain key watchpoints.
Cadence Design Systems' current analyst narrative points to US$8.4b in revenue and US$2.0b in earnings by 2029, based on assumptions of 12.9% yearly revenue growth and an earnings increase of about US$600m from US$1.4b today.
Uncover why Cadence Design Systems' fair value indicates a 24% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bullish twist you may want to check is the idea that Cadence Design Systems turns its AI super agents into a margin engine. The most optimistic analysts were already penciling in revenue of about US$9.3b and earnings of US$2.7b by 2029 before this earnings update, so their story could shift again once the October 26 numbers land.
Explore 5 other Cadence Design Systems fair value estimates, including one that suggests as much as 44% potential increase from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cadence Design Systems research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cadence Design Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cadence Design Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cadence Design Systems?
If Cadence Design Systems has sharpened your interest in AI and high quality platforms, use that curiosity to widen your watchlist with a few focused stock searches.
- For potential value opportunities where quality and price both matter, check companies that appear in our 35 high quality undervalued stocks.
- If capital preservation and steadier risk profiles are a priority, scan through the 32 resilient stocks with low risk scores to see which businesses fit that brief.
- When balance sheet strength is non negotiable, start with the list of solid balance sheet and fundamentals (25 results) and filter for fundamentals that match your own criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com