
Strive (ASST) Stock Could Look Pricey Following Its SATS Stock Offering
Strive has had a volatile run over the past year, and the stock’s swings now put a simple but important question on the table for investors who focus on balance sheet strength. Is the current share price meaningfully supported by the company’s book value, or is the recent move asking you to pay up for something the accounts do not fully capture yet?
- Over the past 12 months, Strive has delivered a 47.8% gain, which raises the stakes on whether that rise lines up with the value recorded on its balance sheet.
- The recent pricing of Strive’s upsized 15.00% Series A Perpetual SATS Preferred Stock, which targets about US$630 million in gross proceeds, may reshape how you think about its capital structure and the equity cushion that underpins book value per share.
- There is a second opinion on Strive worth weighing. See what analysts think Strive's shares could be worth.
The issue now is whether Strive’s current market price can be squared with its book value when set against the industry average.
If you are considering whether Strive’s 47.8% one year gain still aligns with its book value, it can be helpful to compare that question across 35 high quality undervalued stocks.
Is Strive Getting Expensive on Book Value?
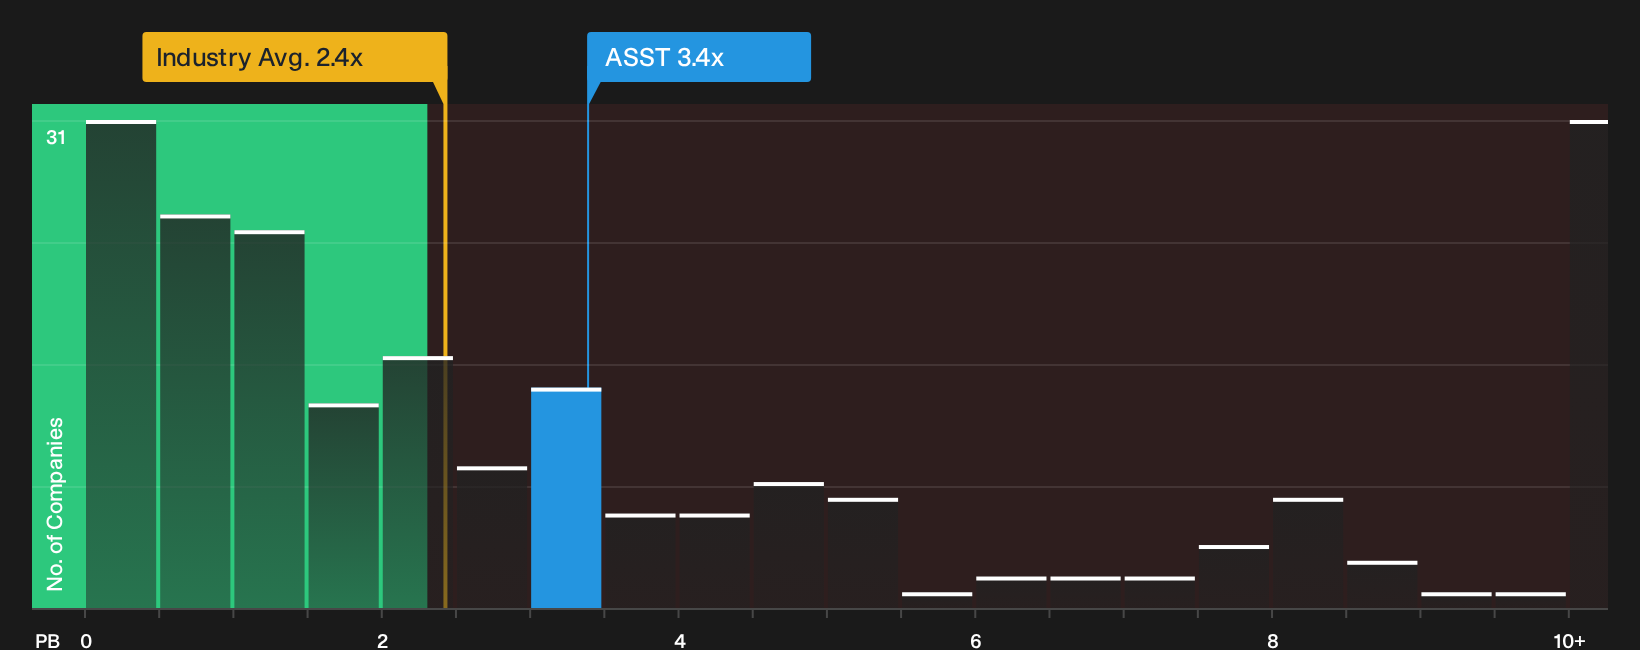
P/B is the cleanest lens here because Strive is capital intensive and investors are already focused on how its balance sheet supports the common equity. On that score, Strive trades at about 3.4x P/B, compared with an industry average of roughly 2.4x for Medical Equipment peers.
The stock also sits below a peer group average of about 6.4x, so the key message is not that Strive screens cheap on this metric but that the shares look expensive relative to the broader industry benchmark. Because the recent 15.00% Series A SATS preferred issuance concentrates attention on the remaining equity cushion, a P/B level above the sector norm suggests investors are paying a premium for the current asset base and business model rather than getting in at a discount to book. Explore the numbers behind Strive's P/B valuation.
The Strive Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Strive's P/B puzzle leaves off by spelling out which expectations on growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's price on the Community page. Each one treats Strive's fair value as a thesis about how the business might play out over time so you can see how that view holds up against future results.
A written, number-driven narrative on Strive at this point can define what would need to happen for the SATS preferred financing, the bitcoin allocation, and the common equity to sit comfortably together over the next few years. Putting those assumptions in black and white provides a clear yardstick to test against each new capital decision and operating update as they arrive.
Share your own Narrative for Strive and set out the assumptions behind your valuation.
One more piece of the Strive puzzle to check
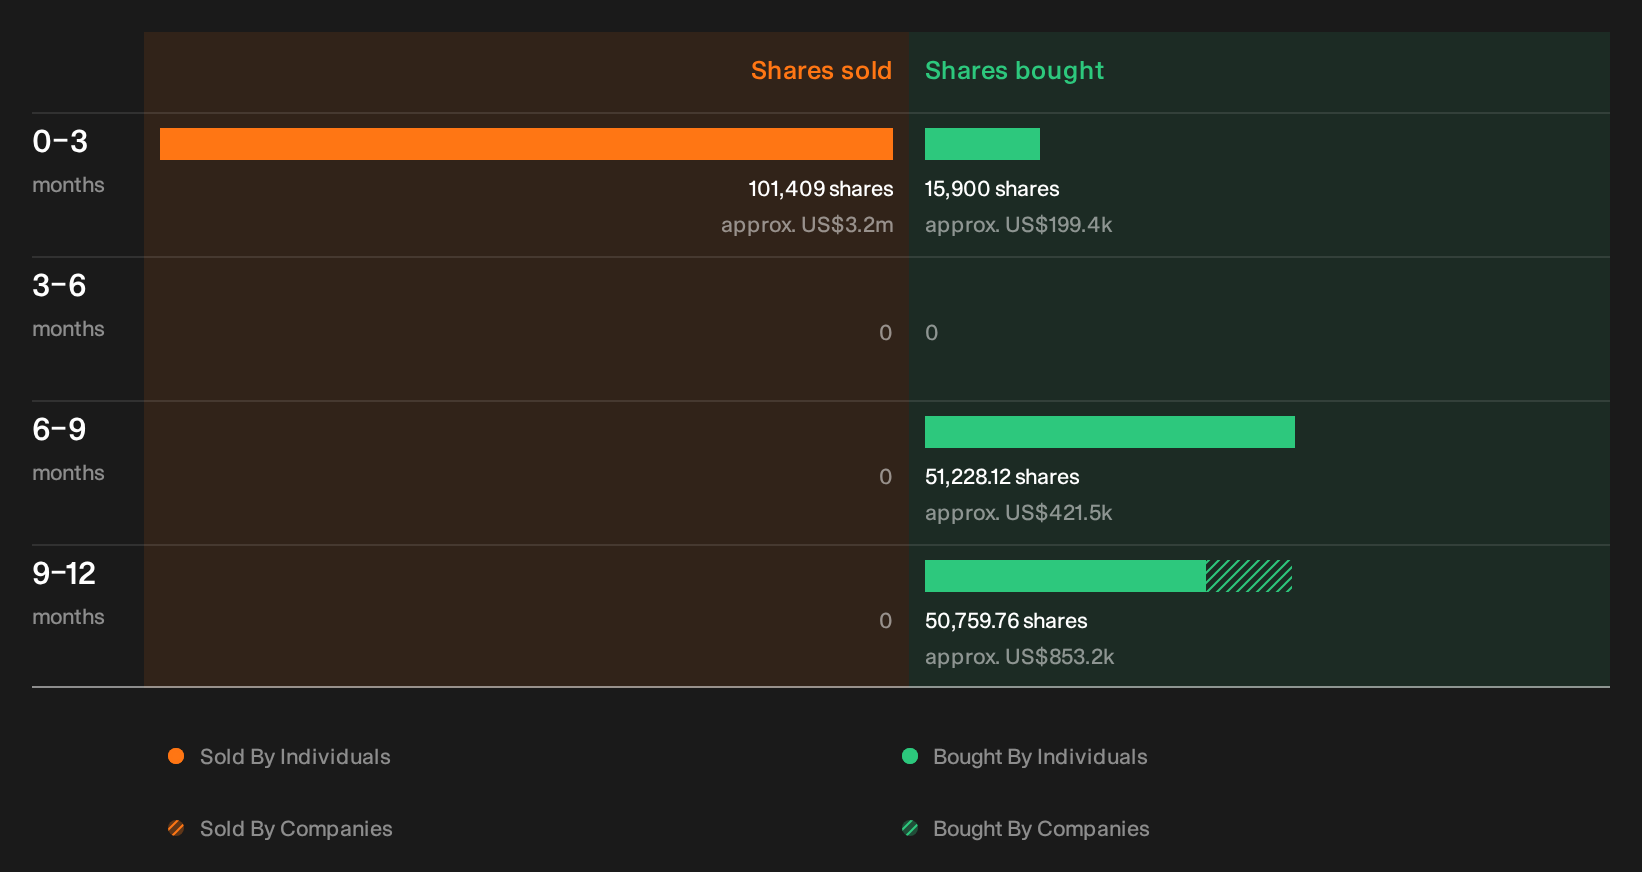
Before you put too much weight on Strive’s current valuation, it is worth knowing that recent trades by people inside the business have been flagged by our checks, and the pattern is sitting there for you to inspect. See the recent insider selling flagged for Strive.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com