
Will Dividend Reinvestment Shares Change CMS Energy's (CMS) Narrative
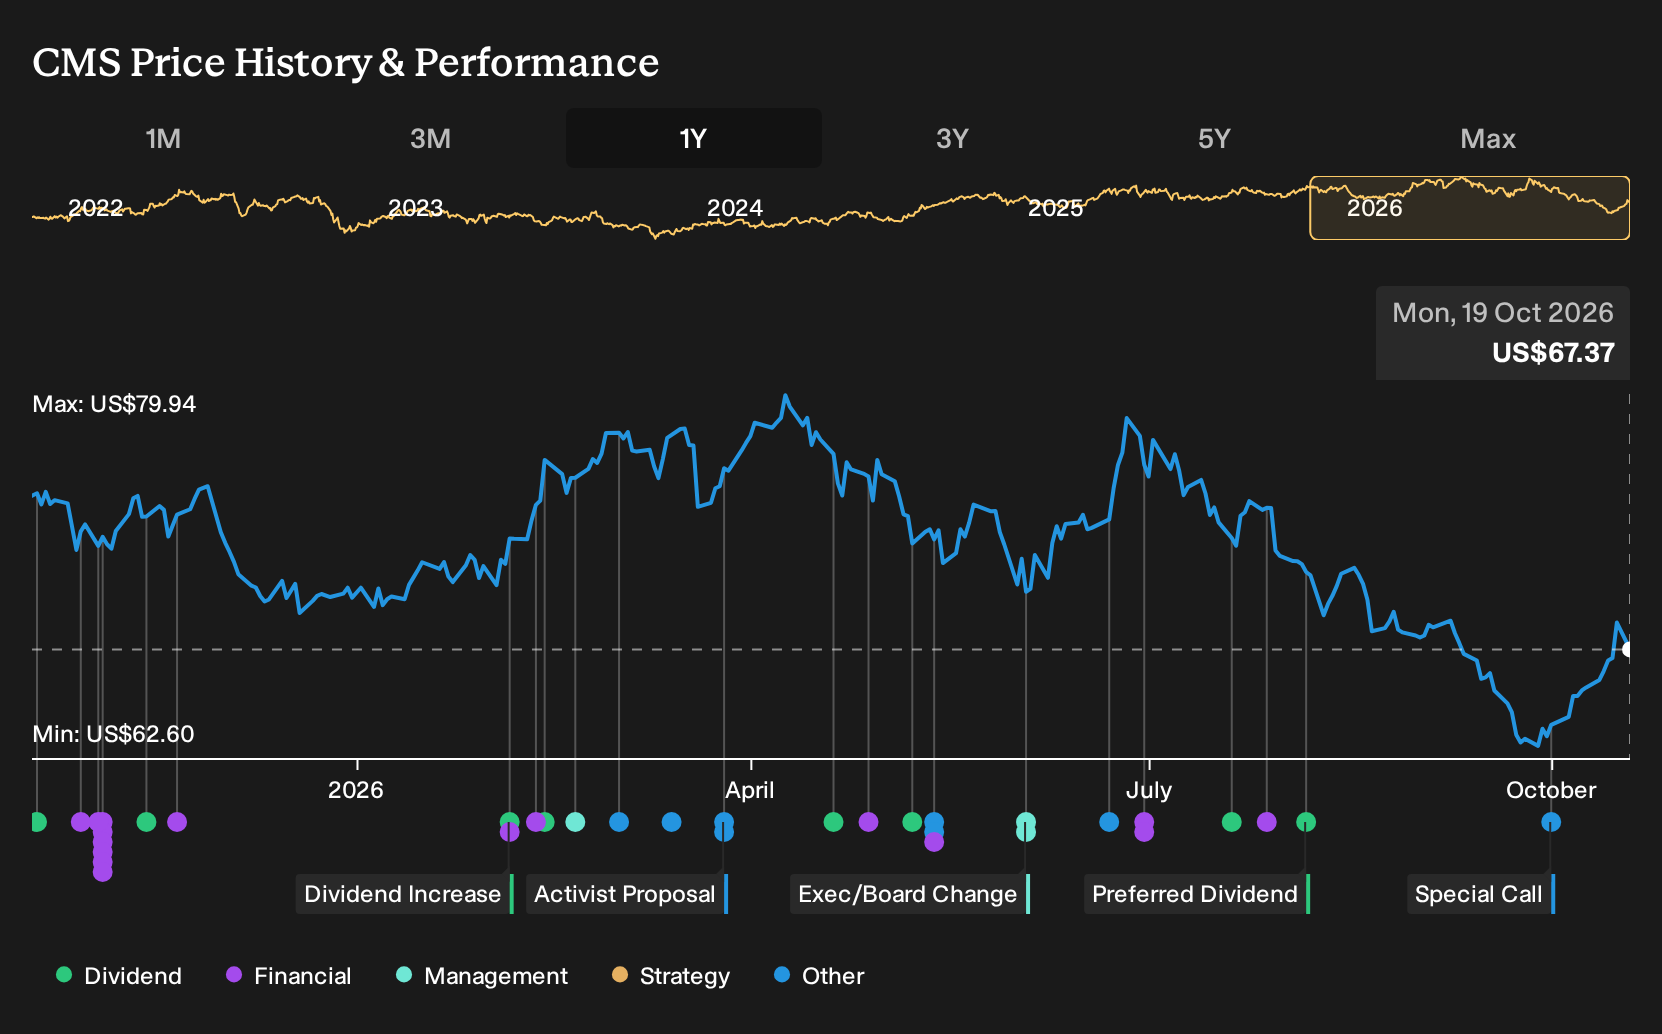
- CMS Energy filed a shelf registration for up to 2,000,000 common shares, worth about $131.72 million, to support its dividend reinvestment plan.
- The refreshed dividend reinvestment capacity gives CMS Energy another tool to source equity capital gradually. This can influence its share count, financing mix, and how investors view future funding needs.
- This development also affects how investors may assess CMS Energy's overall investment narrative in light of the renewed equity capacity under its dividend reinvestment plan.
Scan other regulated utilities taking similar equity raising routes and compare how their plans stack up against CMS Energy by reviewing the curated 42 power grid technology and infrastructure stocks.
CMS Energy Investment Narrative Recap
To own CMS Energy, you need to be comfortable with a utility that leans heavily on a roughly US$24b capital plan in Michigan and a long energy transition roadmap. The short term story still revolves around execution on grid, clean power and gas projects while keeping customer bills manageable and regulators aligned.
The fresh US$131.72m shelf for the dividend reinvestment plan looks incremental rather than a major swing factor. The bigger near term catalyst remains constructive rate outcomes that support this spending. The main risk is that large capital needs and storm related costs force more funding than planned, which could pressure earnings and interest coverage.
Among recent developments, the decision to exit nonutility renewable development and shift about US$1.7b of planned capital back into Michigan rate base projects ties closely to this new equity capacity. Both point to a simpler, more regulated earnings mix for CMS Energy, anchored in its electric and gas utilities.
That pivot sits alongside a plan to reduce parent funding needs by over US$500m through 2030 and trim common equity issuance by at least US$350m versus the prior five year plan. The refreshed dividend reinvestment shelf fits into that funding puzzle and matters most for how investors think about share count pressure, financing flexibility and execution on the long term capital program.
CMS Energy's narrative projects US$10.2b revenue and US$1.5b earnings by 2029. This assumes 4.9% yearly revenue growth and an earnings increase of about US$0.5b from US$1.0b today.
Uncover why CMS Energy's fair value indicates a 14% potential upside to its current price that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Fair value estimates on CMS Energy from the three Simply Wall St Community perspectives stretch from about US$56.18 to roughly US$76.92 per share. Retail opinions already span a wide band before factoring in the fresh US$131.72m shelf. When you also consider funding risk, weather costs and Michigan regulatory outcomes, it becomes clear why you should compare multiple viewpoints.
Explore 2 other CMS Energy fair value estimates, including one that suggests as much as 14% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your CMS Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CMS Energy. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate CMS Energy's overall financial health at a glance.
Looking for more CMS Energy sized investment ideas?
Once you have a view on CMS Energy, it often helps to broaden your watchlist and compare it with other businesses that fit different risk and income profiles. The Simply Wall St Screener can help you quickly surface stocks that match what you want your portfolio to do next.
- If you want income to play a bigger role in your returns, consider strengthening your watchlist with 8 dividend fortresses that may help support a more reliable payout stream.
- If capital preservation and steadier fundamentals matter more to you right now, focus on companies from our 32 resilient stocks with low risk scores that aim to keep balance sheets and earnings quality front and center.
- If you are hunting for new ideas beyond well known utilities like CMS Energy, broaden your research with a curated 20 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com