
COMPASS Pathways (CMPS) Reports Positive Phase 3 Data, Is The Premium Still Justified?
COMPASS Pathways (CMPS) has moved back into focus after reporting positive Phase 3 trial data for its lead psilocybin therapy, COMP360. This milestone has sharpened attention on the stock’s premium valuation.
Over the past month, COMPASS Pathways has given back some of its earlier gains, with a 30 day share price return down 26.86%, even though the year to date share price return sits at 69.62% and the 3 year total shareholder return is up 100.54%. This suggests that recent excitement around the Phase 3 readout is colliding with profit taking and shifting views on how much risk is priced into the current US$11.11 valuation.
Spot similar high-expectation stories to COMPASS Pathways by running through the hand picked 20 high quality undiscovered gems, which couples strong fundamentals with under the radar profiles.The recent pullback forces a simple tension: Are traders cooling on COMPASS Pathways, or is the business now being priced in a way that better reflects its current fundamentals and risk profile?
Most Popular Narrative: 55% Undervalued
Against the last close of $11.11, the most followed narrative on COMPASS Pathways points to a fair value of $24.47. This frames the recent pullback as a valuation reset rather than the end of the story.
Completion of enrollment in the COMP006 Phase III trial and the plan to use 9 week data from Part A together with 26 week COMP005 data to support a rolling NDA process could shorten the path to potential approval, which would bring revenue forward and may support earlier earnings visibility.
See why 13 investors see COMPASS Pathways as 55% undervalued.
Result: Fair Value of $24.47 (UNDERVALUED)
Still, the whole COMPASS Pathways story hinges on clean Phase 3 outcomes and efficient cash use, so any trial setback or funding need could quickly challenge this optimism.
Find out about the key risks to this COMPASS Pathways narrative.
Another View: COMPASS Pathways Looks Expensive On Book Value
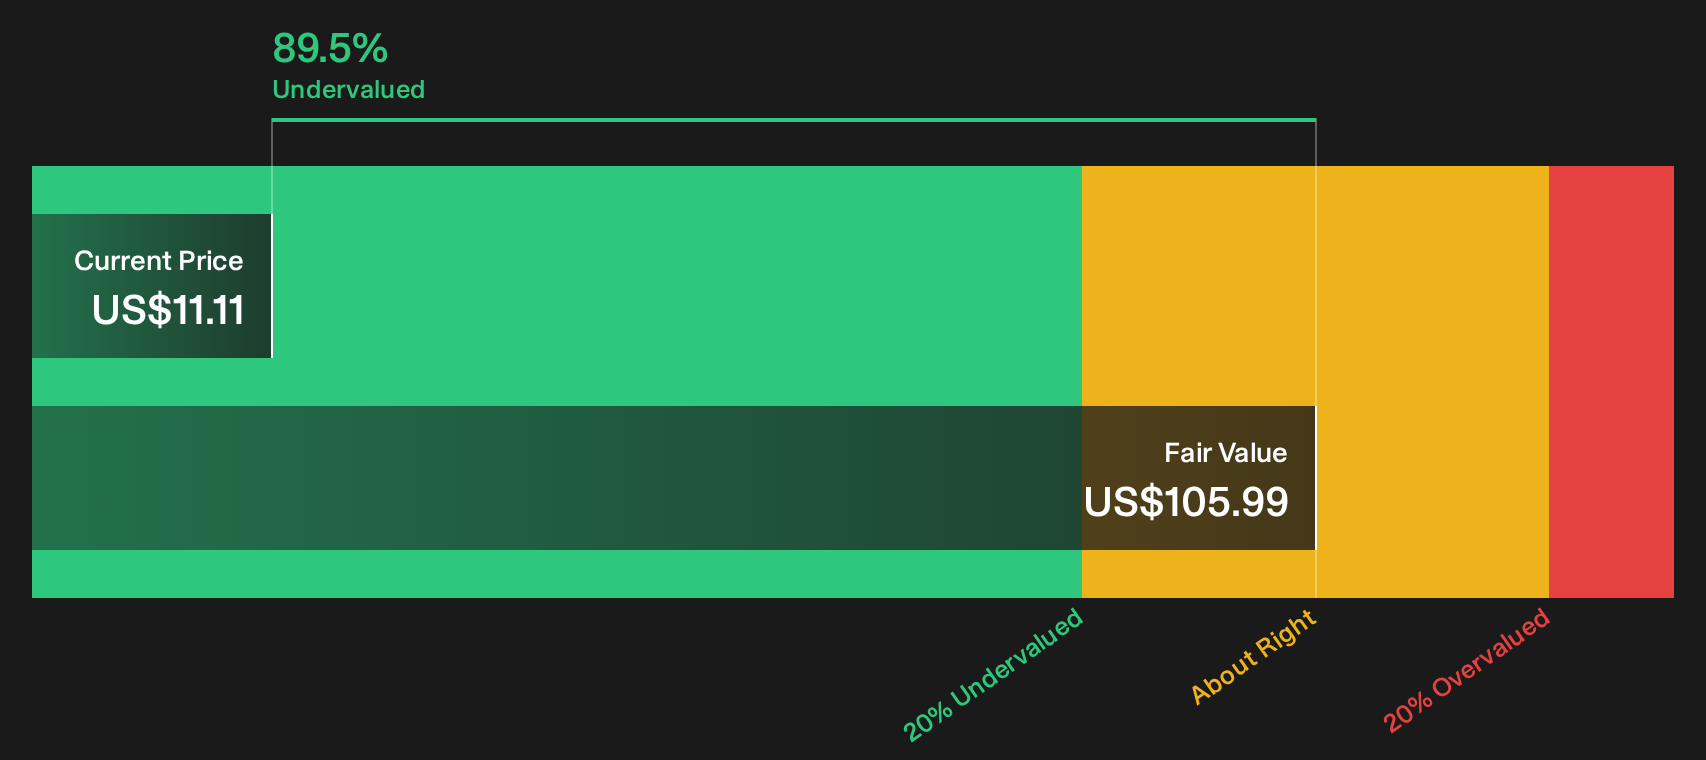
The DCF work around COMPASS Pathways paints a generous picture, with the share price at $11.11 compared with an estimate of future cash flow value at $105.99. On that framework, the stock screens as heavily undervalued. The gap is wide enough to make any investor pause.
Price to book tells a very different story. CMPS trades at a P/B of 18.2x versus 1.8x for the wider US biotech group and 3.3x for peers, which implies a rich premium to current equity on the balance sheet. The question is whether that kind of markup fairly reflects the clinical and regulatory risk still ahead.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Optimistic or cautious after weighing COMPASS Pathways so far, the real edge comes from checking the underlying data yourself and moving before sentiment shifts. To see both sides of the story in one place, walk through the 2 key rewards and 3 important warning signs.
Looking for more COMPASS Pathways style ideas?
If COMPASS Pathways has your attention, do not stop with a single ticker. Broaden your watchlist now so you are not late to the next opportunity.
- Target resilience first by scanning for businesses with sturdy finances and clean balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality by reviewing the 35 high quality undervalued stocks that blend stronger fundamentals with appealing entry prices.
- Prioritise staying power and stability by checking companies highlighted in the 32 resilient stocks with low risk scores for smoother rides through market swings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com