
Why Escorts Kubota Fell Even As Profit Rose
Investors who held Escorts Kubota over the past year are down 25.5%, including dividends. If that decision sat on your desk a year ago, it likely leaned on confident projections about export-led growth, Kubota synergies, and steady double-digit revenue gains. Since then, Q1 2027 results showed higher sales and profit but a weaker net margin. So which part of the original case proved too optimistic, the uplift in volumes and pricing power or the assumed resilience of profitability?
If the move has made Escorts Kubota harder to judge, start where the gap is still open and scan 200 high quality undervalued stocks.
The Two Escorts Kubota Stories Investors Were Weighing
The shares cost ₹3,697 at the start of the period, and Escorts Kubota sat between two very different but plausible stories about its future.
On the bullish side, the narrative pointed to a Fair Value of ₹3,998, the rough price implied by those growth assumptions, built on rising global food demand, Kubota integration, and agricultural mechanization lifting volumes and margins.
The cautious story argued for a Fair Value of ₹2,668, reflecting worries about India-heavy exposure, rural depopulation, and slower adoption of electrification and advanced digital farm equipment.
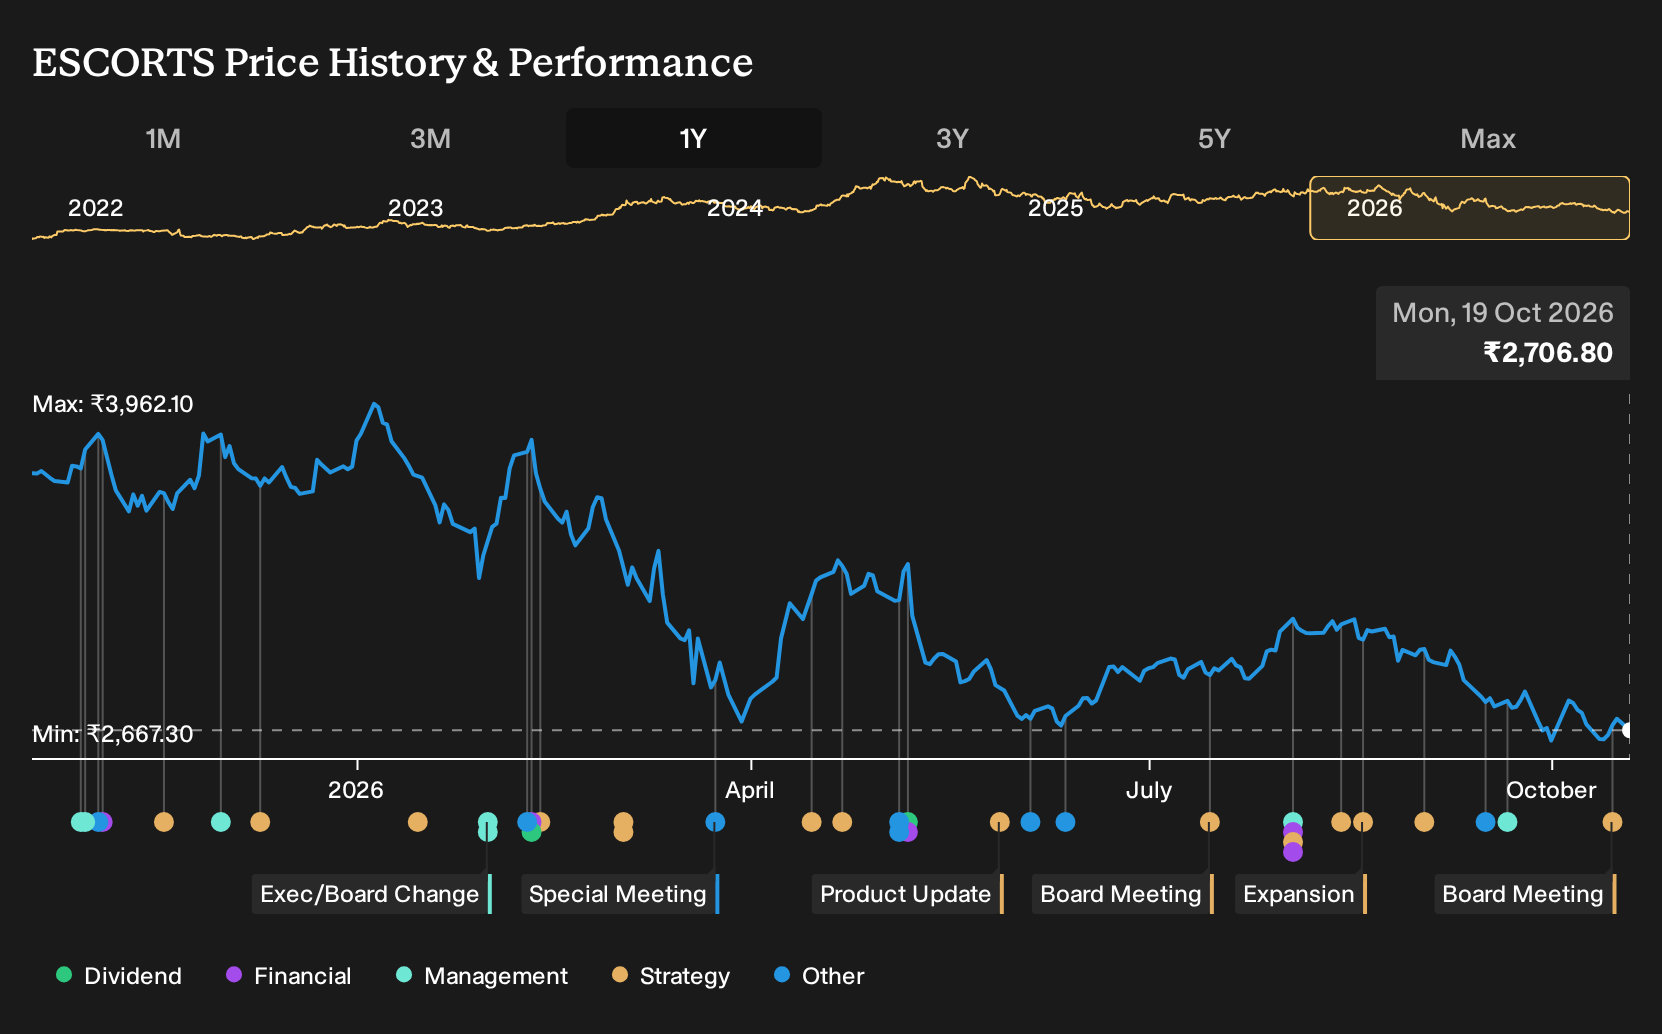
What The Escorts Kubota Results Actually Tested
The most concrete evidence during the period came from Q1 2027, where Escorts Kubota reported revenue of ₹32,075.5m and net income of ₹3,859.4m versus ₹25,000.5m and ₹3,694.8m a year earlier. That supported the optimistic story on volumes and scale. The drop in net margin from 14.8% to 12.0% challenged the thesis of stronger profitability. The evidence cut both ways.
The key lesson is simple. When a growth story leans on higher margins, do not stop at revenue or profit. Track whether net margin actually moves toward the narrative in each set of results.
What Escorts Kubota’s Lower Price Asks You To Believe
With Escorts Kubota now at ₹2,707, the selected Narrative’s Fair Value sits above the current price and leans on a broader export and product refresh story rather than just tractors.
The core assumption a buyer must test is that exports, non tractor revenue and financing penetration together support margins even when individual product lines face pressure.
"The main factor that has to go right is that Escorts Kubota continues to widen its non-tractor and construction equipment mix while managing cost inflation so that margins stay supported even when individual segments face pressure."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Go Straight To The Source
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 32% below our estimate - uses a multichannel electronics footprint to push higher-margin digital and appliances growth.
- Company 2 - 24% below our estimate - expands the maintenance sales force to secure more contracts and denser territories.
- Company 3 - 29% below our estimate - grows beyond pediatric probiotics by pushing adult products into retail pharmacy chains.
That is three of the list. See all 202 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com