
Exploring Binjiang Service Group And 2 Other Promising Small Caps In Asia
As global markets grapple with AI spending concerns and inflation pressures, the spotlight has shifted towards more value-oriented and defensive segments, creating a potential opportunity for small-cap stocks in Asia. In this dynamic environment, identifying promising small-cap companies like Binjiang Service Group can offer investors exposure to growth opportunities that align with current market conditions.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Kyosan Electric Manufacturing | 46.17% | 7.20% | 17.51% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Silvery Dragon Group Tianjin | 25.01% | 2.55% | 25.62% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 64.63% | 9.93% | 28.27% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
We're going to check out a few of the best picks from our screener tool.
Binjiang Service Group (SEHK:3316)
Simply Wall St Value Rating: ★★★★★☆
Overview: Binjiang Service Group Co. Ltd. offers property management and related services in the People’s Republic of China with a market capitalization of HK$5.78 billion.
Operations: Binjiang Service Group generates revenue primarily from property management services (CN¥2.68 billion) and value-added services (CN¥1.19 billion). The company also earns from value-added services to non-property owners, contributing CN¥500.97 million to its total revenue.
Binjiang Service Group, a small player in the Asian market, has shown promising financial performance. With earnings growth of 5.9% over the past year, it outpaced the Commercial Services industry which saw an 11.4% decrease. The company is trading at a value 35% below its estimated fair value and maintains a debt-to-equity ratio that increased slightly to 0.2% over five years, indicating prudent financial management with more cash than total debt. Recent reports show sales reaching CNY 2.3 billion and net income at CNY 315 million for the first half of 2026, alongside an interim dividend announcement of HKD 0.92 per share.
- Delve into the full analysis health report here for a deeper understanding of Binjiang Service Group.
Explore historical data to track Binjiang Service Group's performance over time in our Past section.

Chengtun Mining Group (SHSE:600711)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Chengtun Mining Group Co., Ltd. operates in the non-ferrous metal mining sector both in China and internationally, with a market capitalization of approximately CN¥28.86 billion.
Operations: Chengtun Mining Group generates revenue primarily from its non-ferrous metal mining operations. The company has a market capitalization of approximately CN¥28.86 billion.
Chengtun Mining Group, a noteworthy player in the Asian mining sector, reported impressive financial results for H1 2026 with revenue reaching CNY 19.26 billion compared to CNY 13.80 billion a year prior. Net income rose to CNY 1.80 billion from CNY 1.05 billion, showcasing robust growth and high-quality earnings as evidenced by a significant increase in basic earnings per share from CNY 0.341 to CNY 0.595. Despite trading at an attractive value of approximately 78% below its estimated fair value, the company's debt-to-equity ratio has surged from 34% to nearly double over five years, indicating potential leverage concerns despite strong EBIT coverage on interest payments at over ten times.
- Unlock comprehensive insights into our analysis of Chengtun Mining Group stock in this health report.
Assess Chengtun Mining Group's past performance with our detailed historical performance reports.
Zhuzhou Smelter GroupLtd (SHSE:600961)
Simply Wall St Value Rating: ★★★★★★
Overview: Zhuzhou Smelter Group Co., Ltd. operates in the production and sale of zinc and its alloy products under the Torch brand in China, with a market capitalization of approximately CN¥21.45 billion.
Operations: The company generates revenue primarily from lead and zinc products, amounting to approximately CN¥25.99 billion. Its market capitalization stands at around CN¥21.45 billion.
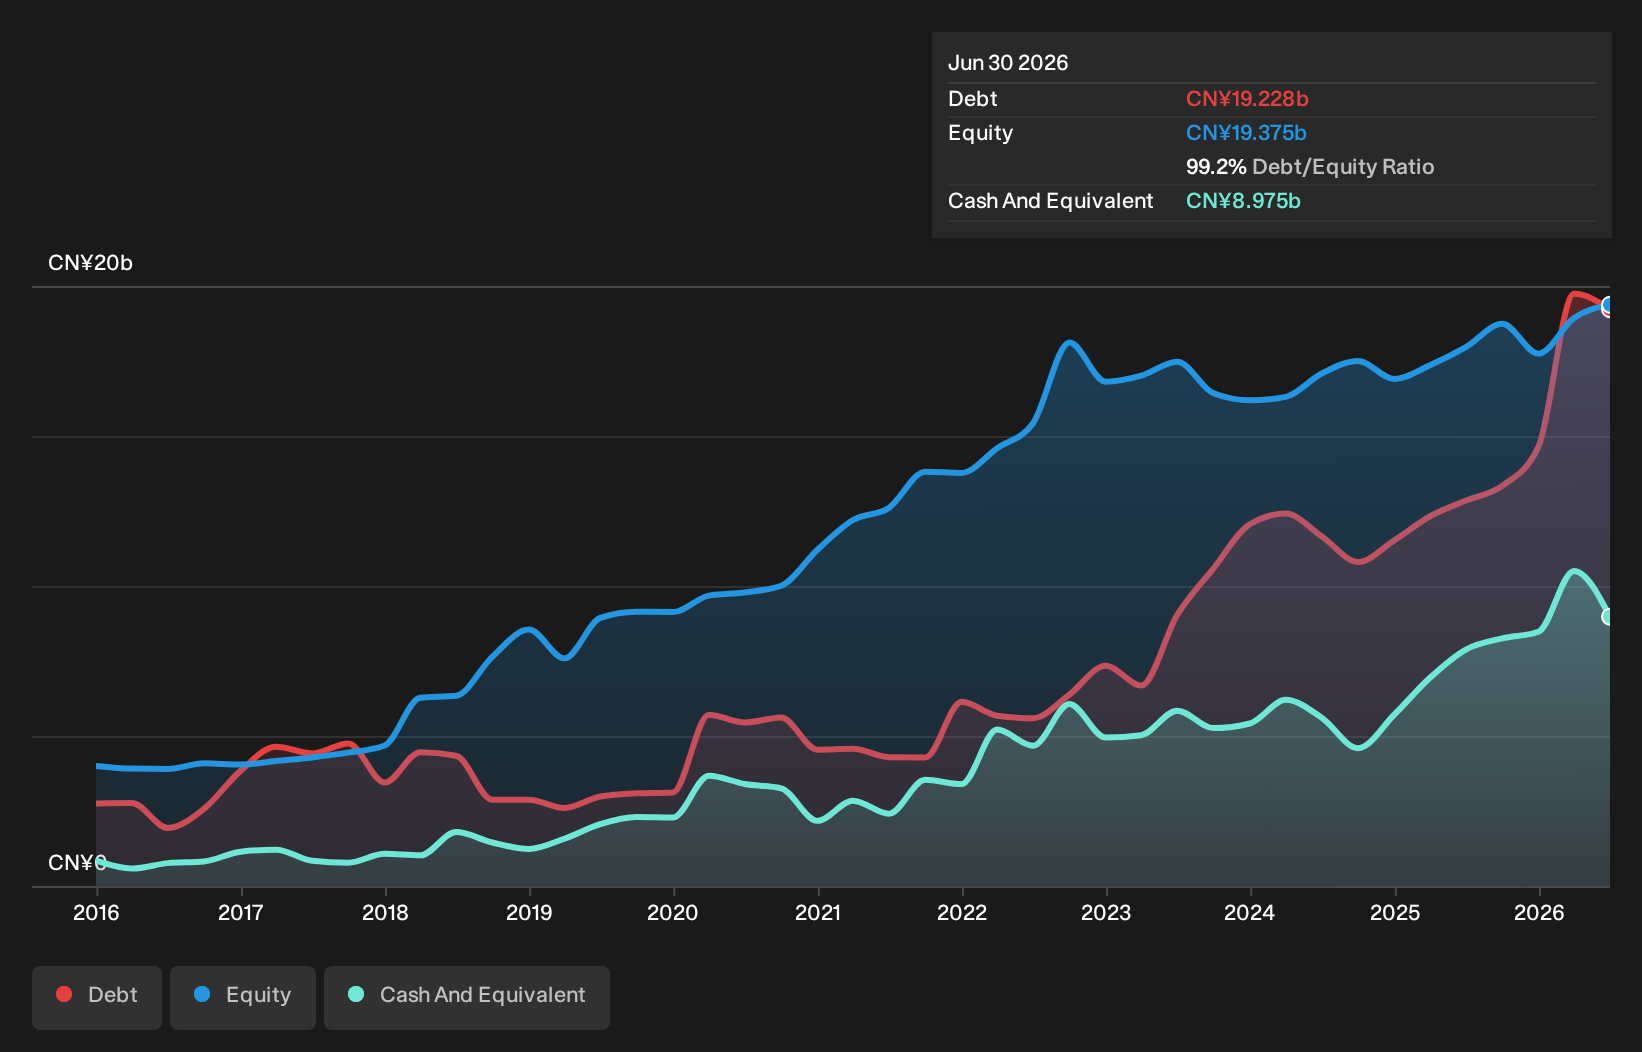
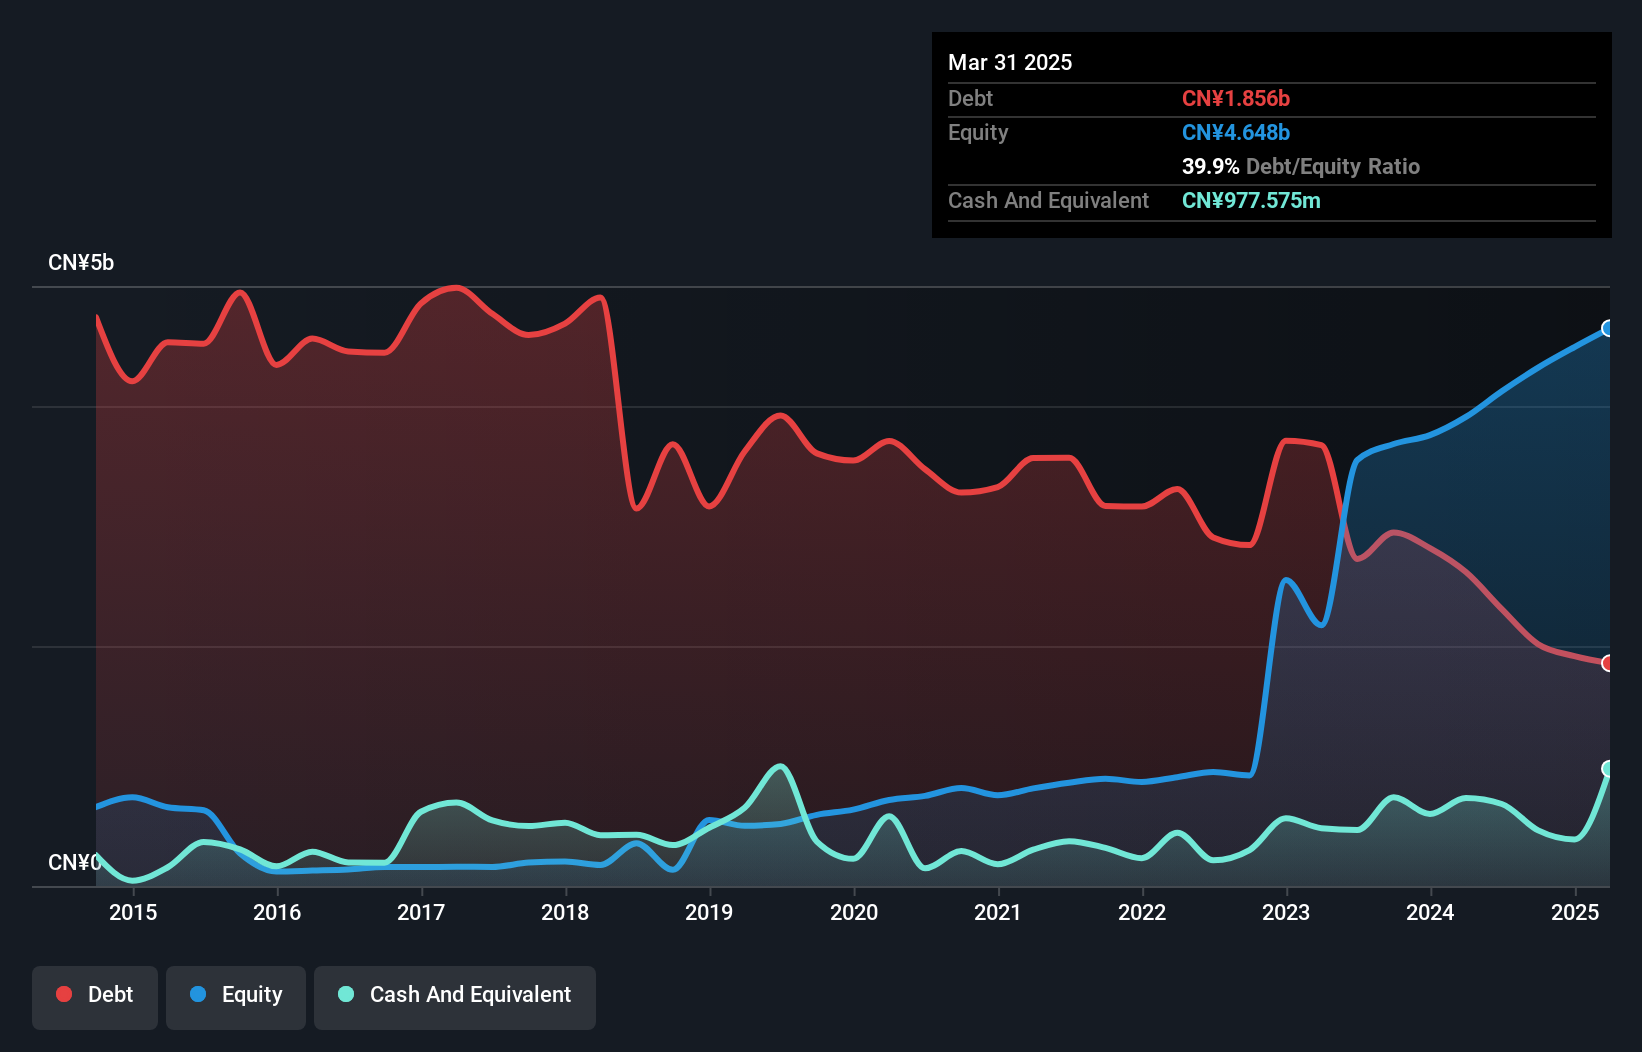
Zhuzhou Smelter Group, a notable player in the metals and mining sector, has showcased impressive financial health over recent years. Its debt to equity ratio dramatically decreased from 414.6% to 10.4%, indicating stronger financial stability. The company reported net income of CNY 1.95 billion for H1 2026, a significant rise from CNY 585 million the previous year, reflecting robust earnings growth of 148.5%. Trading at an attractive valuation—82% below estimated fair value—Zhuzhou seems well-positioned compared to peers, with its earnings growth surpassing industry averages by a wide margin of 23%.
- Click to explore a detailed breakdown of our findings in Zhuzhou Smelter GroupLtd's health report.
Gain insights into Zhuzhou Smelter GroupLtd's past trends and performance with our Past report.
Summing It All Up
- Dive into all 127 of the Asian Undiscovered Gems With Strong Fundamentals we have identified here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Unlock the power of informed investing with Simply Wall St, your free guide to navigating stock markets worldwide.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com