
Asian Market Picks: 3 Stocks That May Be Undervalued In October 2026
As of October 2026, the Asian markets are navigating a complex environment marked by global inflation pressures and shifting investor sentiment away from technology and AI-related stocks. Amidst these challenges, investors are increasingly turning their attention to value-oriented opportunities that may be overlooked. In this context, identifying potentially undervalued stocks requires a keen eye for companies with strong fundamentals and resilience in uncertain times.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| P.S.P. Specialties (SET:PSP) | THB7.40 | THB14.57 | 49.2% |
| PAL GROUP Holdings (TSE:2726) | ¥1459.00 | ¥2911.72 | 49.9% |
| Nissui (TSE:1332) | ¥1109.50 | ¥2165.31 | 48.8% |
| Kumagai GumiLtd (TSE:1861) | ¥1217.00 | ¥2410.08 | 49.5% |
| Kona ILtd (KOSDAQ:A052400) | ₩34800.00 | ₩69484.98 | 49.9% |
| Jason Furniture (Hangzhou)Ltd (SHSE:603816) | CN¥24.30 | CN¥48.39 | 49.8% |
| ENN Energy Holdings (SEHK:2688) | HK$50.15 | HK$97.21 | 48.4% |
| China Resources Sanjiu Medical & Pharmaceutical (SZSE:000999) | CN¥26.26 | CN¥52.47 | 50% |
| China Coal Energy (SEHK:1898) | HK$10.37 | HK$20.18 | 48.6% |
| Apex Mining (PSE:APX) | ₱16.94 | ₱33.35 | 49.2% |
Let's take a closer look at a couple of our picks from the screened companies.
Thai Vegetable Oil (SET:TVO)
Overview: Thai Vegetable Oil Public Company Limited, with a market cap of THB25.35 billion, operates through its subsidiary to manufacture and distribute soy meal and soybean oil both in Thailand and internationally.
Operations: The company generates revenue primarily from the manufacture and distribution of products from soybean, amounting to THB29.81 billion, and also engages in the manufacture and distribution of packaging products, contributing THB649 million.
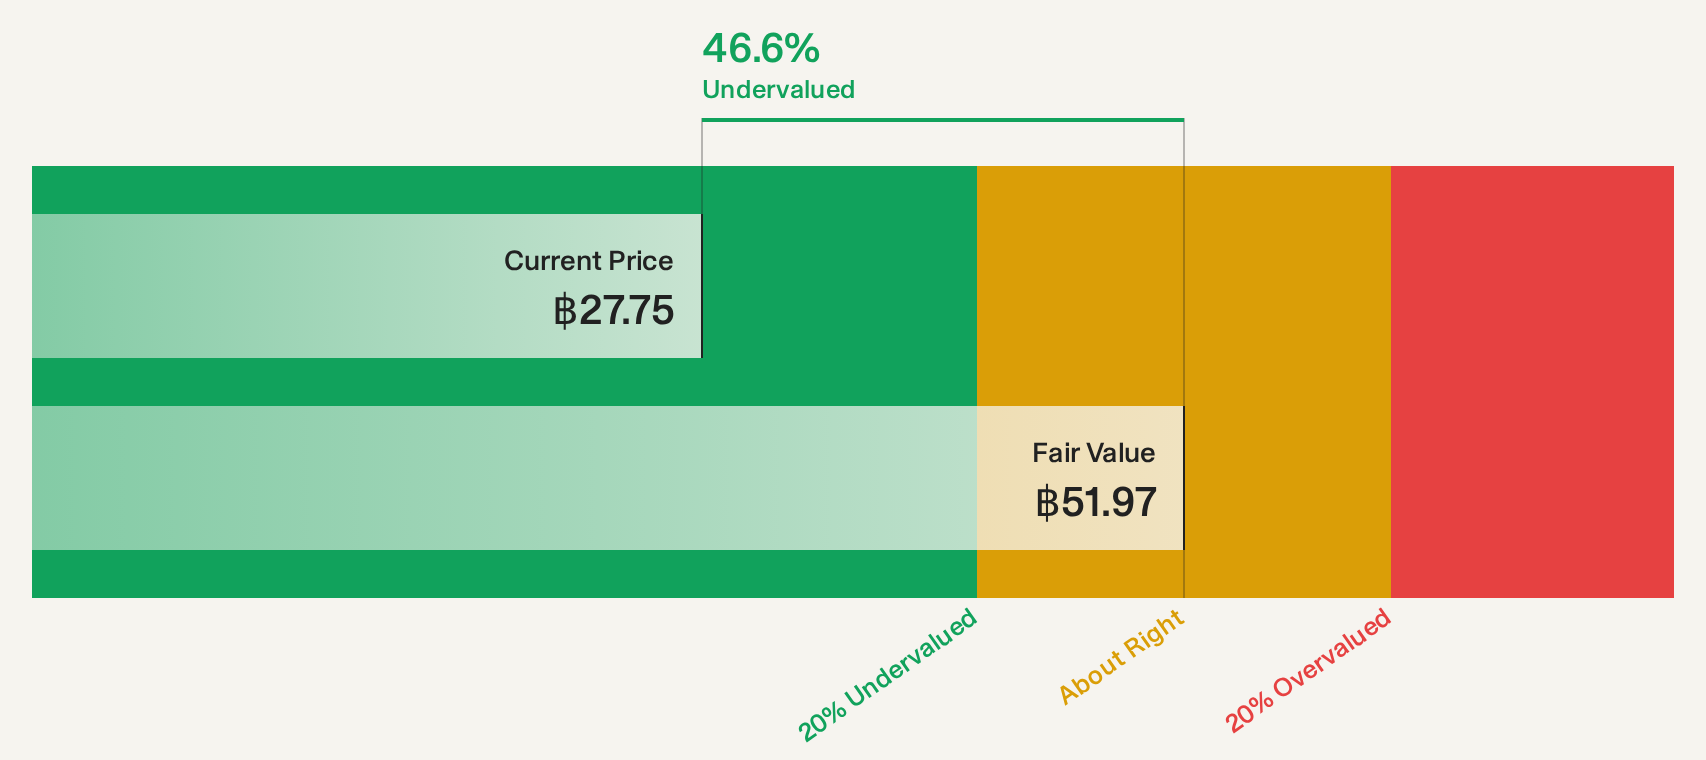
Estimated Discount To Fair Value: 44.7%
Thai Vegetable Oil, trading at THB28.75, is significantly undervalued based on discounted cash flow analysis with an estimated fair value of THB51.97. Despite slower forecasted earnings and revenue growth compared to the Thai market, recent financial results show robust performance with net income rising to THB877.11 million in Q2 2026 from THB647.62 million a year ago. However, its dividend yield of 6.85% is not well covered by free cash flows, indicating potential sustainability concerns.
- Our earnings growth report unveils the potential for significant increases in Thai Vegetable Oil's future results.
- Get an in-depth perspective on Thai Vegetable Oil's balance sheet by reading our health report here.
China Resources Jiangzhong PharmaceuticalLtd (SHSE:600750)
Overview: China Resources Jiangzhong Pharmaceutical Co., Ltd focuses on manufacturing pharmaceutical products in China and has a market cap of CN¥15.15 billion.
Operations: Revenue Segments (in millions of CN¥): The company generates revenue primarily from the manufacture of pharmaceutical products in China.
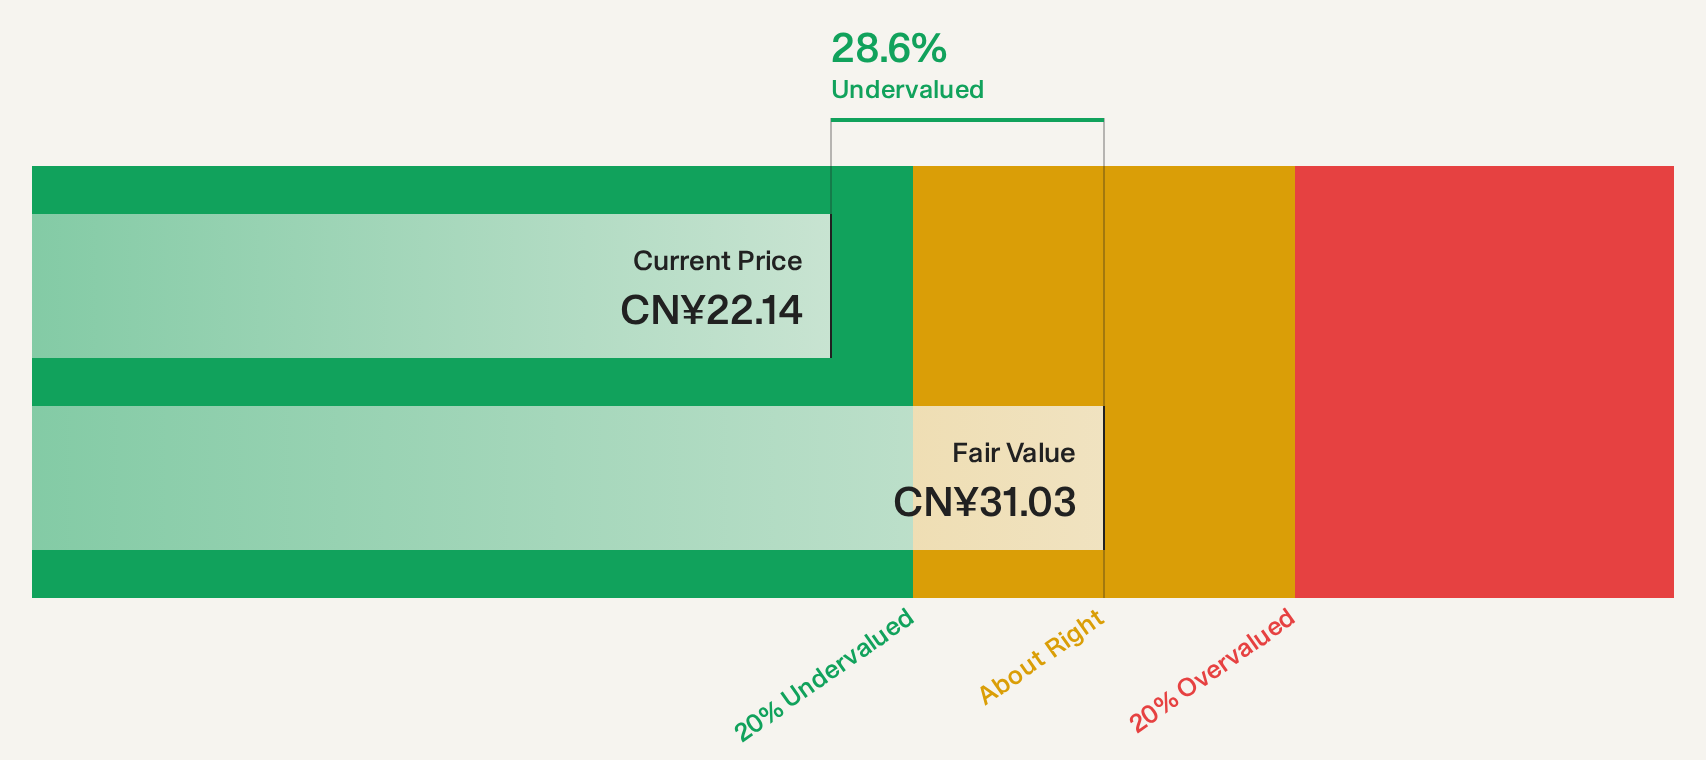
Estimated Discount To Fair Value: 22.4%
China Resources Jiangzhong Pharmaceutical, trading at CN¥24.07, is undervalued with a fair value estimate of CN¥31.03 based on discounted cash flow analysis. Despite a decline in first-half sales and net income compared to the previous year, the stock trades 22.4% below its estimated fair value and offers good relative value against peers. However, its dividend yield of 5.73% isn't well covered by earnings or free cash flows, raising sustainability concerns.
- The growth report we've compiled suggests that China Resources Jiangzhong PharmaceuticalLtd's future prospects could be on the up.
- Click here to discover the nuances of China Resources Jiangzhong PharmaceuticalLtd with our detailed financial health report.
DeHua TB New Decoration MaterialLtd (SZSE:002043)
Overview: DeHua TB New Decoration Material Co., Ltd is engaged in the production and sale of furniture boards both in China and internationally, with a market cap of CN¥10.41 billion.
Operations: The company's revenue is primarily derived from its Decorative Material Business, which accounts for CN¥8.08 billion, followed by the Custom Home Business at CN¥1.33 billion.
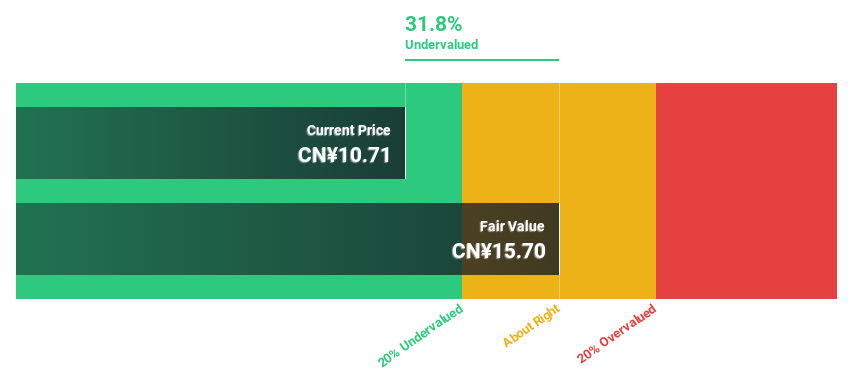
Estimated Discount To Fair Value: 38.8%
DeHua TB New Decoration Material Ltd., trading at CN¥12.64, is undervalued with a fair value estimate of CN¥20.65 based on discounted cash flow analysis, offering good relative value compared to peers. Despite revenue growth from CN¥3,634.08 million to CN¥4,266.52 million year-over-year, net income decreased slightly to CN¥247.31 million from CN¥267.85 million. The company has an unstable dividend track record and forecasts slower revenue and earnings growth than the market average in China.
- Insights from our recent growth report point to a promising forecast for DeHua TB New Decoration MaterialLtd's business outlook.
- Click to explore a detailed breakdown of our findings in DeHua TB New Decoration MaterialLtd's balance sheet health report.
Where To Now?
- Unlock our comprehensive list of 175 Undervalued Asian Stocks Based On Cash Flows by clicking here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com