
Weichai Power (SEHK:2338) Pullback Reopens The Debate Over Whether Fair Value Still Beckons
Recent commentary around Weichai Power (SEHK:2338) has zeroed in on one issue. Can the current earnings profile support a premium valuation when the shares already trade above sector averages, yet still below some implied fair value estimates?
Recent trading in Weichai Power reflects that debate. The share price has fallen 19.81% over the past 30 days and 22.50% over 90 days, yet the year-to-date share price return of 33.93% and a 3-year total shareholder return of 178.09% show long term momentum that is still firmly intact.
Compare Weichai Power's rerating with other premium industrial plays by reviewing the hand picked 200 high quality undervalued stocks that combine stronger fundamentals with valuations the market may not fully reflect yet.
After a 3 year total return above 170% and a recent pullback of more than 20%, is most of Weichai Power's rerating already in the rear view mirror, or do current earnings still leave real upside on the table?
Preferred P/E of 14.4x: Is it justified?
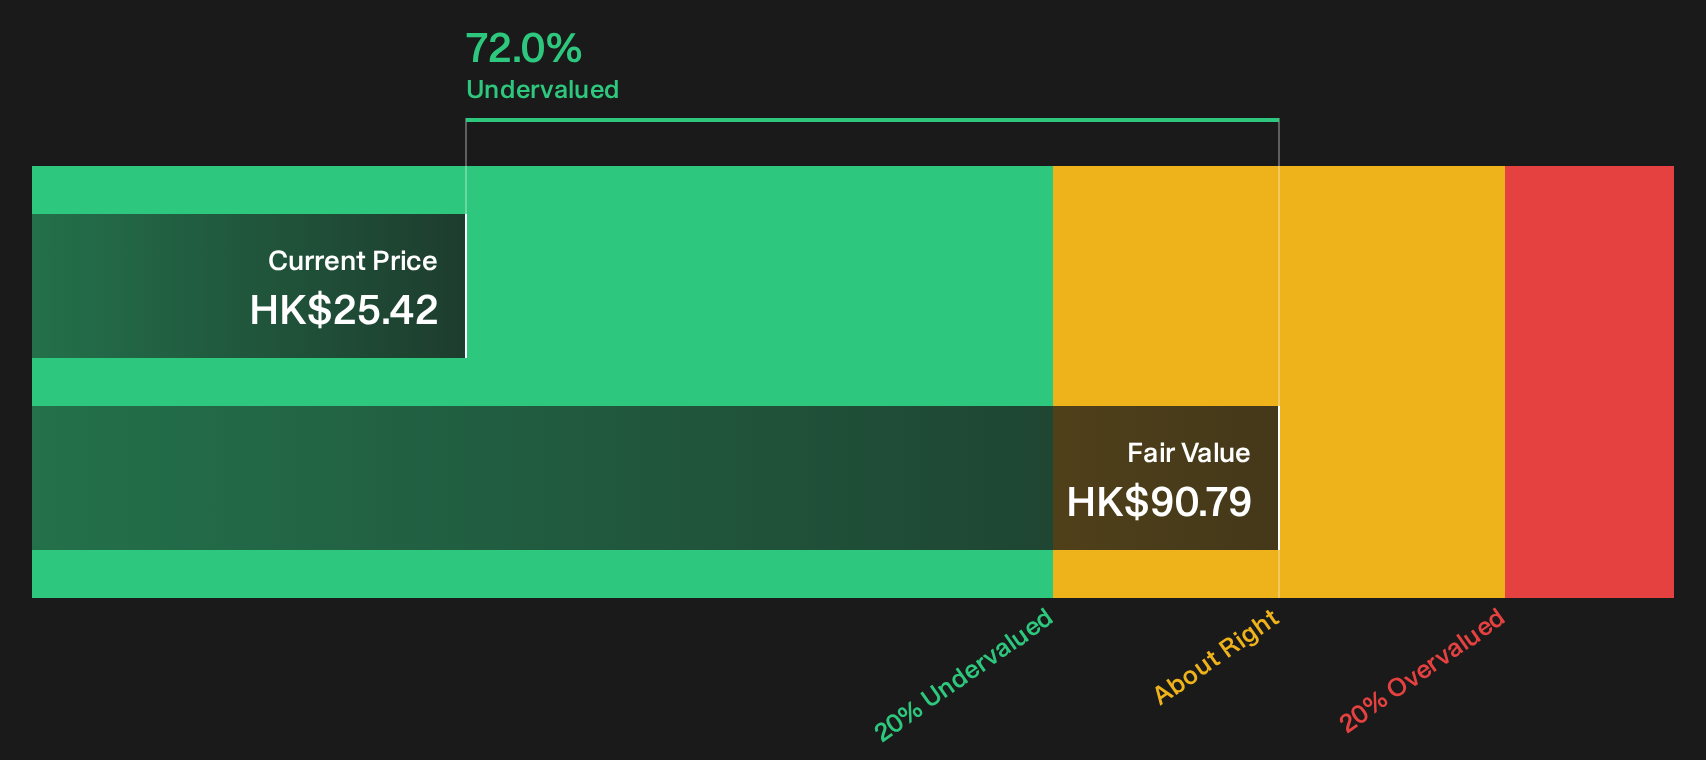
Valuation on Weichai Power today sits in a tight spot. The stock trades on a P/E of 14.4x, which is richer than both the Hong Kong Machinery industry at 11.6x and the peer average of 10.7x, yet still below an estimated fair P/E of 17.9x and well under some HK$90.79 per share future cash flow estimates from the SWS DCF model when set against the current HK$25.42 price.
The P/E ratio simply tells you how many dollars of price investors are paying for each dollar of current earnings. For a manufacturer with multiple segments and international reach like Weichai Power, that measure becomes a quick shorthand for how the market is weighing its profit engine, from engines and auto parts through to intelligent logistics and agricultural equipment.
High quality earnings, forecast profit growth of 25.12% per year and revenue that is projected to advance 11.3% per year all help explain why the market is willing to put a premium P/E on Weichai Power against other Machinery stocks. At the same time, the fair P/E estimate of 17.9x points to a level the valuation could gravitate toward if those earnings forecasts and margin trends hold up, while the SWS DCF model fair value of HK$90.79 per share highlights how sensitive intrinsic value can be to cash flow assumptions when set beside the current HK$25.42 share price.
Relative to peers, the comparison is blunt. The current 14.4x P/E is higher than the Hong Kong Machinery industry on 11.6x and above the 10.7x peer average, which signals the market is already assigning Weichai Power a more optimistic earnings profile than many competitors.
Explore the SWS fair ratio for Weichai Power.
Result: Price-to-earnings of 14.4x (OVERVALUED).
Still, Weichai Power faces risk if earnings forecasts disappoint or if its capital goods end markets soften, which could quickly weaken that premium P/E narrative.
Find out about the key risks to this Weichai Power narrative.
Another view on Weichai Power's value
The SWS DCF model paints a very different picture for Weichai Power. It places fair value at HK$90.79 per share versus the current HK$25.42 price, which points to a large gap. If that cash flow outlook proves too optimistic, how much weight should you really give this signal?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Weichai Power for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 200 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Weichai Power's valuation can feel confusing, so move quickly to review the data yourself, weigh both sides of the debate, and then study the 4 key rewards and 1 important warning sign
Looking for more ideas beyond Weichai Power?
Once you have formed a view on Weichai Power, the next smart move is broadening your watchlist with other focused opportunities that match your style.
- Target resilient payers that aim to keep income flowing by screening for 218 dividend fortresses that can anchor the income side of your portfolio.
- Hunt for overlooked quality by scanning a list of solid balance sheet and fundamentals (202 results) so you are not missing sturdier businesses hiding behind quieter headlines.
- Spot tomorrow's potential standouts early by running a 613 high quality undiscovered gems before the crowd starts paying close attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com