
The Bet Singapore Exchange Holders Made
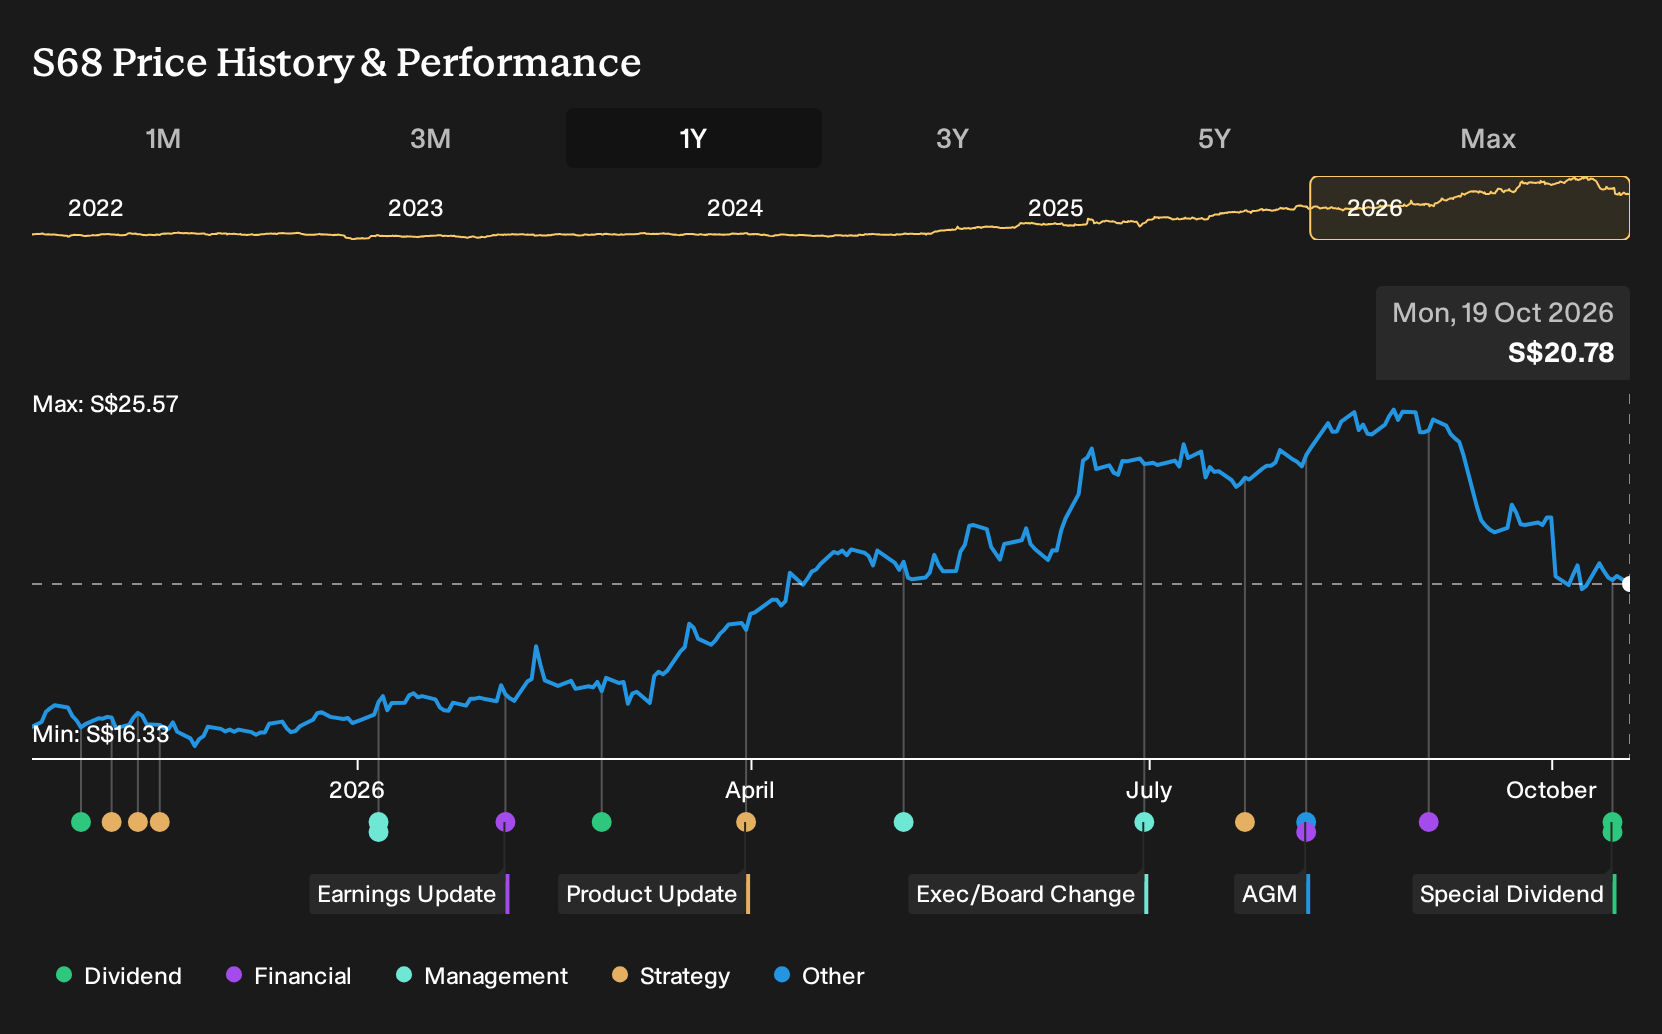
If you only glanced at Singapore Exchange headlines, the story might look straightforward. Holding Singapore Exchange over the past year would have returned 26.2%, including dividends. That gain arrived in a year when analysts were split between a bullish view tied to Asian wealth and ESG demand, and a cautious stance focused on digital disruption and listing pressure. If you had been weighing those opposing records in October 2025, what exactly were you betting on?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Singapore Exchange has already moved. See which of 200 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Choose Between On Singapore Exchange
The shares cost SGD16.75 at the start of the period, and you had to decide which version of Singapore Exchange felt more plausible.
On the optimistic side, the bull Narrative put Fair Value at SGD18.3, or 9% above the start price. It leaned on rising Asian wealth, Singapore's safe-haven role, and the idea that new ESG and crypto products could expand fee income and diversify earnings.
The bear Narrative set Fair Value at SGD10.3, or 39% below the start price. That view stressed digital finance and rival Asian exchanges eroding SGX's relevance, with heavy dependence on derivatives adding volatility and margin risk.
What The Results Changed For The Singapore Exchange Story
Singapore Exchange secured two clear proof points for the bullish version of the story. Crypto perpetual futures for US institutions and the Gprnt partnership on ESGenome both backed the idea of new product lines around digital assets and ESG. Reported H2 2026 numbers added weight, with revenue at SGD823.3m and net income at SGD355.7m, although net margin slipped to 43.2%. The evidence cut both ways.
The key assumption investors can recycle elsewhere is about breadth, not headlines. When a thesis leans on new platforms or disclosure tools, track whether those actually show up in reported revenue and profit, and whether margins hold up while the product mix shifts.
What Today's Singapore Exchange Price Already Assumes
Today Singapore Exchange trades at SGD20.78 after a 26.2% gain over the past year. The selected Narrative places its Fair Value below that level, arguing the recent run already bakes in confident expectations about execution.
This view hinges on whether SGX can keep turning record activity into earnings while expenses, technology spending and capital choices stay under control. A buyer today effectively backs that conversion, so the question is how the risks around costs, treasury income and capital recycling affect that bet.
"The main thing that has to go right is that SGX converts record revenues in multi asset derivatives, FX and revitalised cash equities into sufficient earnings growth to offset rising expenses, technology investment and capital recycling missteps. The current valuation implies SGX shares are priced for continued strong execution on multi year growth targets and dividend commitments, even though recent downgrades point to risk of earnings expectations being revised down."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Looking Beyond Singapore Exchange
Singapore Exchange sits at a junction of capital flows and trading activity. One step away, another business rides a different kind of transaction stream.
Instead of matching buyers and sellers of securities, this platform handles everyday payments. It gives shoppers and merchants a way to move money online and in person.
The model is asset light. Banking partners provide the balance sheets, while the platform keeps the payment relationships and software rails.
Where SGX leans on listings and derivatives, this neighbour leans on checkout buttons and digital wallets. The open question is whether that payment toll road widens or hits limits from regulation and funding costs.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 45% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com