
Is IDEXX Laboratories (IDXX) Undervalued On Its Zacks Rank Upgrade?
IDEXX Laboratories (IDXX) moved into focus after being upgraded to a Zacks Rank #2 rating. This change reflects a more positive view on its earnings estimates and puts fresh attention on the stock’s recent performance trends.
The recent upgrade comes as IDEXX Laboratories trades around US$555.80. The 7 day share price return is 6.1% and the 30 day share price return is 8.6%. In contrast, the year to date share price return is down 17.0% and the 1 year total shareholder return has declined 13.6%. Over a longer period, the 3 year total shareholder return of 29.9% indicates stronger momentum than over the past year.
Compare this Zacks upgrade on IDEXX Laboratories with other potential breakout candidates by scanning our curated list of 20 high quality undiscovered gems for ideas beyond a single ticker.
IDEXX Laboratories has just logged a sharp short term rebound while longer term returns look more mixed, which sets up a familiar fork in the road: lean into the current momentum or wait for a cleaner entry on valuation grounds.
Most Popular Narrative: 21% Undervalued
On the most followed view, IDEXX Laboratories screens as undervalued, with a fair value estimate of about $701 compared with the recent $555.80 close. This view puts more weight on recurring diagnostics than on the short term share price swing.
The main factor that has to go right is that IDEXX Laboratories converts underpenetrated veterinary diagnostics demand into higher bloodwork inclusion and utilization across an expanding VetLab and inVue Dx installed base, even with softer clinical visit trends.
The current numbers and guidance imply a share price that already reflects solid execution, yet still allows for potential upside if the company delivers on its long-term algorithm while the stock is viewed as undervalued in this narrative’s assessment.
See why 29 investors see IDEXX Laboratories as 21% undervalued.
Result: Fair Value of $701 (UNDERVALUED)
Still, if U.S. clinic visits stay weak or rising expenses outpace recurring diagnostics growth, the bullish IDEXX Laboratories earnings narrative could quickly lose momentum.
Find out about the key risks to this IDEXX Laboratories narrative.
Another View: IDEXX Laboratories Looks Expensive On Earnings
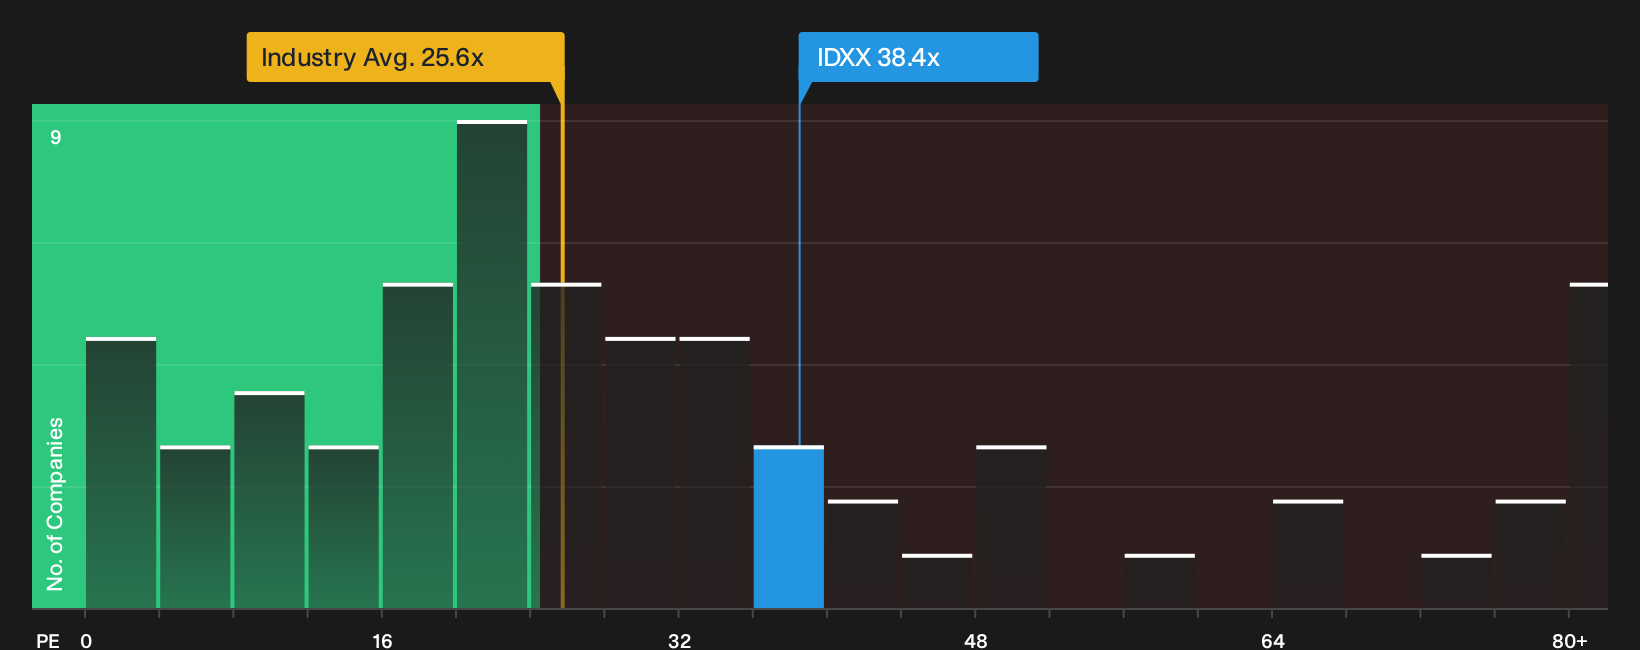
The earlier narrative framed IDEXX Laboratories as about 6% below an estimated fair value of $590.83. A simple P/E cross check tells a very different story. The stock trades at roughly 38.4x earnings, while the fair ratio sits closer to 28.9x and the US Medical Equipment group averages about 25.6x.
That means investors are already paying a steep premium to both peers and the fair ratio, which raises the bar for future execution and leaves less room for error if growth comes in closer to the 8.5% to 10.2% forecasts. The question is whether recurring diagnostics and high returns on equity justify carrying that kind of multiple risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on IDEXX Laboratories after all this, or leaning one way? Act quickly, review both sides of the story, and weigh up the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond IDEXX Laboratories?
If IDEXX Laboratories has you thinking harder about valuation and momentum, use that focus to widen your watchlist and spot opportunities before they get crowded.
- Target quality at a discount by scanning our curated pool of resilient compounders through the 35 high quality undervalued stocks.
- Lock in potential income streams by reviewing companies that feature in the 8 dividend fortresses.
- Reduce unpleasant surprises by filtering for durable businesses with strong finances using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com