
Vishay Intertechnology (VSH) Launches New Sensors, Is It Still A Bargain?
Vishay Intertechnology (VSH) has just expanded its optoelectronics lineup with four Automotive Grade optical sensors and is showcasing broader battery focused components at The Battery Show North America 2026, drawing fresh attention to the stock.
Recent trading has been choppy. Vishay Intertechnology’s share price is up 3.00% over the past day to US$28.54 but down 10.90% over the past week and 12.21% across 30 days. In comparison, the 1 year total shareholder return of 66.00% and 5 year total shareholder return of 61.09% indicate stronger momentum over longer periods that recent product news may be helping to reignite.
Scan Vishay Intertechnology’s latest battery and optical sensor catalysts against a curated field of peers by reviewing the 42 power grid technology and infrastructure stocks that is shaping next generation EV and energy storage infrastructure.
Vishay Intertechnology shares have pulled back sharply even as analysts and intrinsic value models sit much higher. Is the recent slide a reset, or a gap between price and fair value that may need to close next?
Most Popular Narrative: 29% Undervalued
Vishay Intertechnology’s most followed valuation story pegs fair value at $40.00, well above the last close at $28.54. This puts the recent pullback into sharper context for anyone tracking long term upside versus near term volatility.
With major multi year investments in capacity expansion now supported by nearly $900m already deployed, a planned 2026 capex range of $400m to $440m, and new Western facilities such as the German 12 inch fab and Newport UK fab ramping, Vishay Intertechnology is building headroom for potential future revenue growth and operating leverage as utilization improves.
See why 13 investors see Vishay Intertechnology as 29% undervalued.
Result: Fair Value of $40.00 (UNDERVALUED)
Still, Vishay Intertechnology’s heavy capex plan and reliance on its U.S. revolving credit facility mean that weaker demand or pricing could quickly challenge that 29% undervalued narrative.
Find out about the key risks to this Vishay Intertechnology narrative.
Another View: What Multiples Say About Vishay Intertechnology
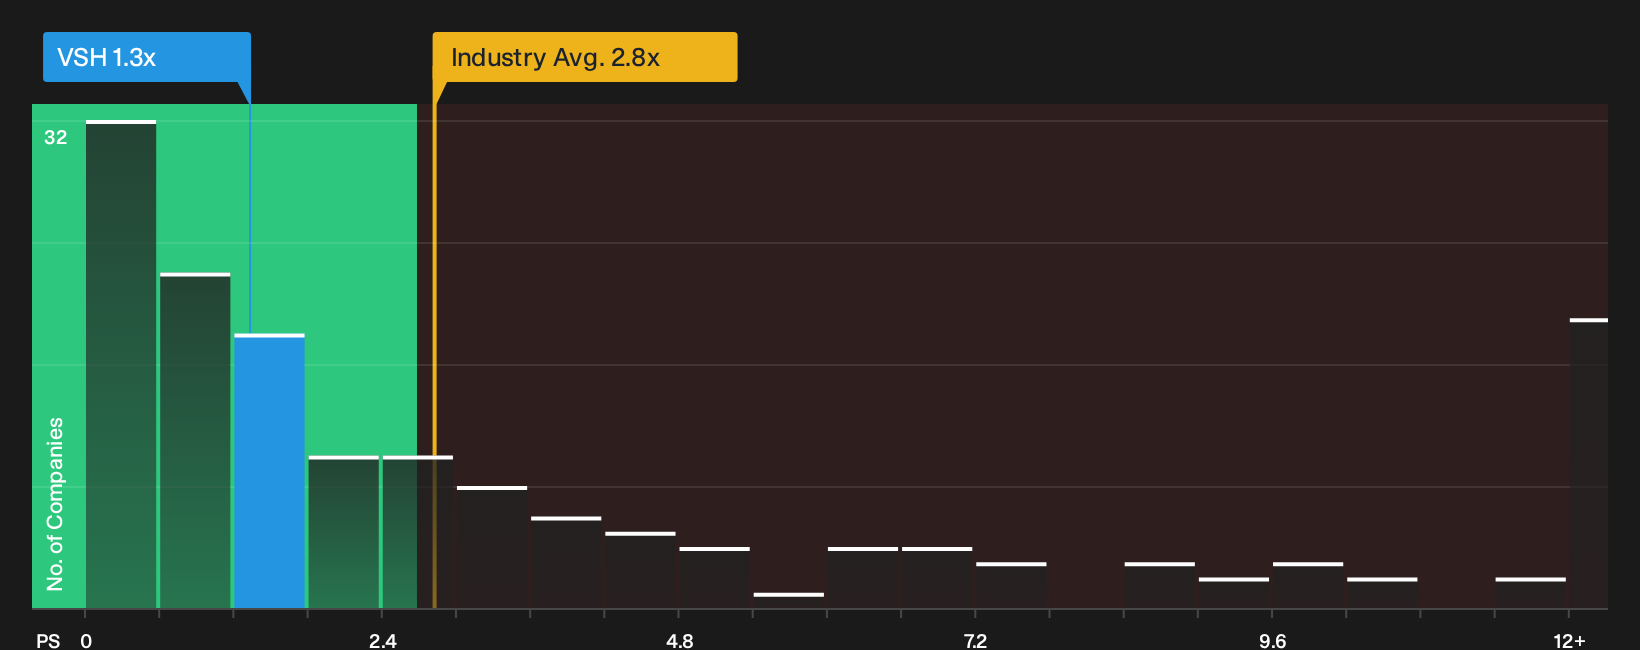
On price targets and fair value models, Vishay Intertechnology screens as undervalued. On sales multiples, the picture is more mixed. The P/S ratio sits at 1.3x, which matches the 1.3x fair ratio, yet it is far lower than the 2.8x US Electronic industry average and 3.1x peer group level. That gap can look like a margin of safety or a sign that the market is still questioning how durable future earnings might be.
Before leaning on any one method, it helps to see how the numbers stack up across different checks. This includes our valuation breakdown that focuses on this sales multiple and the fair ratio the market could drift toward over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in the Vishay Intertechnology story so far. If you want to move quickly and decide where you stand, start by weighing the 3 key rewards and 4 important warning signs.
Looking for more Vishay Intertechnology style ideas?
If Vishay Intertechnology has sharpened your focus on valuation and fundamentals, do not stop at a single opportunity. Broader ideas can help round out your watchlist.
- Spot potential bargains early by scanning companies that screen as high quality and potentially undervalued using the 35 high quality undervalued stocks.
- Strengthen your downside protection by reviewing a 32 resilient stocks with low risk scores and see which businesses line up with your comfort for volatility.
- Support future watchlist candidates with healthier finances by filtering through a list of solid balance sheet and fundamentals (25 results) before the market pays closer attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com