
Why Everyone Is Watching SEI Investments (SEIC) Today
Why SEI Investments Stock Is Back In Focus
SEI Investments (SEIC) has drawn fresh attention after appointing Kristie Edling-Day as Chief Information Officer, putting a veteran technology leader in charge of its digital transformation and product platforms.
The move gives investors a new angle to assess SEIC, since enterprise technology, cybersecurity governance, and platform modernization now sit with an executive who has long experience running large scale systems for financial advisors and institutional clients.
Recent moves in SEI Investments stock reflect that mix of change and execution, with the share price at US$104.79 after a modest 1-day gain of 0.37%, a 90-day share price return of 6.12%, and a 1-year total shareholder return of 28.60% building on a 3-year total shareholder return of 99.64%. This comes even as the 7-day and 30-day share price returns have drifted slightly lower and investors weigh the CIO appointment alongside the new ICE ETF Hub agreement.
Spot similar fintech and investment platforms building out long-haul technology and data capabilities with our curated 20 high quality undiscovered gems.Bulls see SEI Investments turning fresh tech leadership and the ICE ETF Hub linkup into durable earnings power. Bears see a mature business that is already priced for that. The valuation work now shows which case carries more weight.
Most Popular Narrative: 19% Undervalued
SEI Investments most followed narrative pegs fair value at $129, above the last close of $104.79. This puts the valuation debate squarely on future outsourcing demand, margin work, and tech spending discipline.
SEI is deliberately front loading spending on technology, AI, tokenization and talent ahead of anticipated growth, and management has already cautioned that IMS margins could flatten or decline into 2026. If the long term sales pipeline or international expansion fails to materialize at the expected pace, elevated cost levels could structurally compress operating margin and limit EPS expansion.
See why 0 investors see SEI Investments as 19% undervalued.
Result: Fair Value of $129 (UNDERVALUED)
Still, the bullish SEI Investments story runs into two clear pressure points if outsourcing demand cools or if higher technology spending weighs on margins for longer than expected.
Find out about the key risks to this SEI Investments narrative.
Another View On SEI Investments Valuation
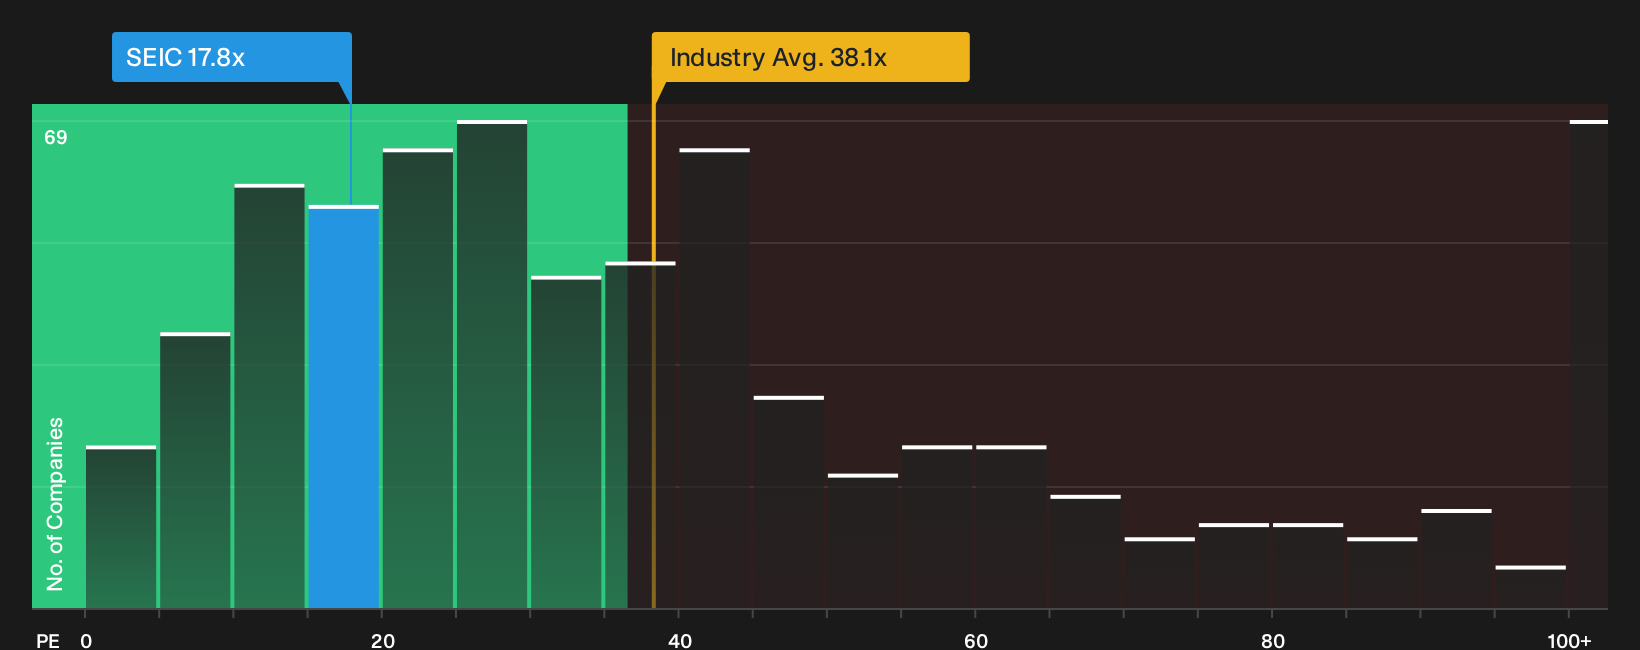
The story looks different when you step away from fair value models and focus on the current P/E. SEI Investments trades on 17.8x earnings, while the fair ratio is 11.7x. This signals less upside if sentiment cools and the market drifts back toward that lower multiple.
Peer context matters too. The same 17.8x P/E sits well under both the US Capital Markets industry at 38.1x and the peer group at 35.9x. This suggests investors are paying a lower headline multiple but still more than the fair ratio points to, so which reference point deserves more weight in your own work.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals on SEI Investments leave you torn, move quickly and review the full risk reward picture yourself with 3 key rewards and 1 important warning sign.
Looking for more SEI Investments style ideas?
Do not stop your work at SEI Investments. Use the same discipline to scan fresh opportunities so you are not relying on a single story.
- Target resilient balance sheets and steady fundamentals by running a focused search through our list of solid balance sheet and fundamentals (25 results).
- Hunt for quality businesses that trade below what their financials suggest they could justify using the 35 high quality undervalued stocks.
- Zero in on resilient companies with lower overall risk profiles before they move to everyone’s radar by screening through the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com