
Viasat (VSAT) Rallied This Year, Is It Still 42% Undervalued?
Viasat (VSAT) has drawn fresh attention after recent trading left the stock up 60.2% year to date, even though it has declined over the past month and the past 3 months.
That sharp 60.2% year-to-date share price gain for Viasat sits alongside a recent loss of momentum, with the stock down 21.1% over the past month and 18.9% over the past quarter, even as long-term total shareholder returns remain strong.
Compare Viasat's sharp swings with other hand-picked communications and tech players moving on similar themes using the 20 high quality undiscovered gems.
Viasat has surged this year yet still trades well below the average analyst target and a separate intrinsic value gauge. Does that gap reflect genuine upside potential, or a market that is rightly cautious?
Most Popular Narrative: 42% Undervalued
At a last close of $60.29, the most followed narrative around Viasat points to a fair value of $103.94. This frames a wide gap that hinges on how much of its spectrum and satellite buildout can be converted into lasting cash generation.
The focus on operational efficiency, portfolio review, and progressing integration with Inmarsat, in addition to CapEx peaking with the ViaSat-3 program, sets up Viasat for positive free cash flow inflection, deleveraging, and earnings improvement as major investment cycles wind down.
See why 30 investors see Viasat as 42% undervalued.
Result: Fair Value of $103.94 (UNDERVALUED)
Still, the narrative around Viasat hinges on heavy ViaSat-3 and Inmarsat spending, as well as on regulatory decisions that could slow or dilute spectrum monetization.
Find out about the key risks to this Viasat narrative.
Another View: Viasat Through A Cash Flow Lens
The first story around Viasat leans heavily on analyst targets and spectrum driven upside. A second, simpler yardstick tells a different story. The SWS DCF model values the stock at $53.03, which sits below the current $60.29 price and frames Viasat as overvalued on projected cash flows.
That gap suggests less of a margin of safety if free cash generation comes in below bullish expectations or arrives later than hoped. It also pushes you to ask a harder question: Is the spectrum and contract narrative strong enough to offset what a more conservative cash flow model is implying?
Look into how the SWS DCF model arrives at its fair value.
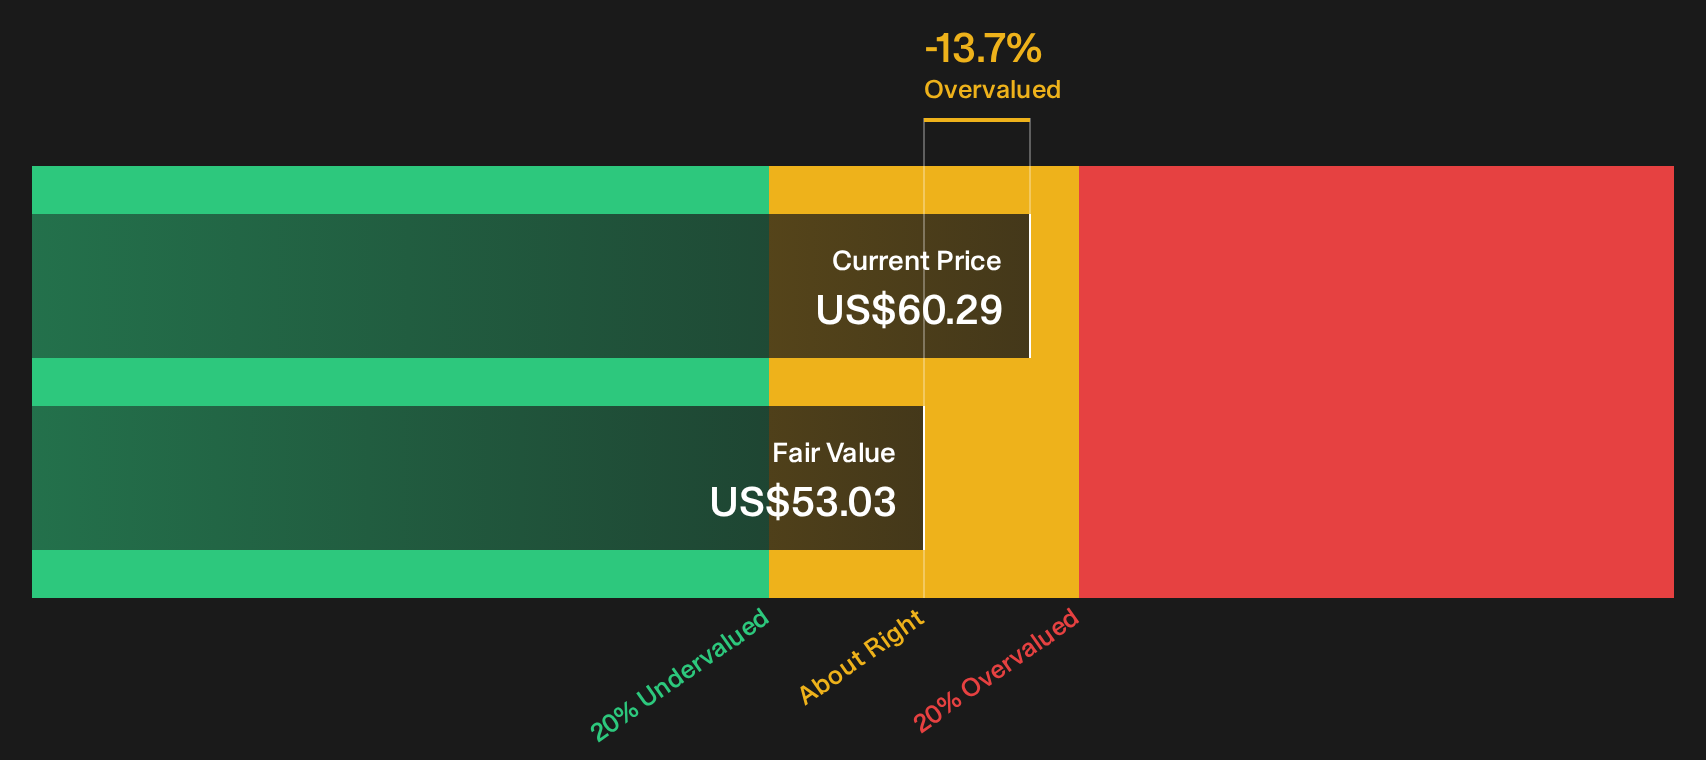
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Viasat for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Viasat story so far. Do not wait for consensus to harden. Weigh both sides of the argument for yourself and stress test your own thesis using the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Viasat?
If Viasat has you thinking harder about where risk and reward really line up, this is the moment to widen your net before the next move passes you by.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (25 results) that filters for financial strength first.
- Hunt for mispriced opportunities using a focused list of 35 high quality undervalued stocks that pair quality metrics with attractive valuations.
- Dial down volatility and concentrate on stability by checking a curated pool of 32 resilient stocks with low risk scores designed to keep downside in sharper focus.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com