
Why Agilysys Stock And Enterprise Software Shares Could Keep Raising Customer Costs
Enterprise software is quietly becoming a tax on corporate life, with forced upgrades, licensing tweaks and hardware refreshes eating deeper into budgets each year. That pressure can punish some stocks yet support others that enjoy locked in contracts and recurring subscription or license income. This article walks through three large cap platform vendors exposed to that trend and explains how rising software dependence could help or hurt their shares over time.
The stocks covered below are just a starting sample, and the full screen surfaced 24 more large cap enterprise software vendors with equally interesting platform and subscription stories that are not covered in this article. To identify and analyze the highest conviction ideas for your own watchlist, head straight into the Large-Cap Enterprise Software Vendors screener.
Agilysys (AGYS)
Overview: Agilysys provides cloud based enterprise hospitality platforms that run hotel, resort and casino operations through tightly integrated property, point of sale and guest experience software.
Operations: Agilysys generates about $330 million in revenue from providing software solutions to the global hospitality industry, centered on enterprise platforms and services.
Market Cap: US$3.1b
Agilysys fits this large cap enterprise software screen because its hospitality platforms are embedded deep in day to day hotel and resort workflows, creating recurring subscription and upgrade opportunities that can feel like a permanent line item in a property’s budget.
"Although Agilyss continues to win large multiproduct ecosystem deals and reports that add on modules account for over a third of subscription revenue, hospitality operators may eventually push back on vendor concentration and total cost of ownership."
What happens to Agilysys’ growth story depends heavily on how one unseen pressure shapes future pricing power and contract renewals.
That pricing pressure is exactly what makes the full narrative for Agilysys worth reading, as it unpacks where pricing power could accelerate or quietly stall Agilysys’ future story.

SPS Commerce (SPSC)
Overview: SPS Commerce runs a cloud supply chain platform that lets large retailers and their suppliers automate orders, invoices, data sharing and related workflows.
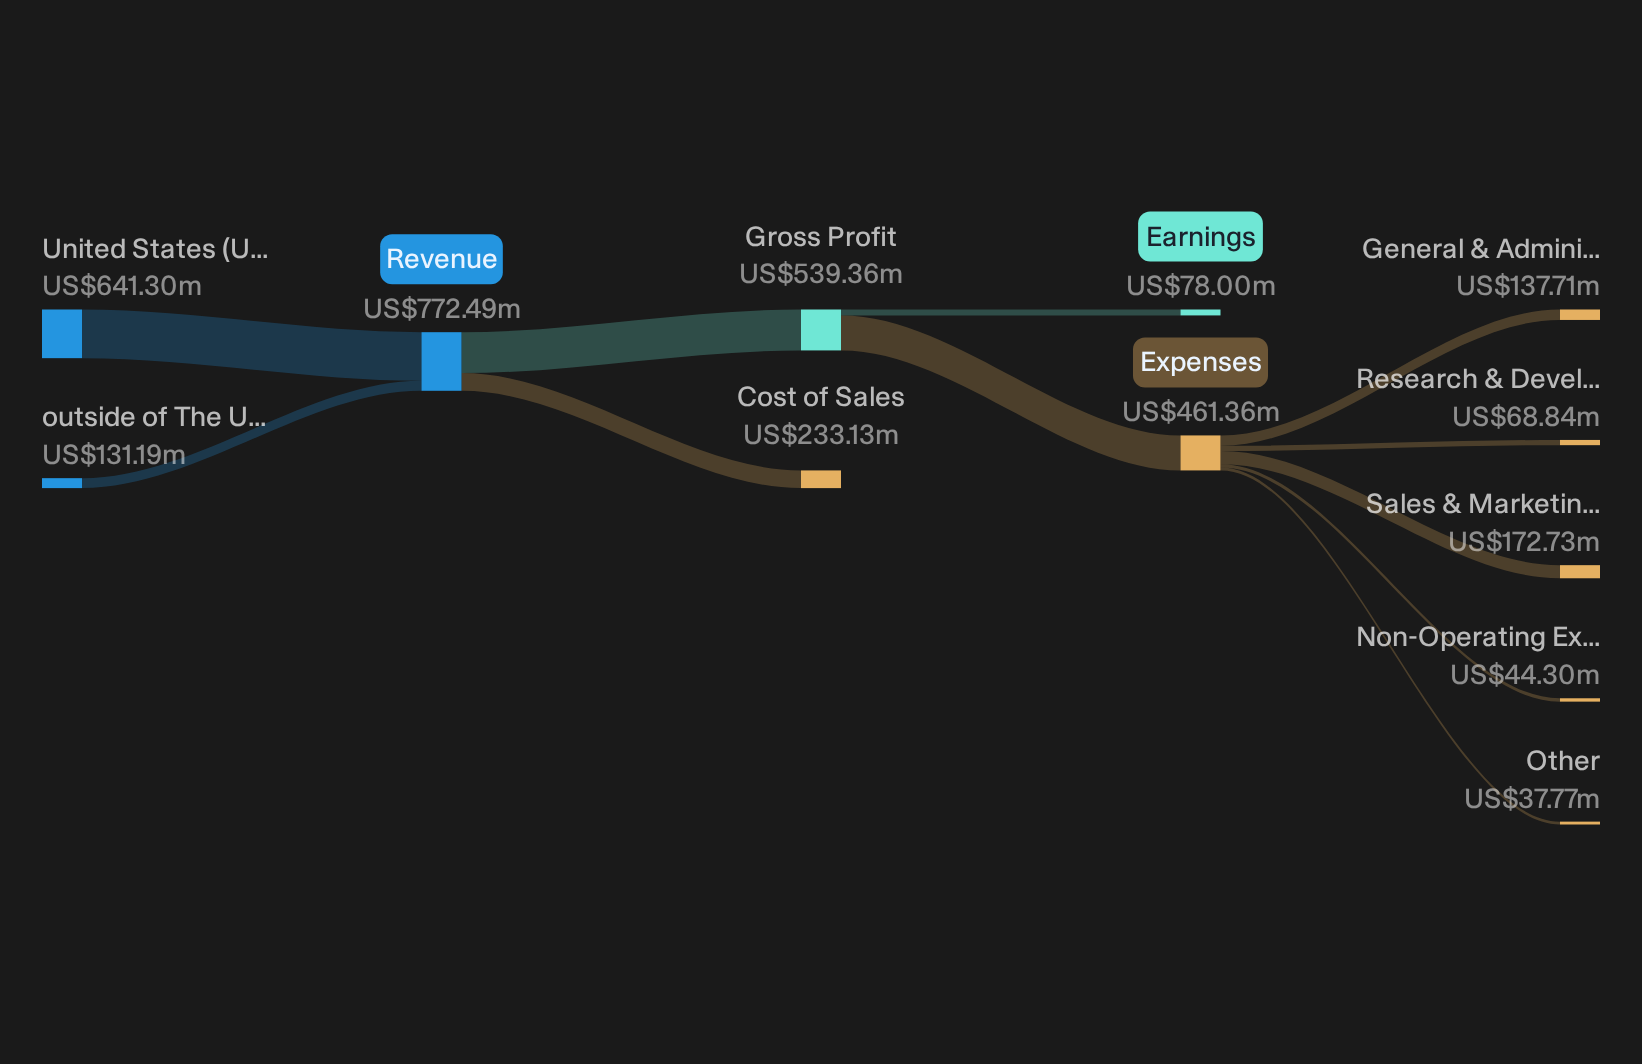
Operations: SPS Commerce generates about US$772 million from supply chain management solutions, mostly in the U.S. at roughly US$641 million, with the balance overseas.
Market Cap: US$3.1b
SPS Commerce fits this enterprise software screen because its subscription platform is wired into how retailers and brands run daily trading relationships. This gives the business recurring revenue and upgrade levers that can feel like a permanent infrastructure cost for customers.
"Customer growth for SPS Commerce is expected to be roughly flat to slightly positive in 2026, with a recent decline of a little over 200 1P customers. This increases reliance on extracting more ARPU from the existing base to support consolidated revenue and earnings."
What happens next for SPS Commerce depends heavily on how one quiet shift in how customers use and value its AI enabled tools affects pricing power.
That reliance on ARPU makes the full narrative for SPS Commerce a useful read for seeing how SPS Commerce could turn flat customer trends into accelerating value for long term holders.
Vertex (VERX)
Overview: Vertex provides enterprise tax software and services that automate indirect tax calculation, e-invoicing and compliance for large global retailers, wholesalers and manufacturers.
Operations: Vertex generates about $787 million in software and programming revenue, with roughly $701 million from the United States and $86 million from overseas markets.
Market Cap: US$2.2b
Vertex matters for this enterprise software screen because its tax platform is embedded directly into large ERP and billing systems. This can turn regulatory change into a recurring subscription and licensing story rather than a one off consulting project.
"Regulatory mandates for real-time e-invoicing in large European economies, including the September 2026 French requirement and the January 2027 German requirement, are expected to direct more invoice volume onto Vertex e-invoicing platforms, which could add to subscription revenue and transaction driven revenue."
What happens to Vertex’s valuation story now largely depends on how one quiet shift in customer adoption shapes long term margins and renewal economics.
Those renewal economics are exactly what the full narrative for Vertex unpacks, showing where regulatory volume could be accelerating value and where risks might still be masking upside.

Seeking Alternatives Before The Crowd?
Fresh opportunities can move from quiet to flying under the radar for now to fully caught by the crowd. Review these ideas while they are still emerging.
- Identify potential income workhorses and review the curated 8 dividend fortresses aimed at continuing to pay investors even when market momentum shifts elsewhere.
- Explore early trendsetters and scan the curated 20 high quality undiscovered gems that remain under most radars today yet have defined fundamental backing.
- Focus on long term tech themes and work through the 55 AI infrastructure stocks that highlights companies involved in AI-related infrastructure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com