
What Viatris Holders Bought Into Before An 83% Run
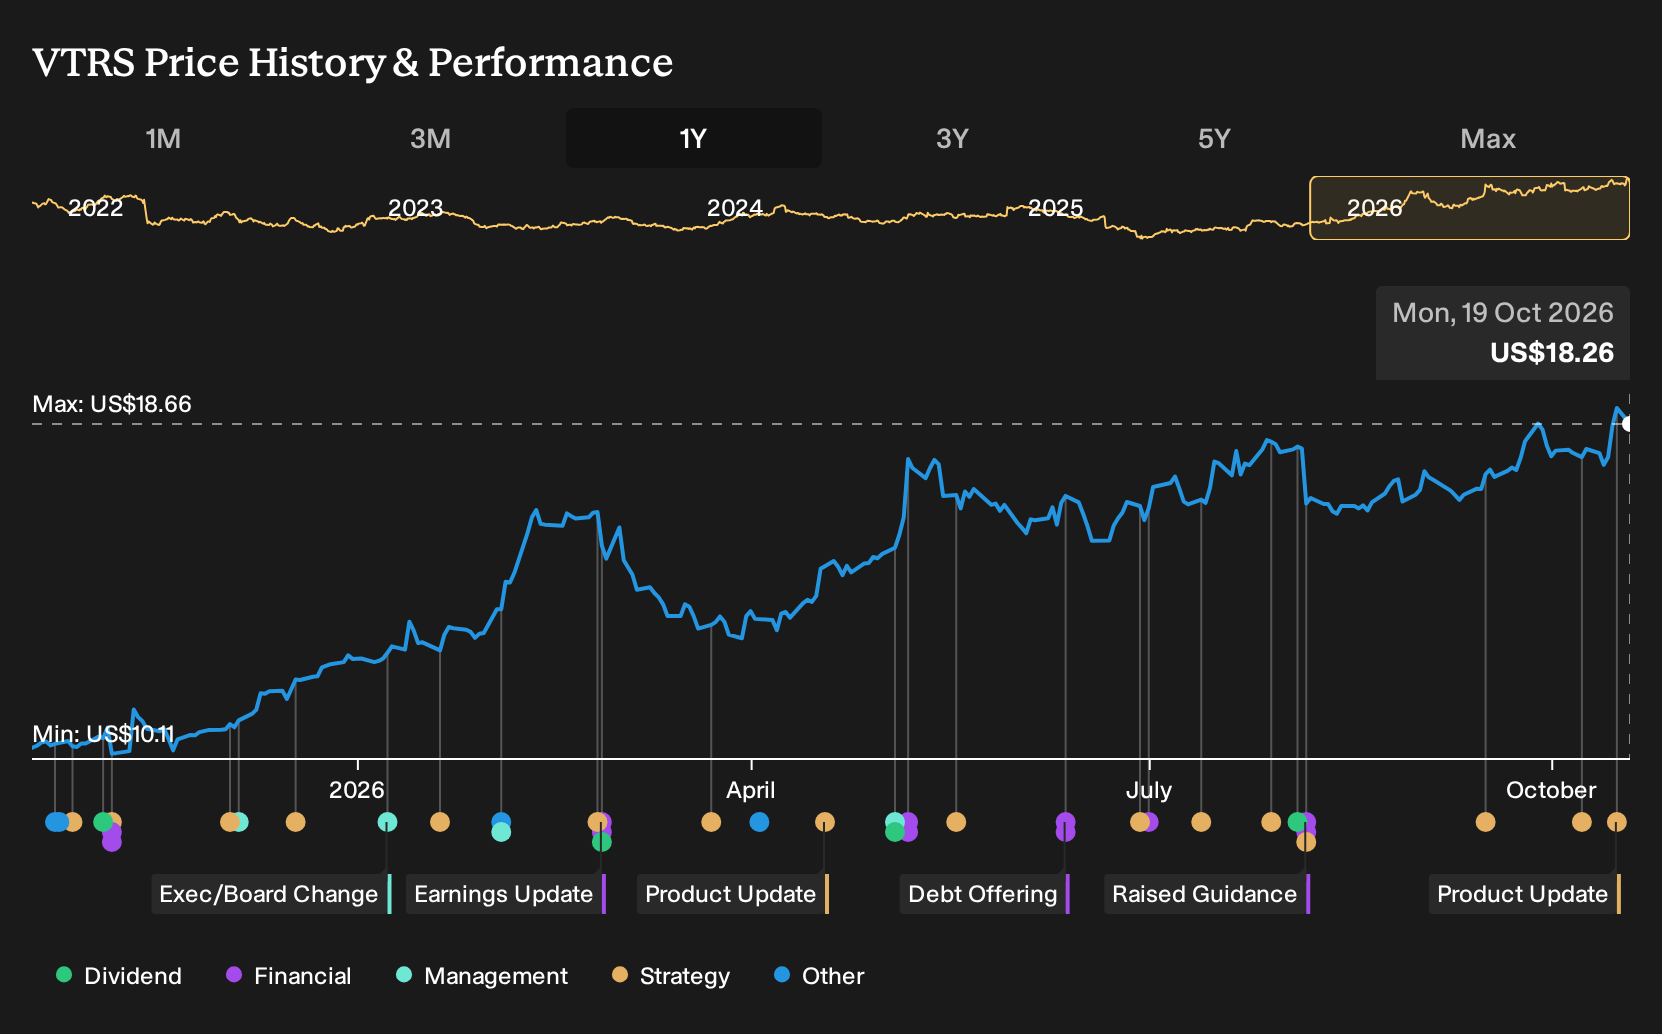
Holding Viatris over the past year would have returned 83.4%, including dividends. That outcome sits between two very different starting points. One bullish October 2025 view saw aging populations in Asia, late-stage pain and eye drugs, and cost cuts as reasons the shares were trading about 12% above the analyst fair value. A bearish camp argued regulatory pressure, debt and reliance on mature generics pointed nearer to US$8. If you were weighing Viatris on 19 October 2025, which side of that gap would have felt more convincing?
Viatris is not the only name tied to this theme. Zero in on 33 healthcare AI stocks and compare how each one is priced.
The Argument You Would Have Had To Settle On Viatris
The shares cost US$10.17 at the start of the period, and Viatris sat between two very different stories about where value might come from.
The bullish Narrative pointed to a Fair Value of US$11.43, a price those assumptions implied rather than a hard fact, anchored in aging populations and emerging Asia. That view leaned on revenue change of 0.9% a year and profit margins rising to 2.9%.
The bearish camp worked off a Fair Value of US$8 built on regulatory pressure and heavy debt. It assumed revenue change of 0.4% and margins reaching only 0.7%, with a very high future P/E of 113.4x needed to support that price.
What The Evidence Around Viatris Actually Tested
The Pacira deal, FDA approvals for Gwyn Lo and RYZUMVI, and multiple positive Phase 3 updates gave clear backing to the bullish Viatris story that leaned on higher margin products and late stage drugs. The measured figures told a harder truth. Revenue moved from US$3,582.1m in Q2 2025 to US$3,756.8m in Q2 2026, while the business reported a larger loss and net margin fell from -0.1% to -3.2%. Overall, the evidence cut both ways.
The lesson is simple. When a thesis rests on better profitability, you need to track net income and margin, not just new products or higher sales. For any healthcare stock pitched on “mix upgrade”, check whether margin is actually improving in the reported numbers before you lean on the story.
What Viatris' Run Up 83% Already Builds In
Viatris now trades at US$18.26 after gaining 83.4% over the past year. The selected Narrative’s Fair Value sits below the current price, so its author sees today’s level as already baking in a lot of the good news.
The core idea is simple. Buyers now pay up assuming the shift to higher margin, branded drugs and international growth offsets pressure on generics and debt. The open question is how that assumption stacks up against the execution and regulatory risks the Narrative spells out.
"Significant debt obligations from the legacy Mylan/Upjohn merger, combined with ongoing integration challenges, could severely constrain Viatris'' ability to invest in new growth drivers or respond to competitive threats, threatening free cash flow generation and future shareholder returns through dividends and buybacks."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking Past Viatris' Drug Mix
Viatris leans on better drugs and sharper execution. You could also look sideways. Healthcare weight in your portfolio does not need one route.
Another large player is pouring money into new medicines and medical hardware. It targets treatments for difficult cancers, immune disorders and brain conditions.
That same group is developing surgical tools and eye care technology. The aim is straightforward. Help doctors handle more complex procedures with more capable equipment.
If those therapies and devices gain traction, the revenue mix could shift toward higher value treatments and procedures. That changing balance remains the deeper thread to explore.
One Narrative has already put a figure on it. → Uncover the company trading 21% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com