
Could Phillips 66 (PSX) Be 5% Above Fair Value As It Lifts Its Dividend?
Phillips 66 (PSX) has put income front and center, with its board approving a higher quarterly dividend of US$1.33 per share, up US$0.06, against a backdrop of elevated U.S. gasoline prices.
Recent trading has reflected that backdrop. The share price is now US$290.55, with a 30-day share price return of 6.38% and a 90-day share price return of 36.88%. The 1-year total shareholder return of 129.52% and 5-year total shareholder return of 316.08% indicate strong momentum building around Phillips 66 as investors respond to higher payouts and ongoing refinery tightness.
Scan beyond Phillips 66 and see how other refiners and energy plays stack up on income strength and recent momentum by reviewing the hand picked 8 dividend fortresses
The share price already reflects a big swing in sentiment around Phillips 66 and its dividend story. How much of that move lines up with what the underlying business and current valuation actually support?
Most Popular Narrative: 5% Overvalued
Against the last close at $290.55, the most followed narrative anchors Phillips 66 at a fair value of $276.32 based on a 7.24% discount rate and detailed cash flow assumptions. This leaves the current income fueled rally slightly ahead of that modeled estimate.
Phillips 66 is viewed as fairly valued and bullish, and current earnings, cash generation and cash return levels imply the share price already reflects a large part of the expected margin strength and operational improvement story.
See why 48 investors see Phillips 66 as 5% overvalued.
Result: Fair Value of $276.32 (OVERVALUED)
Still, Phillips 66 faces two clear pressure points, with union action at the Bayway refinery and potential derivative losses both capable of disrupting cash returns and operations.
Find out about the key risks to this Phillips 66 narrative.
Another View: Phillips 66 Through The Market’s Lens
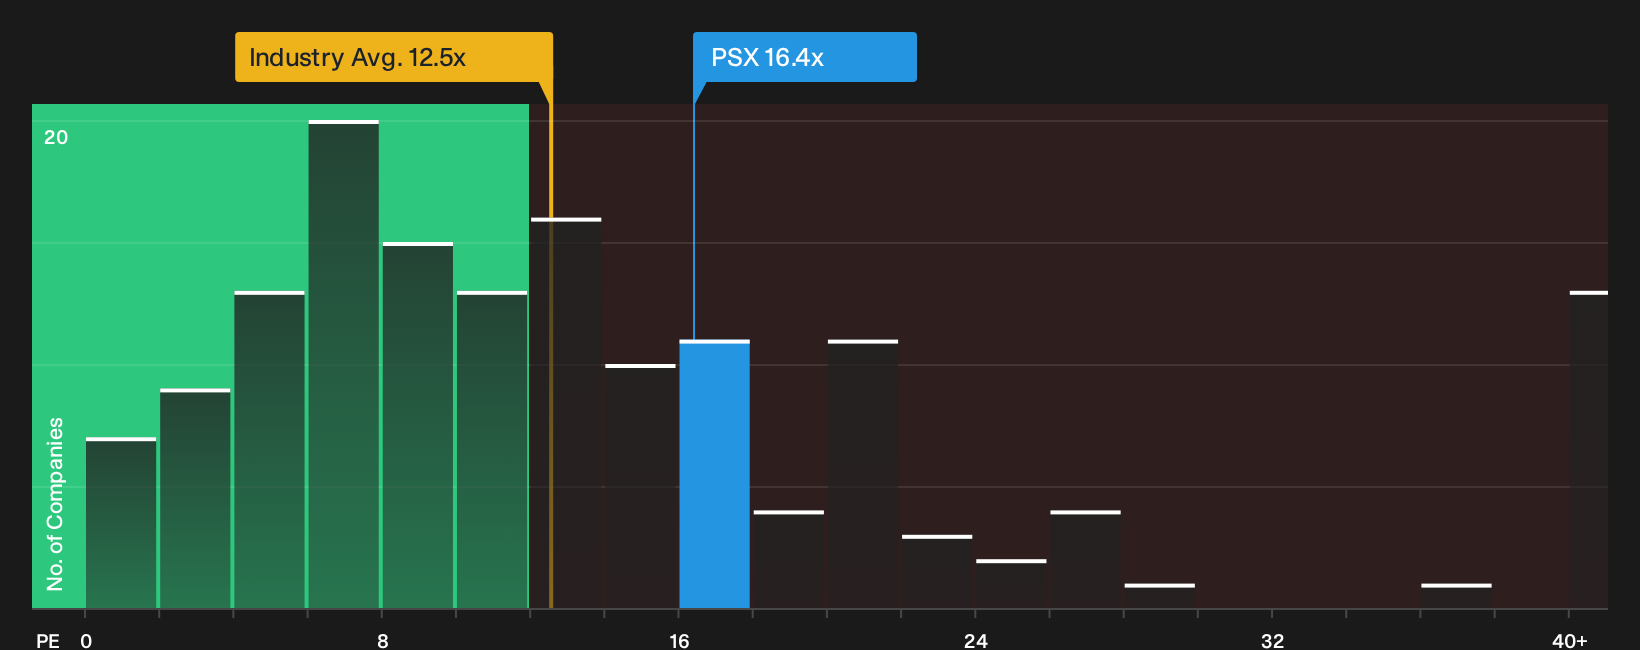
Analyst models point to a fair value of $276.32, which suggests Phillips 66 trades above that consensus. The market is telling a slightly different story. At a P/E of 16.4x versus an industry average of 12.5x and a fair ratio of 16.9x, investors are paying a premium that is close to what regression work suggests the ratio could move toward. Is that narrow gap a cushion or a thin margin for error if sentiment cools?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Phillips 66 is split between optimism on rewards and concern about specific risks. Move quickly, review the data, and weigh both sides through the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Phillips 66?
If you only stop at Phillips 66, you could miss other opportunities that fit your goals, income needs, and risk comfort just as well.
- Target resilient compounding potential by filtering for companies with strong cash positions and low leverage through our list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities by scanning a curated set of companies trading below estimated worth using the 35 high quality undervalued stocks.
- Stack your watchlist with fresh prospects by zeroing in on quality businesses that many investors overlook through the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com