
Sansan And 2 Other Japanese Founder Led Stocks To Own
Japanese founder-led businesses are drawing fresh attention as global investors focus on leadership that can adapt to rising inflation and changing trade rules. Central banks are reassessing policy and regulators are rewriting the playbook, so capital is searching for owners with real skin in the game. This article walks through three founder-run Japanese stocks from our screener that aim to turn long-term commitment into potential shareholder value.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is personally tied to long term outcomes. However, if you want the standouts, these 11 top founder-led companies are the most outstanding.
Sansan (TSE:4443)
Sansan is a Tokyo based software group built around founder led cloud products that turn business cards and invoices into usable data, including the Sansan contact management platform, Bill One and Eight. Most revenue comes from the Sansan/Bill One segment at ¥48,865 million, with Eight contributing ¥7,143 million, and the company is valued at about ¥251.5b.
Sansan ties the founder’s product vision directly to how customers manage contacts, invoices and contracts. Recent guidance and results point to a business that is growing while lifting profitability. For anyone backing founder run platforms, the key question is how long that product edge can sustain pricing and margin power if a single assumption about demand shifts.
To see how much room that edge might really have, study the DCF valuation analysis for Sansan and judge whether Sansan’s ambition is already fully priced in or still underestimated.
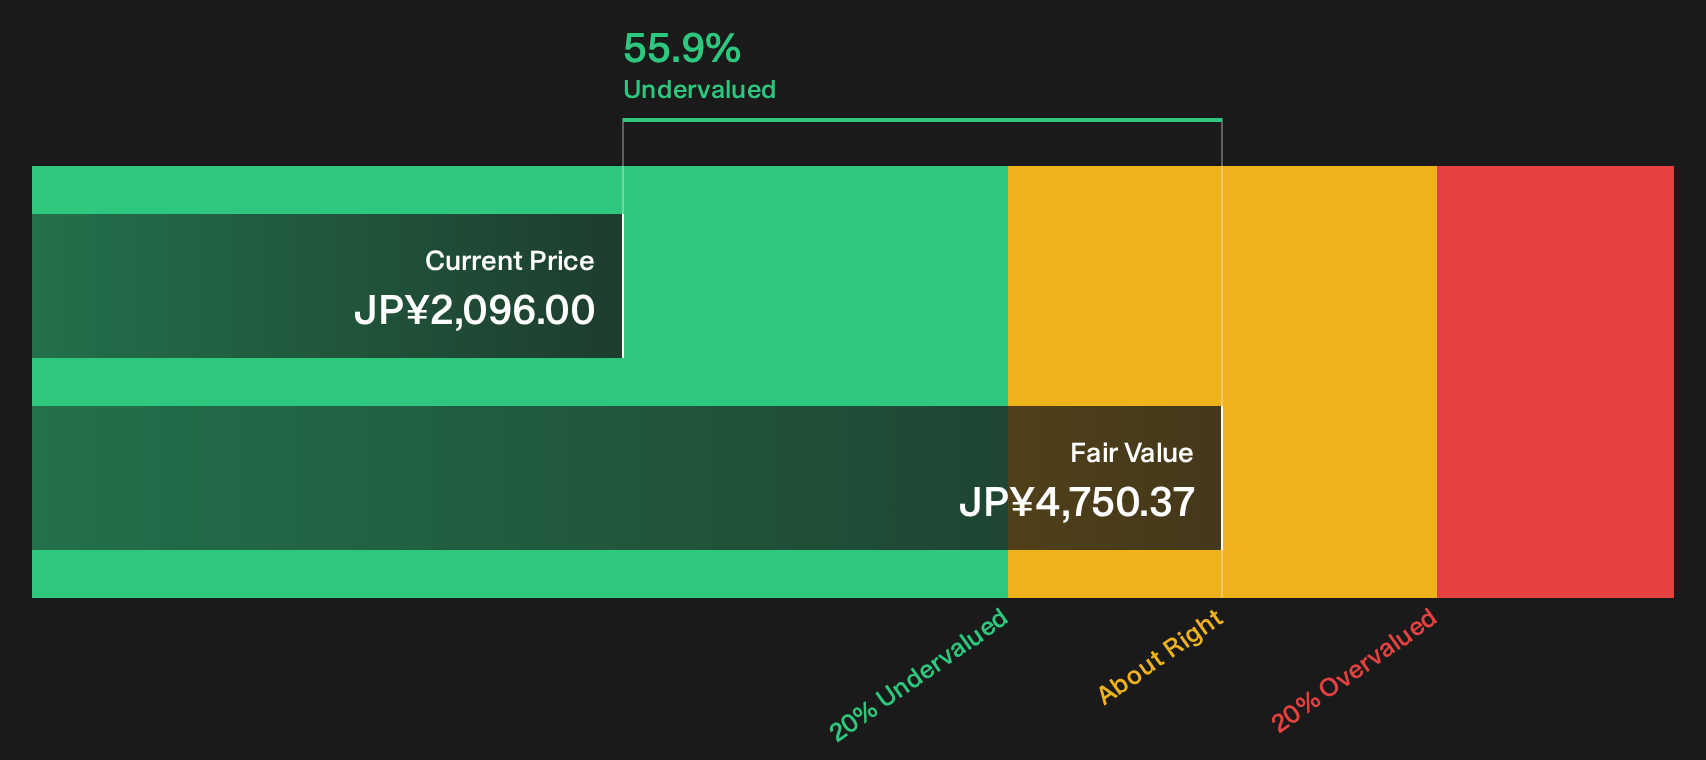
CyberAgent (TSE:4751)
CyberAgent is a founder-led digital group shaped by Susumu Fujita’s long-running leadership, with operations spanning internet advertising, media platforms like Ameba and smartphone games. The company generated ¥478.2b from advertising, ¥269.7b from games and ¥246.6b from Media & IP, and has a roughly ¥668.7b market value.
For investors drawn to founders who still set the agenda, CyberAgent offers a clear example of long-term leadership attempting to turn media platforms and game studios into a lasting franchise. The key interest today lies in how that approach is now feeding into its media economics.
"The Media & IP segment, including ABEMA, has moved from gradually decreasing losses to reporting operating profit of JPY 4.9b in the first quarter of FY 2026 while ABEMA turned profitable, so further monetisation of original IP such as anime and films now has a clearer path to influence segment revenue and operating margins."
The next chapter for CyberAgent largely hinges on how one shifting line item filters through to group margins and the durability of that founder-led model.
That hinge point around margins is exactly where the story gets interesting. Read the full narrative for CyberAgent to see how ABEMA’s profitability could be masking deeper shifts.

DeNA (TSE:2432)
DeNA runs a founder-influenced portfolio of mobile games, live streaming, sports teams and digital healthcare services, with gaming bringing in ¥58,341 million, livestreaming ¥39,544 million, sports ¥34,569 million and healthcare ¥8,659 million, alongside other smaller units, on top of a roughly ¥234.6b market value.
For founder-led investors, DeNA offers something different from a single-product story. Long-running leadership influence flows through its games, sports assets and healthcare tools, then into vehicles like Delight Ventures that decide where the next wave of effort and capital goes.
"Rapid global adoption and engagement with Pokemon Trading Card Game Pocket, launched in 150 countries with reported strong download and retention metrics, may position DeNA to benefit from expanding mobile internet usage and the monetization of digital content."
The real test for DeNA now is how one pressure on future earnings shapes management’s choices on buybacks, reinvestment and eventual margin strength.
That pressure point on future earnings is exactly where the story could accelerate or stall, and the full narrative for DeNA shows how DeNA’s portfolio decisions might reshape that path.

Seeking Alternatives Before Everyone Else?
Fresh ideas move first. Breakout stories build momentum while they are still under the radar for now and laggards keep dropping. Get in early and act now.
- Spot income workhorses built for consistency and scan a curated mix of cash generators in the 30 dividend fortresses before the yields get caught by yield chasers.
- Ride the next wave of automation and sort through carefully filtered builders in the 92 robotics and automation stocks while the market is still pricing old-world workflows.
- Position ahead of the energy grid overhaul and review screened operators in the 42 power grid technology and infrastructure stocks while the transition story is only partially reflected in prices.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com