
Principal Financial Group (PFG) Stock May Sit Above Fair Value On Earnings
Principal Financial Group has delivered a strong multi year run, so the question now is whether the current share price still lines up with what its earnings can reasonably support. With the stock recently closing at US$106.86, investors are asking if that level is grounded in the underlying profit engine or leaning too hard on past gains.
- Over the past 5 years, Principal Financial Group has returned 83.4%, which raises the question of how much of that strength is backed by sustainable earnings power.
- The business leans heavily on fee based and insurance earnings, so the durability of those profit streams and the capital they require may shape how much investors are willing to pay for each dollar of income.
- The analysts covering Principal Financial Group have run their own numbers. See what analysts think Principal Financial Group's shares could be worth.
The issue now is whether Principal Financial Group's current valuation can be explained by its earnings record and what the market expects those profits to deliver next.
If you are weighing whether Principal Financial Group's earnings still justify the recent share price, a focused stock screen built around 35 high quality undervalued stocks.
Does Principal Financial Group Look Pricey on Earnings?
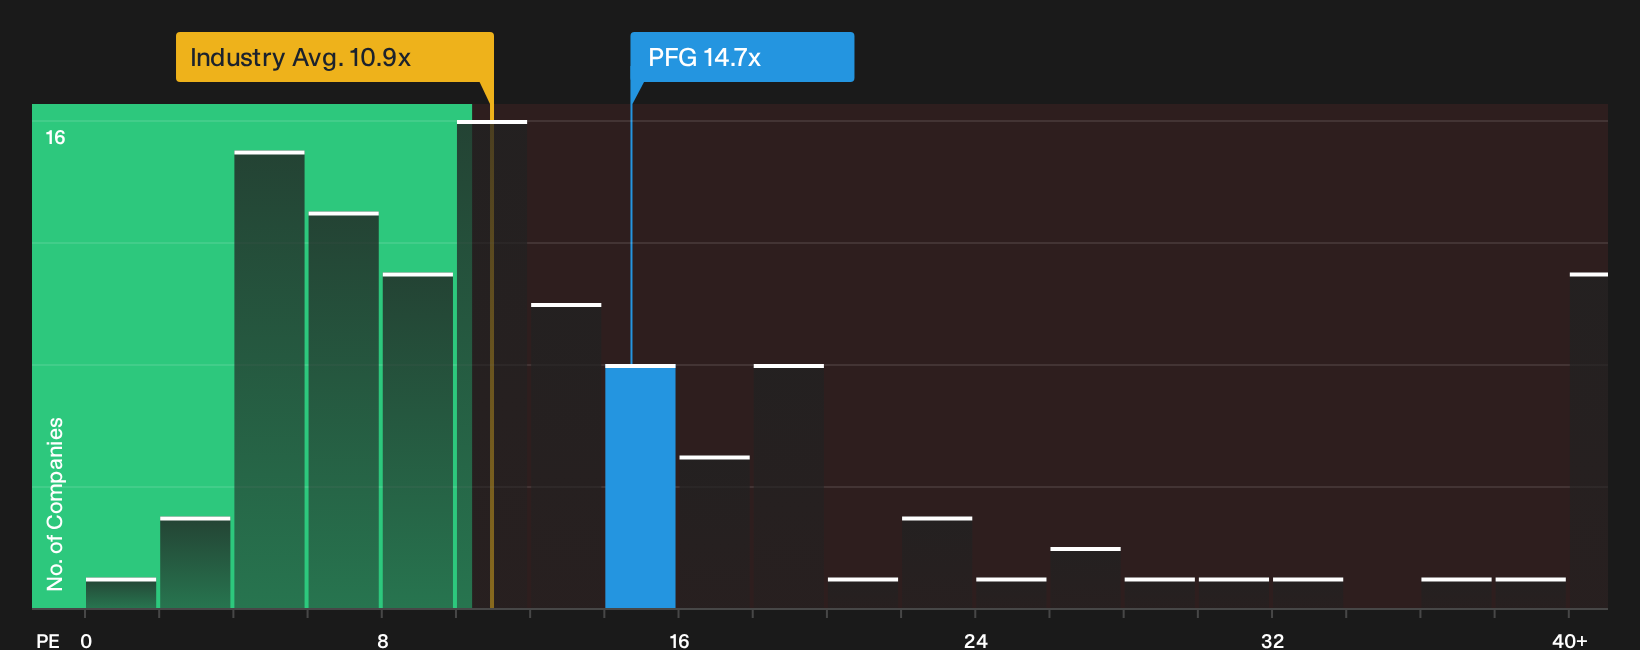
P/E fits Principal Financial Group well because earnings are a central yardstick for fee based and insurance focused businesses. On that measure, the stock trades at about 14.7x, compared with an Insurance sector average near 10.9x and a peer group around 36.5x. The P/E therefore sits above the wider industry but below the richer end of direct comparables. That indicates the market is paying something extra for each dollar of profit.
A more tailored benchmark suggests what buyers might typically pay for Principal Financial Group once its growth profile, profitability and risk are blended into a single yardstick. Against that customised yardstick, the current 14.7x P/E screens as overvalued, implying the market is attaching a higher earnings multiple than the model would assign to the same fundamentals. For you as a shareholder or potential buyer, the key judgement is whether the quality and durability of those earnings justify paying that richer price tag on current profits. Explore the numbers behind Principal Financial Group's P/E valuation.
The Principal Financial Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Principal Financial Group leaves off by explaining which combinations of future growth, margins and earnings would need to hold for the stock to be worth materially more or less than it is today. Each narrative connects a fair value view to a specific path for Principal Financial Group's catalysts and risks so you can track over time which story is actually taking shape on the Community page.
Community views on Principal Financial Group split between investors who see the current setup as roughly in line with earnings power and those who think expectations already stretch too far.
Bull case: roughly fairly valued
"The focused push in small and midsized business retirement and benefits, including deeper cross sell that has lifted products per employer and the addition of more than 25,000 small business customers from Beam Benefits, is aimed at building a larger premium and fee base over time…"
Discover why this Narrative puts Principal Financial Group at roughly fairly valued.
Bear case: 18% overvalued
"Although Principal Financial Group highlights strong recent EPS and margin expansion, the roughly $11b of net outflows concentrated in U.S. active equity strategies that account for just over 5% of assets suggest that if style headwinds persist, fee revenue from this part of asset management could decline further and weigh on total revenue growth…"
Explore why this Narrative puts Principal Financial Group at 18% overvalued.
One unresolved thread for Principal Financial Group
Price multiples tell you what the market pays for Principal Financial Group today, while professional earnings projections sketch where the business might be a few years from now and how that compares with the current tag. Explore where analysts expect Principal Financial Group to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com