
CBIZ (CBZ) Stock Seems Fairly Valued Following $5.0B Takeover Deal
CBIZ has moved steadily higher over the past several years, and with recent news of a planned all cash takeover, the price now carries an extra layer of expectation. That combination puts a spotlight on a simple question for investors who follow CBIZ stock: how much of today’s valuation is really supported by its earnings power?
- CBIZ has returned 50.3% over the past 5 years, which puts meaningful long term gains on the line if its earnings profile does not match up with the current share price.
- The agreed US$5.0b all cash acquisition by Grant Thornton signals a clear market view on CBIZ’s profit potential and cash generation, which may reshape how investors think about the earnings that underpin the stock today.
- There is a second opinion on CBIZ worth weighing. See what analysts think CBIZ's shares could be worth.
The stock's next move may depend on whether the earnings that CBIZ generates are enough to justify where the shares trade now.
If you are weighing CBIZ against other opportunities where earnings support is central to the story, a focused stock screen built around 35 high quality undervalued stocks can be a useful next step.
Is CBIZ Fairly Priced on Earnings?
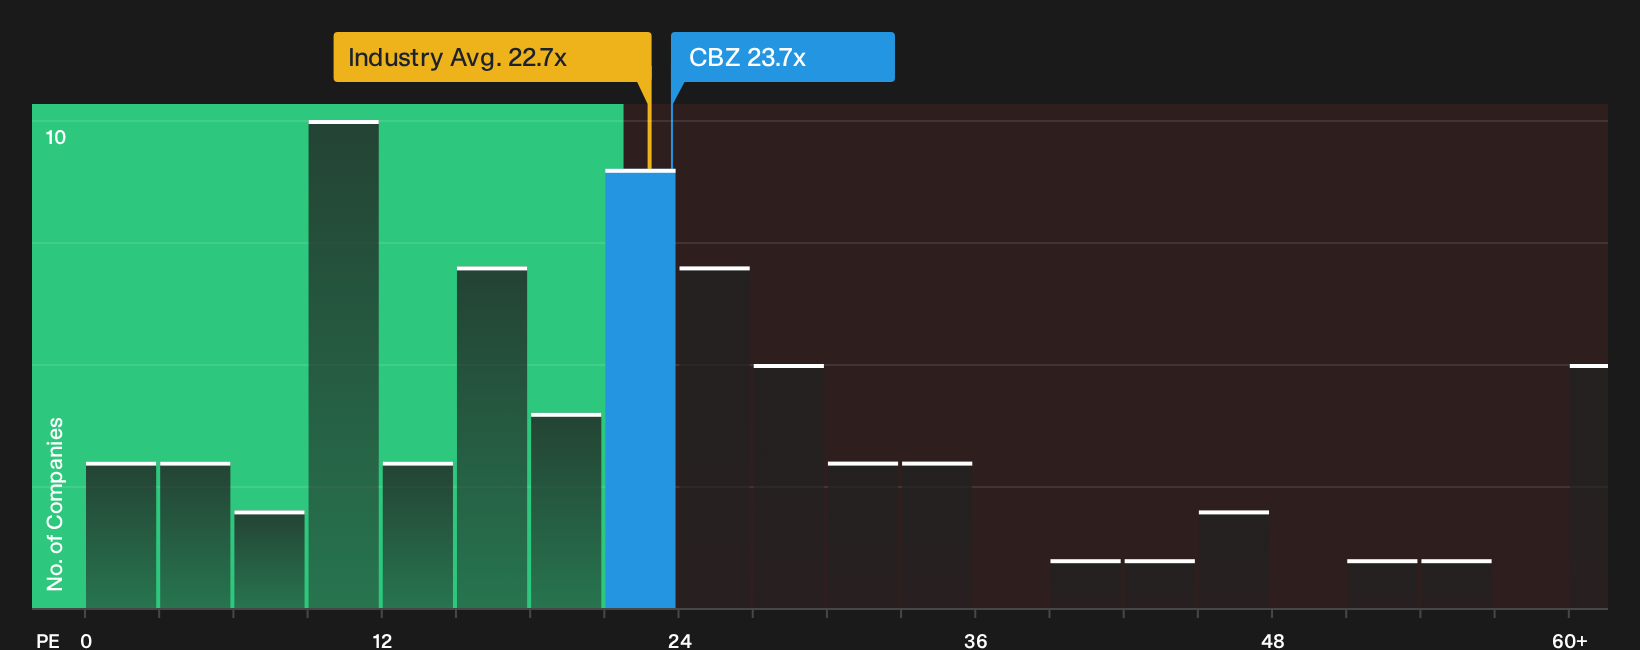
The P/E ratio fits CBIZ well because earnings are a key anchor for how service firms like this get valued. On current numbers the stock trades on about 23.7x earnings, which is very close to both the Professional Services sector average of 22.7x and the peer group at 23.1x. The tailored fair multiple, which blends factors such as CBIZ’s growth profile, profitability and risk, sits very near the current P/E, so the market price looks broadly aligned with what this framework implies for the business.
Because the proposed US$5.0b all cash acquisition by Grant Thornton puts a firm value marker on CBIZ, this near match between the trading multiple and the modelled fair level suggests investors are already treating the stock as roughly fully reflecting its current earnings power. That leaves the takeover timing, deal terms and any shifts in reported profits as the key pieces to watch if you are weighing whether the present P/E still looks worth paying compared with other Professional Services options. Explore the numbers behind CBIZ's P/E valuation.
The CBIZ Narrative: What Would Justify Today's Price?
Narratives for CBIZ pick up where the valuation questions leave off by spelling out what would need to happen to the firm’s growth, margins and earnings for the stock to be worth materially more or less than it is today on Simply Wall St's Community page. Rather than relying on a single multiple or one model result, each narrative lays out the assumptions behind its view of fair value so you can track those against CBIZ's actual results over time.
One of the top community narratives on CBIZ: roughly fairly valued
"CBIZ is rolling out AI enabled workflows across attest and other services, including one use case that is already delivering 20% efficiency in year one…"
Discover why this Narrative puts CBIZ at roughly fairly valued.
One more CBIZ piece investors are watching closely
Current earnings and the takeout price frame where CBIZ is today, but the projection that matters next is how professional analysts sketch this business a few years down the road. Explore where analysts expect CBIZ to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com