
Undervalued Small Caps In Global With Insider Action October 2026
In October 2026, global markets are navigating a complex landscape marked by AI spending concerns and inflation pressures, leading to a rotation from large-cap growth stocks to more value-oriented segments. Amidst this backdrop, the small-cap Russell 2000 Index experienced a notable decline of 3.05%, highlighting the shifting investor sentiment and potential opportunities in undervalued small-cap stocks with insider activity. In such an environment, identifying robust small-cap companies that demonstrate strong fundamentals and strategic insider actions can be crucial for investors seeking value amid broader market volatility.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Transcontinental | 2.7x | 0.2x | -106.57% | ★★★★☆☆ |
| Franchise Brands | 27.0x | 2.0x | 47.84% | ★★★★☆☆ |
| Nexus Industrial REIT | 10.1x | 3.0x | 10.12% | ★★★★☆☆ |
| Pizza Pizza Royalty | 11.7x | 8.9x | 39.82% | ★★★★☆☆ |
| Saniona | 7.5x | 3.3x | 31.07% | ★★★★☆☆ |
| Sagicor Financial | 6.8x | 0.5x | -81.54% | ★★★★☆☆ |
| Yellow Pages | 8.6x | 0.9x | 27.74% | ★★★☆☆☆ |
| Centurion | 15.8x | 3.1x | 19.87% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -230.03% | ★★★☆☆☆ |
| Linc | 12.0x | 12.4x | 35.16% | ★★★☆☆☆ |
Let's dive into some prime choices out of from the screener.
Nine Entertainment Holdings (ASX:NEC)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Nine Entertainment Holdings operates across various media segments, including outdoor advertising, corporate services, publishing, and streaming & broadcast services, with a market cap of A$3.92 billion.
Operations: Nine Entertainment Holdings generates revenue primarily from its Streaming & Broadcast segment, contributing approximately A$1.60 billion, and Publishing, which adds around A$517.49 million. The company's gross profit margin has shown variability, reaching 26.83% in late 2022 but decreasing to 16.00% by mid-2026.
PE: -3.1x
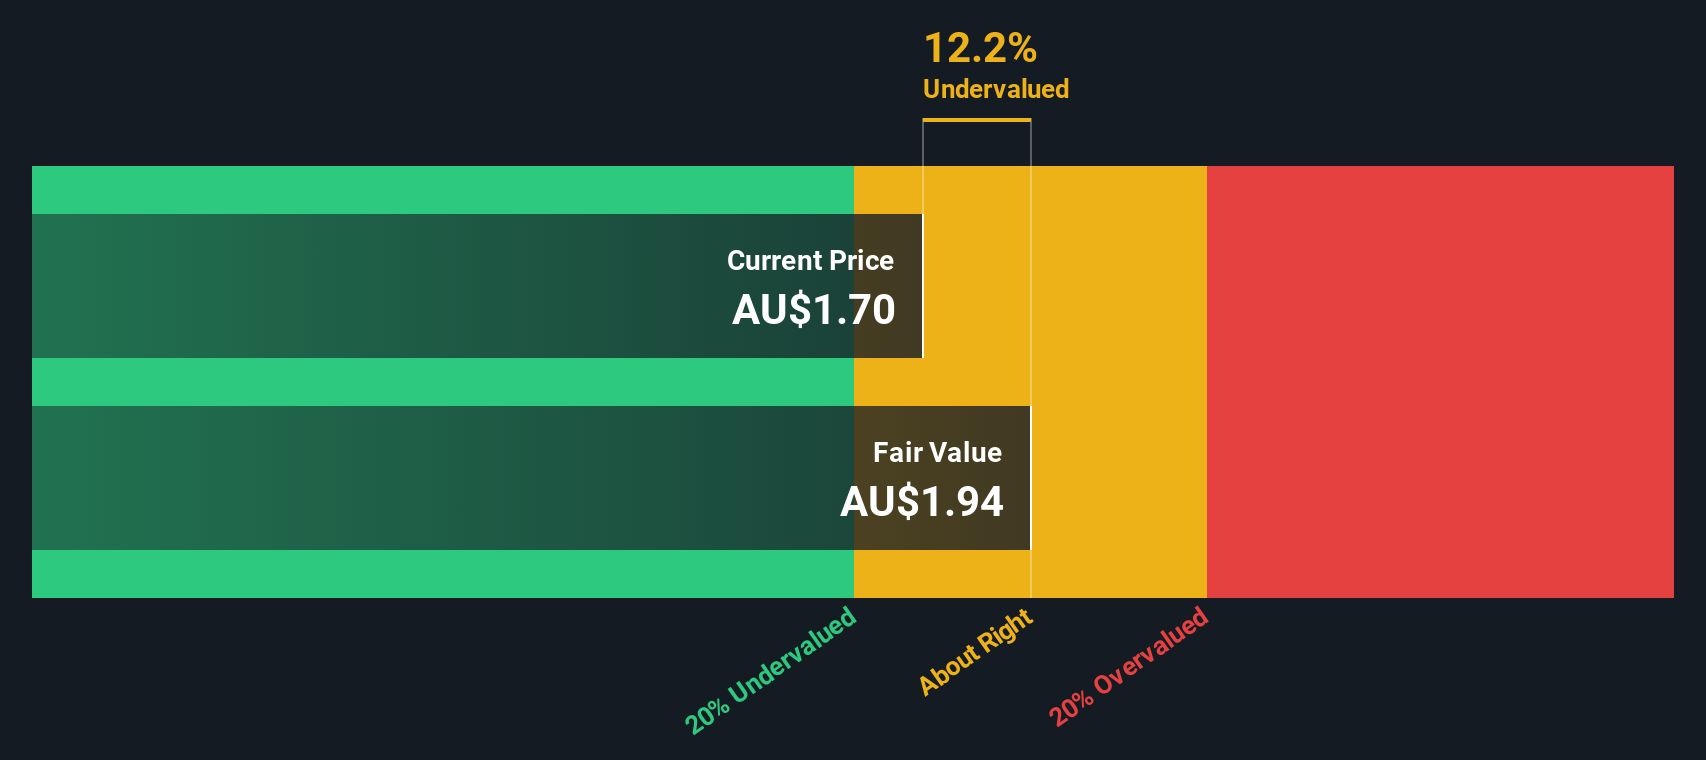
Nine Entertainment Holdings, a player in the media industry, showcases potential as an undervalued stock with impressive earnings growth, reporting A$511 million in net income for the year ending June 2026. Despite high debt levels and reliance on external borrowing, insider confidence is evident through recent share purchases. The appointment of Leigh Terry as a Non-Executive Director adds strategic depth to their leadership team. With earnings forecasted to grow significantly annually, Nine's future prospects appear promising amidst its financial challenges.
Omni Bridgeway (ASX:OBL)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Omni Bridgeway specializes in funding and providing services related to legal dispute resolution, with a market capitalization of A$1.04 billion.
Operations: Omni Bridgeway primarily generates revenue from the funding and provision of services related to legal dispute resolution, with a recent revenue figure of A$112.26 million. The company has experienced fluctuations in its net income margin, most recently recording a net income margin of 0.48%. Its cost structure includes significant costs of goods sold (COGS) and operating expenses, impacting overall profitability.
PE: 8.5x
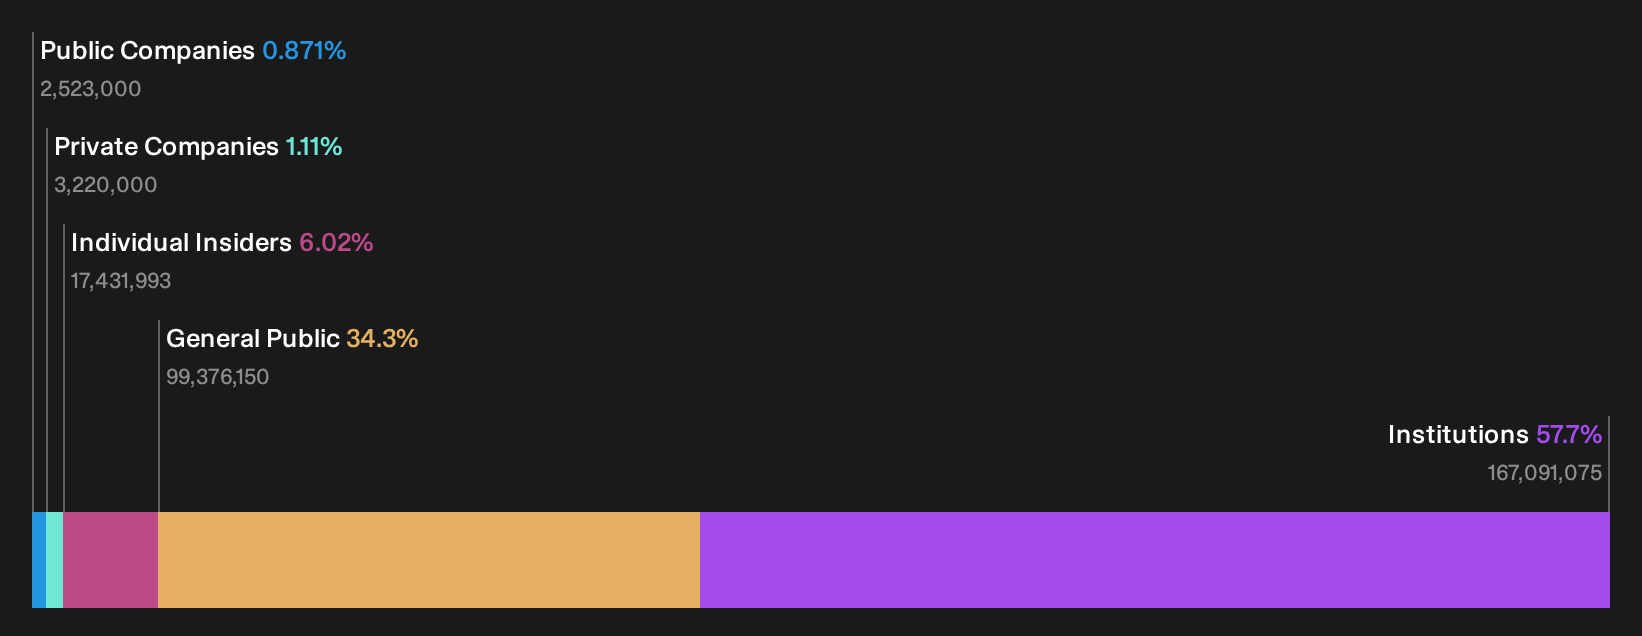
Omni Bridgeway, a company with a focus on litigation finance, presents an intriguing opportunity within the small-cap sector. Despite recent challenges like its removal from the S&P Global BMI Index in September 2026 and declining net income to A$53.7 million from A$349.8 million, insider confidence is evident as Christine Feldmanis increased their stake by 58% through purchasing 50,000 shares for approximately A$73,750 in August 2026. While profit margins dipped to 47.8%, earnings are projected to grow annually by over 34%, signaling potential for future growth amidst current financial restructuring efforts.
- Click here and access our complete valuation analysis report to understand the dynamics of Omni Bridgeway.
Assess Omni Bridgeway's past performance with our detailed historical performance reports.
China Lilang (SEHK:1234)
Simply Wall St Value Rating: ★★★★★☆
Overview: China Lilang is engaged in the manufacturing and sale of menswear and accessories, with a market capitalization of CN¥3.15 billion.
Operations: The company generates revenue primarily from the manufacturing and sale of menswear and accessories, with recent figures showing a gross profit margin of 49.00%. Operating expenses are significant, largely driven by sales and marketing costs. The net income margin has shown variability over time, recently recorded at 10.78%.
PE: 5.8x
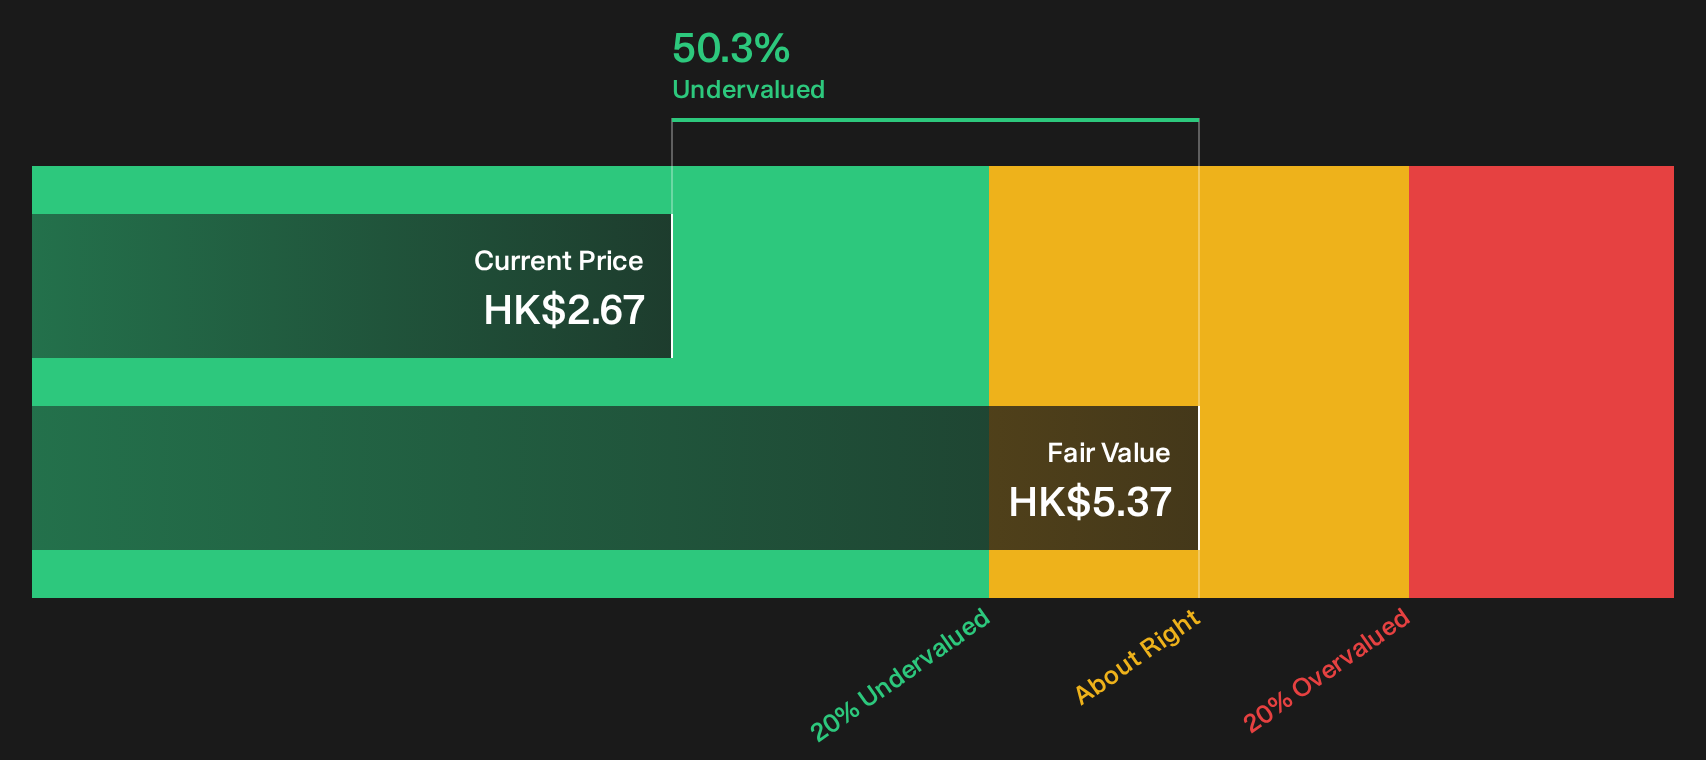
China Lilang's recent earnings call revealed sales growth to CNY 2.06 billion for H1 2026, up from CNY 1.73 billion the previous year, though net income dipped slightly to CNY 215.37 million. Despite this, insider confidence is evident with share purchases in early August 2026, indicating belief in future prospects. The company declared a special interim dividend of HKD 0.04 per share alongside an interim dividend of HKD 0.10 per share, reflecting shareholder returns despite funding through external borrowing sources. Earnings are projected to grow by over 11% annually, suggesting potential value amidst its small-cap peers.
- Unlock comprehensive insights into our analysis of China Lilang stock in this valuation report.
Examine China Lilang's past performance report to understand how it has performed in the past.
Seize The Opportunity
- Explore the 116 names from our Undervalued Global Small Caps With Insider Buying screener here.
- Hold shares in these firms? Setup your portfolio in Simply Wall St to seamlessly track your investments and receive personalized updates on your portfolio's performance.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com