
Horace Mann Educators (HMN) Faces Mixed Valuation Views, Is The Stock Undervalued?
Recent commentary on Horace Mann Educators (HMN) has focused on two themes. Analysts updated research views on the insurer, while income-focused investors reacted to its 3.11% dividend yield and multi-year pattern of dividend increases.
At a share price of US$46.29, Horace Mann Educators has seen the 90-day share price return fall 10.5%, even though the year-to-date share price return is up 2.5% and the 1-year total shareholder return of 7.9% still reflects longer term gains built over a 3-year total shareholder return of 65.7%.
Compare Horace Mann Educators with a curated 8 dividend fortresses that combines income potential with balance sheet resilience and consistent shareholder return profiles.
After a 10.5% pullback over 90 days but a 3-year total return above 65%, Horace Mann Educators now sits in an awkward middle ground. Does that recent slide justify stepping in today, or is it better to wait for a cleaner entry based on the valuation math to follow?
Most Popular Narrative: 18.1% Undervalued
On the most followed view of Horace Mann Educators, a fair value of $56.50 sits well above the recent $46.29 share price. This puts the spotlight on how the business is expected to grow into that gap using its educator focused model.
Extension of product offerings into supplemental and group benefits is now supported by 44% sales growth in Individual Supplemental & Group Benefits and higher Life sales, which indicates that this broader mix can keep shifting earnings toward higher-margin business and support core EPS.
See why 2 investors see Horace Mann Educators as 18% undervalued.
Result: Fair Value of $56.50 (UNDERVALUED)
Still, heavy reliance on public K-12 educators and pressure on investment income could both chip away at the bullish Horace Mann Educators narrative if conditions turn.
Find out about the key risks to this Horace Mann Educators narrative.
Another View: Horace Mann Educators On Earnings Multiples
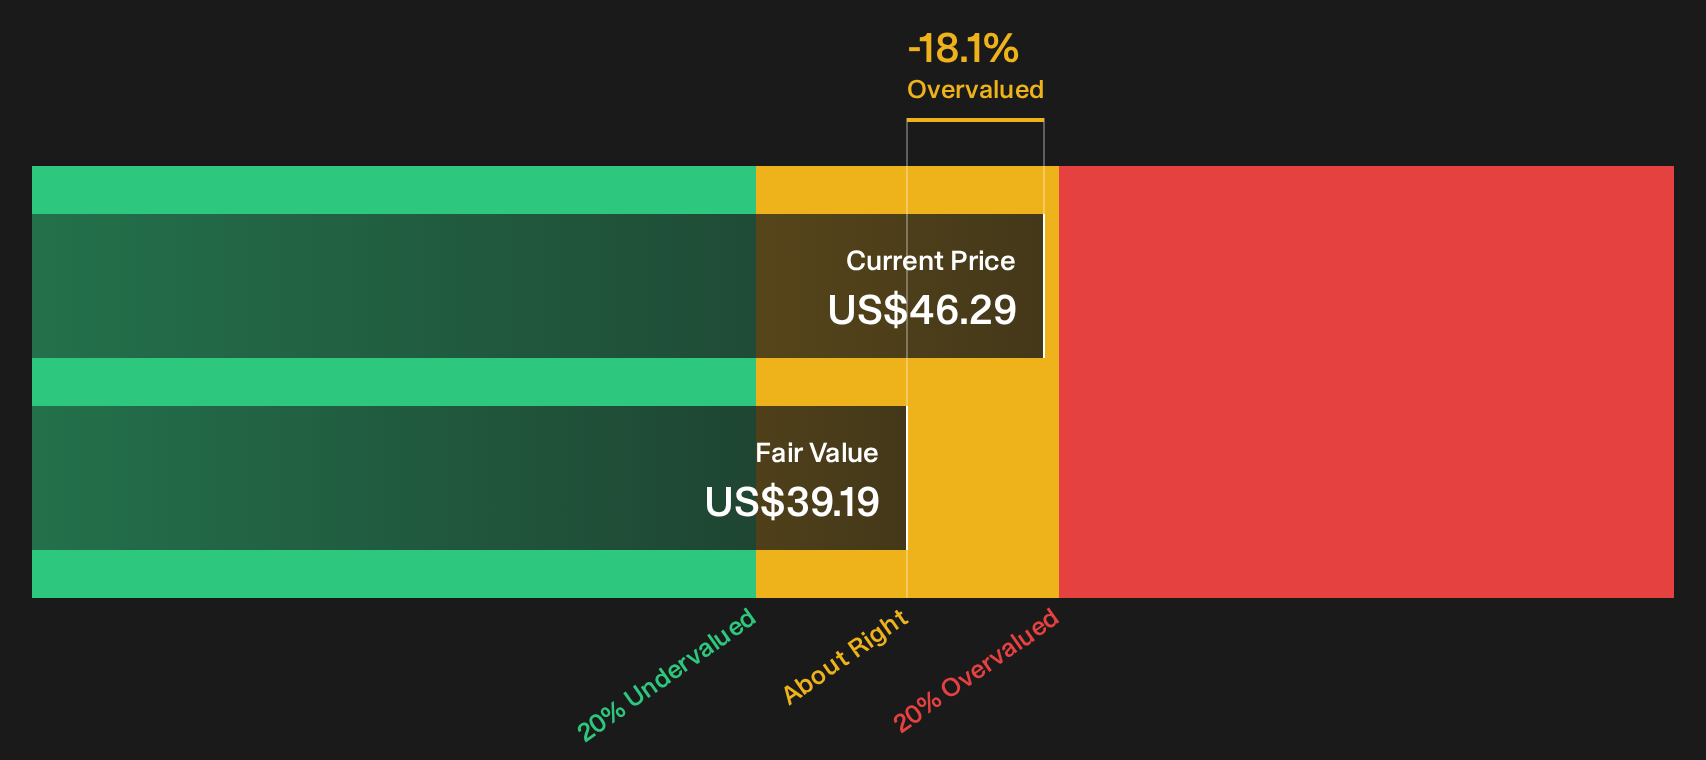
The SWS DCF model lands in a different place. On that approach, Horace Mann Educators at $46.29 trades above an estimated future cash flow value of $39.19, which screens as overvalued rather than cheap. If cash flows matter more than earnings scenarios to you, does that change the story?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed views on Horace Mann Educators are clear, with investors highlighting both potential benefits and possible risks. Act while the data is fresh and shape your own stance by weighing 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Horace Mann Educators?
Round out your research by scanning fresh opportunities through the Simply Wall St Screener, so you do not miss stocks that better fit your goals.
- Target dependable income streams by reviewing companies that feature a 8 dividend fortresses and may complement Horace Mann Educators in a yield-focused portfolio.
- Hunt for mispriced opportunities by checking a curated 35 high quality undervalued stocks that filters for quality fundamentals at potentially appealing prices.
- Strengthen capital preservation by focusing on a 32 resilient stocks with low risk scores that screens for resilient balance sheets and milder volatility profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com