
How Dividend Cut Will Impact Conagra Stock Investors
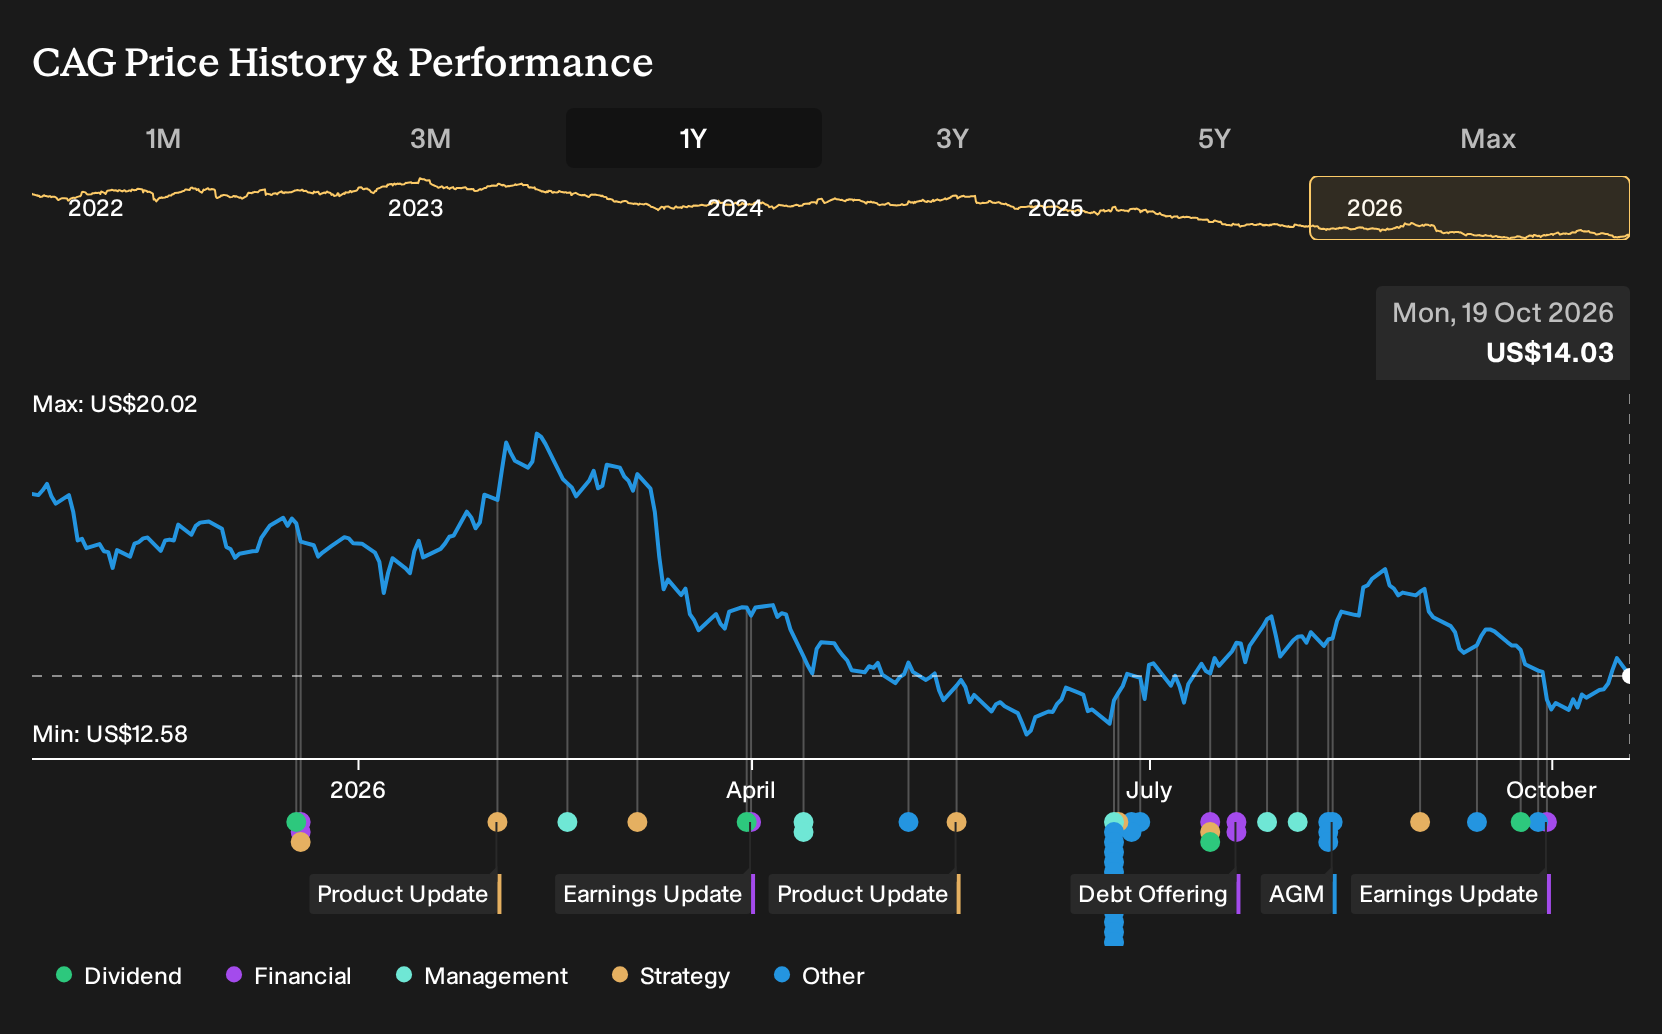
- Conagra Brands cut its dividend in half in July 2026 to free more cash for debt reduction after sluggish organic net sales and a previously high 76% payout ratio.
- The reset dividend, now aimed at a more sustainable level, highlights management’s priority to bring net leverage closer to the 3x target while sales remain under pressure.
- We will now look at how this dividend reset and debt focus could reshape the broader investment narrative around Conagra Brands today.
Compare Conagra Brands' reset payout and debt focus with other balance sheet conscious opportunities by scanning our curated list of solid balance sheet and fundamentals (25 results) now shaping the income and stability conversation.
Conagra Brands Investment Narrative Recap
To stay invested in Conagra Brands, you need to believe the reset dividend and higher reinvestment can eventually support healthier margins and a more resilient balance sheet. The near term story is about execution, not expansion. Productivity programs, supply chain upgrades and SKU clean up all need to work while organic net sales remain under pressure.
The dividend cut is unlikely to change the most immediate catalyst, which is whether Conagra Brands can stabilize volumes and margins while tariff and inflation costs are still biting. The bigger risk is leverage. Net debt of roughly 4x earnings before interest, tax, depreciation and amortization keeps interest expense and execution missteps in sharp focus.
The July 2026 decision to halve the dividend and free more cash for debt reduction is the announcement that most directly frames this setup. Management is aiming to move net leverage closer to 3x from around 3.99x, using the lower US$0.70 per share payout to release roughly US$335 million each year for balance sheet repair and reinvestment.
That rebalanced capital allocation sits alongside Project Catalyst, productivity targets above 4% of cost of goods sold and portfolio simplification as the main operational levers. Together they form the practical test for Conagra Brands over the next few years. Debt is not well covered by operating cash flow today, so progress on these projects and on cash generation is what income focused investors will likely track most closely.
Conagra Brands Forecasts Behind The Debt And Dividend Reset
Conagra Brands' reset story is not just about balance sheet repair. It also leans heavily on analyst expectations that the business shifts from a loss today to solid profitability over the next few years while revenue gently contracts rather than expanding.
Analysts in the Simply Wall St report assume Conagra Brands' revenue will decline by about 1.0% each year over the next 3 years. That puts more weight on efficiency, pricing discipline and mix than on chasing top line growth. The trade off is clear for income investors: the company is trying to make each dollar of sales more profitable instead of pushing for a bigger revenue base.
On earnings, the swing expected is large. The consensus view has Conagra Brands moving from an earnings loss of about US$1.9b today to earnings of roughly US$1.1b by 2029, on revenue of around US$10.9b. That shift lines up with an assumed profit margin improvement from a loss making position near 17% in the red to a positive margin of 10.4% in 3 years. For a dividend that was cut to free cash, this kind of margin rebuild is what would need to underpin any future flexibility on payouts.
Those same analyst estimates imply that by 2029 the shares would trade at a P/E of about 7.2x on the US$1.1b of earnings, compared with a current food sector multiple cited at 18.7x in the report. That gap only matters for you if you think the margin rebuild, leverage reduction and earnings path described are realistic. If you see more risk to execution, or a slower pace on cost savings and portfolio clean up, then a lower multiple and different earnings path might feel more appropriate.
Conagra Brands' narrative projects revenue of about US$10.9b and earnings of roughly US$1.1b by 2029, based on analyst forecasts that layer a yearly 1.0% revenue decline onto an earnings swing from a loss of about US$1.9b today, an implied earnings increase of roughly US$3.0b over that period.
Uncover why Conagra Brands' fair value indicates a value that is roughly in line with its current price.
Exploring Other Perspectives
One alternate view around Conagra Brands leans hard into the dividend reset as a future earnings catalyst. The most optimistic analysts were penciling in revenue of about US$11.5b and earnings close to US$1.2b by 2029 before this cut, so their story is far more upbeat. Use that spread to explore how differently reasonable people can read the same business and how this latest news could shift those scripts.
Explore 7 other Conagra Brands fair value estimates, including one that suggests potential upside of as much as 254% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own analysis.
- A helpful starting point for your Conagra Brands research is our analysis highlighting 3 key rewards and 2 important warning signs that could inform your investment decision.
- See our latest analysis for Conagra Brands. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easier to review Conagra Brands' overall financial position at a glance.
Looking For More Investment Ideas Beyond Conagra Brands?
If the Conagra Brands story has sharpened your focus on balance sheets, income durability and valuation gaps, it can help to line it up against other listed businesses using the Simply Wall St Screener.
- For investors who want income with a buffer, consider higher yielding companies that our tools flag as more resilient by reviewing 8 dividend fortresses that could complement or contrast with Conagra Brands.
- If capital protection ranks higher on your list than rapid gains, survey stocks that show stronger financial resilience and lower risk scores using the 32 resilient stocks with low risk scores available in the screener.
- When you want quality without the crowd, compare Conagra Brands with a 20 high quality undiscovered gems that currently fly under most radars yet screen well on core fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com