
Dear Meta Stock Fans, Mark Your Calendar for October 21
Meta Platforms (META) will release its third-quarter earnings after the market closes on Wednesday, October 21. The event matters for Meta fans, as it could set the stock’s future trajectory.
While Meta’s resilient ad revenue will continue to support top- and bottom-line growth, higher capital expenditures could continue to limit upside potential in Meta stock. Thus, any signs of accelerating growth could boost Meta stock.
Meta’s capital expenditures are soaring to support its artificial intelligence (AI) ambitions. In the second quarter, Meta reported $31.1 billion in capital expenditures. A substantial portion of this investment went toward servers, data centers, and networking infrastructure needed to develop and expand its AI capabilities.
These investments could help Meta improve its advertising technology, strengthen its competitive position, and develop new AI-powered products over time. However, these investments will likely weigh on Meta’s bottom line in the short term.
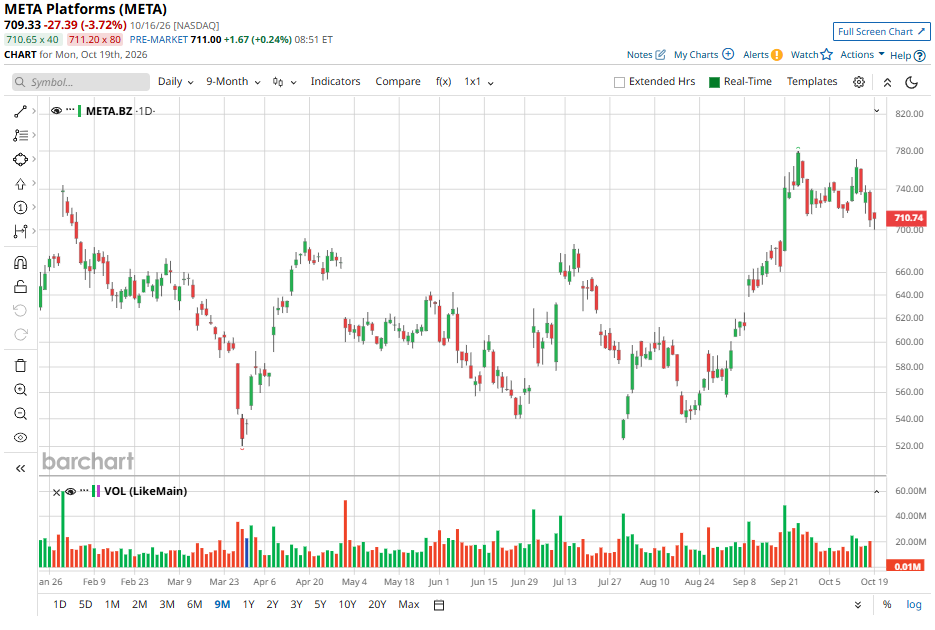
Meta Q3 Outlook
Meta Platforms is expected to deliver another quarter of solid revenue growth, supported by strong advertising demand and the growing impact of AI across its platforms. However, while the company’s AI investments are improving user engagement and advertising performance, rising capital expenditure to strengthen its AI capabilities could weigh on third-quarter earnings.
Meta expects Q3 revenue to be between $61 billion and $64 billion, with the midpoint of $62.5 billion representing about 22% year-over-year growth. This outlook reflects the continued strength of its advertising business, the company’s main revenue source.
Notably, Meta’s Family of Apps advertising revenue was $59.4 billion in Q2, up 27% from a year earlier. Higher ad impressions and stronger pricing drove the increase, highlighting continued demand for advertising across Facebook, Instagram, and its other platforms.
During the quarter, ad impressions across Meta’s services rose 14% year over year, driven by growth in users and engagement, as well as improved ad placement. At the same time, the average price per ad rose 12%, benefiting from better ad performance. These trends suggest that Meta’s advertising business remains in good shape for Q3 and beyond.
Meta has invested heavily in AI to improve content recommendations and make its platforms more engaging. These efforts are already showing results. In Q2, time spent on Instagram rose double digits year over year, largely due to improvements in Feed and Reels recommendations. Facebook also saw stronger video engagement, with worldwide video watch time rising 9%, while growth exceeded 10% in the U.S. and Canada. These trends are likely to continue.
Meta is seeing growing demand for its AI-powered advertising tools. Its Advantage+ suite has surpassed an annual revenue run rate of $75 billion, reflecting the increasing use of automation to improve advertising campaigns. The number will further increase in the quarters ahead.
Meta’s generative AI tools are also gaining traction, with more than 9 million small businesses using at least one of its AI creative tools. The adoption is likely to increase, supporting Meta’s growth.
While Meta is expected to deliver solid top-line growth, its bottom line could remain under pressure. Analysts expect Meta to report earnings of $6.54 per share, down approximately 9.8% from the same period last year. The projected decline reflects its continued investment in expanding AI capabilities and infrastructure.
The Bottom Line for Meta’s Q3
Overall, Meta’s Q3 outlook remains encouraging on the revenue front, with its advertising business benefiting from stronger engagement, better ad performance, and wider adoption of AI-powered tools. These factors could help the company maintain solid growth and strengthen its competitive position in digital advertising. However, its investments in AI capabilities will likely weigh on margins in the short term.
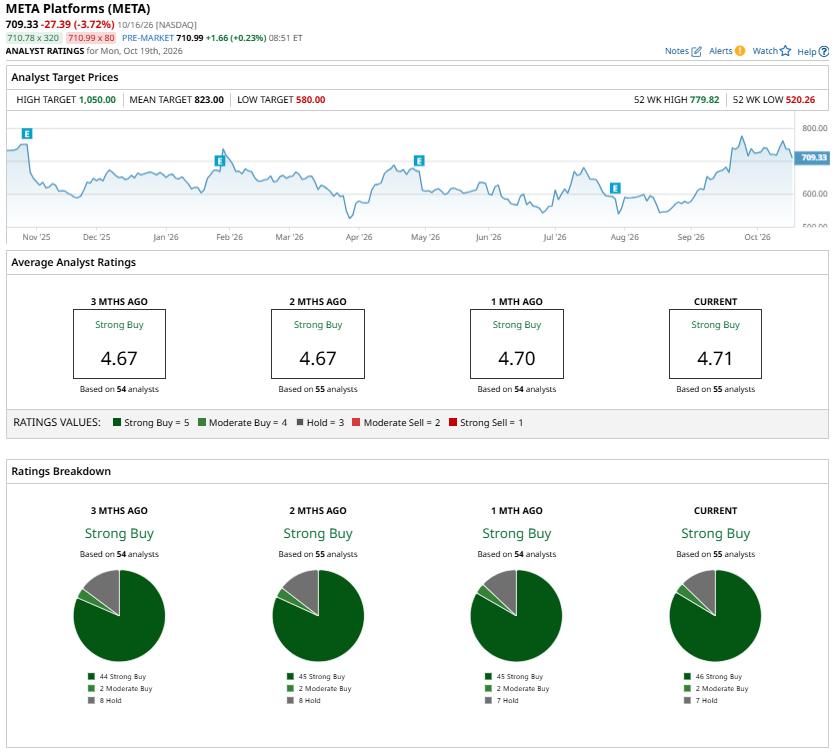
Despite near-term margin pressure, Wall Street’s “Strong Buy” consensus rating reflects continued confidence in Meta’s long-term potential.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.