
Basilea Pharmaceutica (SWX:BSLN) Heads To IDWeek 2026, Is It Still Undervalued?
Pipeline spotlight at IDWeek 2026
Basilea Pharmaceutica (SWX:BSLN) is back on investor radars after announcing that new data on antifungal and antibiotic candidates will be presented at IDWeek 2026, including pediatric results and pathogen specific findings.
Recent trading backs up the renewed interest in Basilea Pharmaceutica, with a 1 day share price return of 3.05% and a 90 day share price return of 29.01%, while the 1 year total shareholder return of 39.09% points to momentum that extends beyond this IDWeek 2026 catalyst.
Scan other infection fighters showing similar momentum and R&D focus with our hand picked 122 healthcare AI stocks aligned with Basilea Pharmaceutica's IDWeek 2026 spotlight.
After a 39.09% 1 year total return and fresh excitement around IDWeek 2026 data, Basilea Pharmaceutica now forces a choice. Investors must decide whether to lean into the move or wait for a calmer entry once the subsequent numbers are available.
Most Popular Narrative: 37% Undervalued
On the most followed narrative, Basilea Pharmaceutica screens as undervalued, with a fair value of CHF107.78 set against the last close at CHF67.60. That gap reflects a view that the anti infective portfolio and late stage programs carry more weight than the current share price implies.
The flexible, partnership-based commercialization model enables Basilea to rapidly scale new assets, capture global stewardship initiatives targeting drug-resistant "superbug" threats, and maintain disciplined cost structure, supporting margin expansion and stronger long-term free cash flow and earnings.
See why 5 investors see Basilea Pharmaceutica as 37% undervalued.
Result: Fair Value of CHF107.78 (UNDERVALUED)
Still, this bullish Basilea Pharmaceutica narrative collides with two hard risks: looming Cresemba exclusivity loss after 2027 and heavy dependence on a handful of late stage assets.
Find out about the key risks to this Basilea Pharmaceutica narrative.
Another View: Basilea Pharmaceutica Through A Cash Flow Lens
The analyst narrative flags Basilea Pharmaceutica as undervalued at CHF107.78 fair value, yet the SWS DCF model paints a cooler picture. On that cash flow view, the shares at CHF67.60 sit above an estimate of CHF62.22, which frames the stock as slightly overvalued instead.
That gap leaves investors weighing two different signals. One story leans on earnings multiples and analyst targets, the other on projected cash generation. This raises a practical question: which toolkit is more useful for a business facing Cresemba expiry and a concentrated pipeline?
Look into how the SWS DCF model arrives at its fair value.
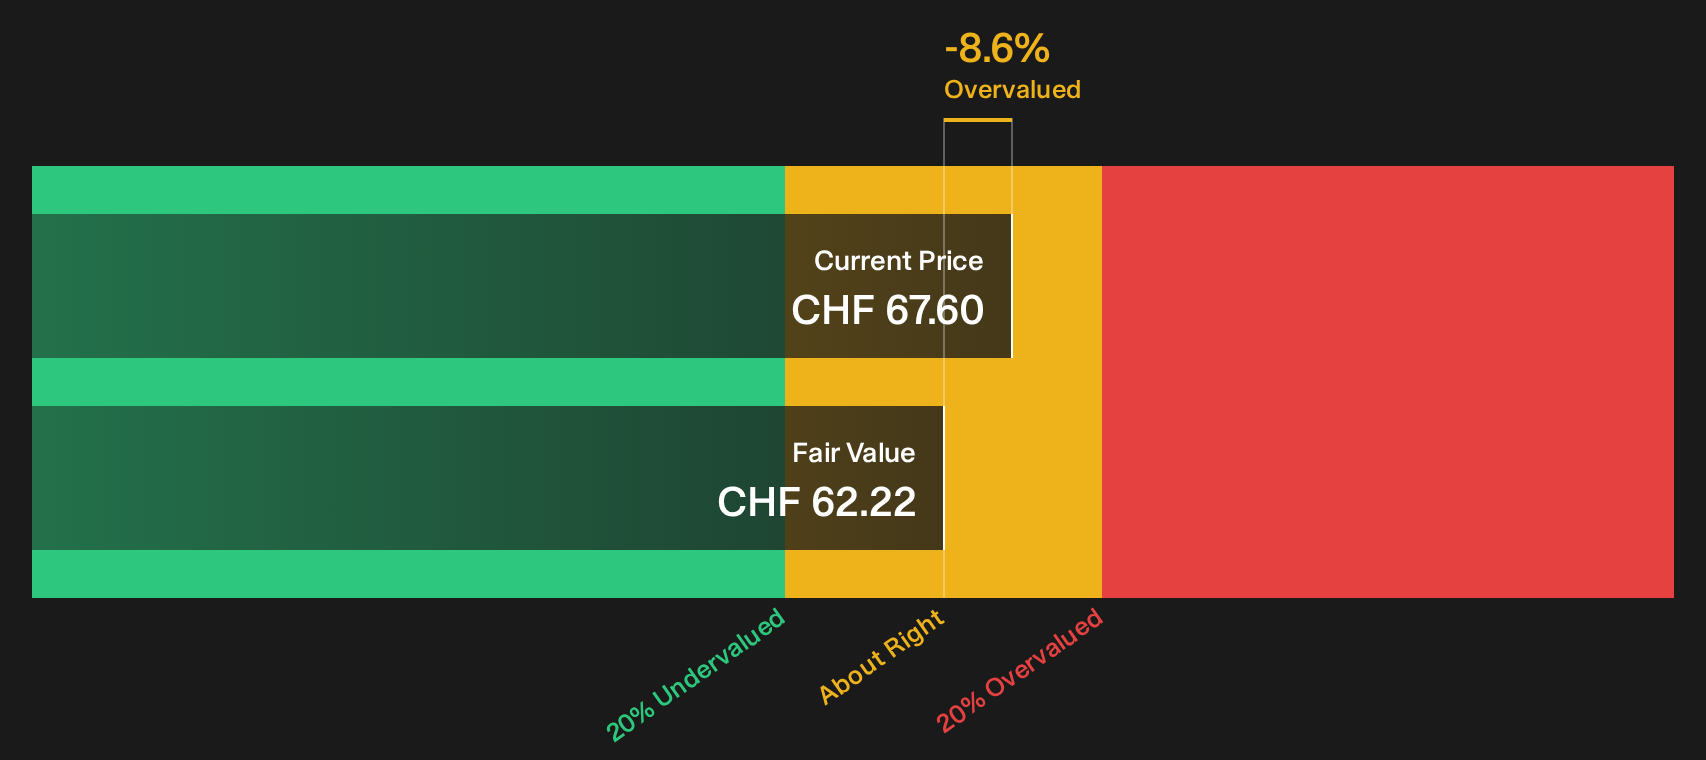
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Basilea Pharmaceutica for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 198 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Basilea Pharmaceutica so far, right, with enthusiasm around value and pipeline set against clear risk flags that investors keep circling back to.
You do not need to wait for the next headline to form a view. Move quickly through the data, pressure test both sides, and weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Basilea Pharmaceutica?
If you stop with Basilea Pharmaceutica, you miss the wider opportunity set. Apply the same disciplined mindset across other ideas and let the data guide your analysis.
- Target steady compounding by scanning a diversified pool of companies with strong fundamentals through our 230 resilient stocks with low risk scores.
- Look for potentially mispriced opportunities by filtering for businesses that pair quality with attractive pricing using the 198 high quality undervalued stocks.
- Prioritise financial resilience and funding strength by focusing on companies highlighted in the list of solid balance sheet and fundamentals (202 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com