
How Investors May Respond To Akeso Stock As New Cancer Trials Begin
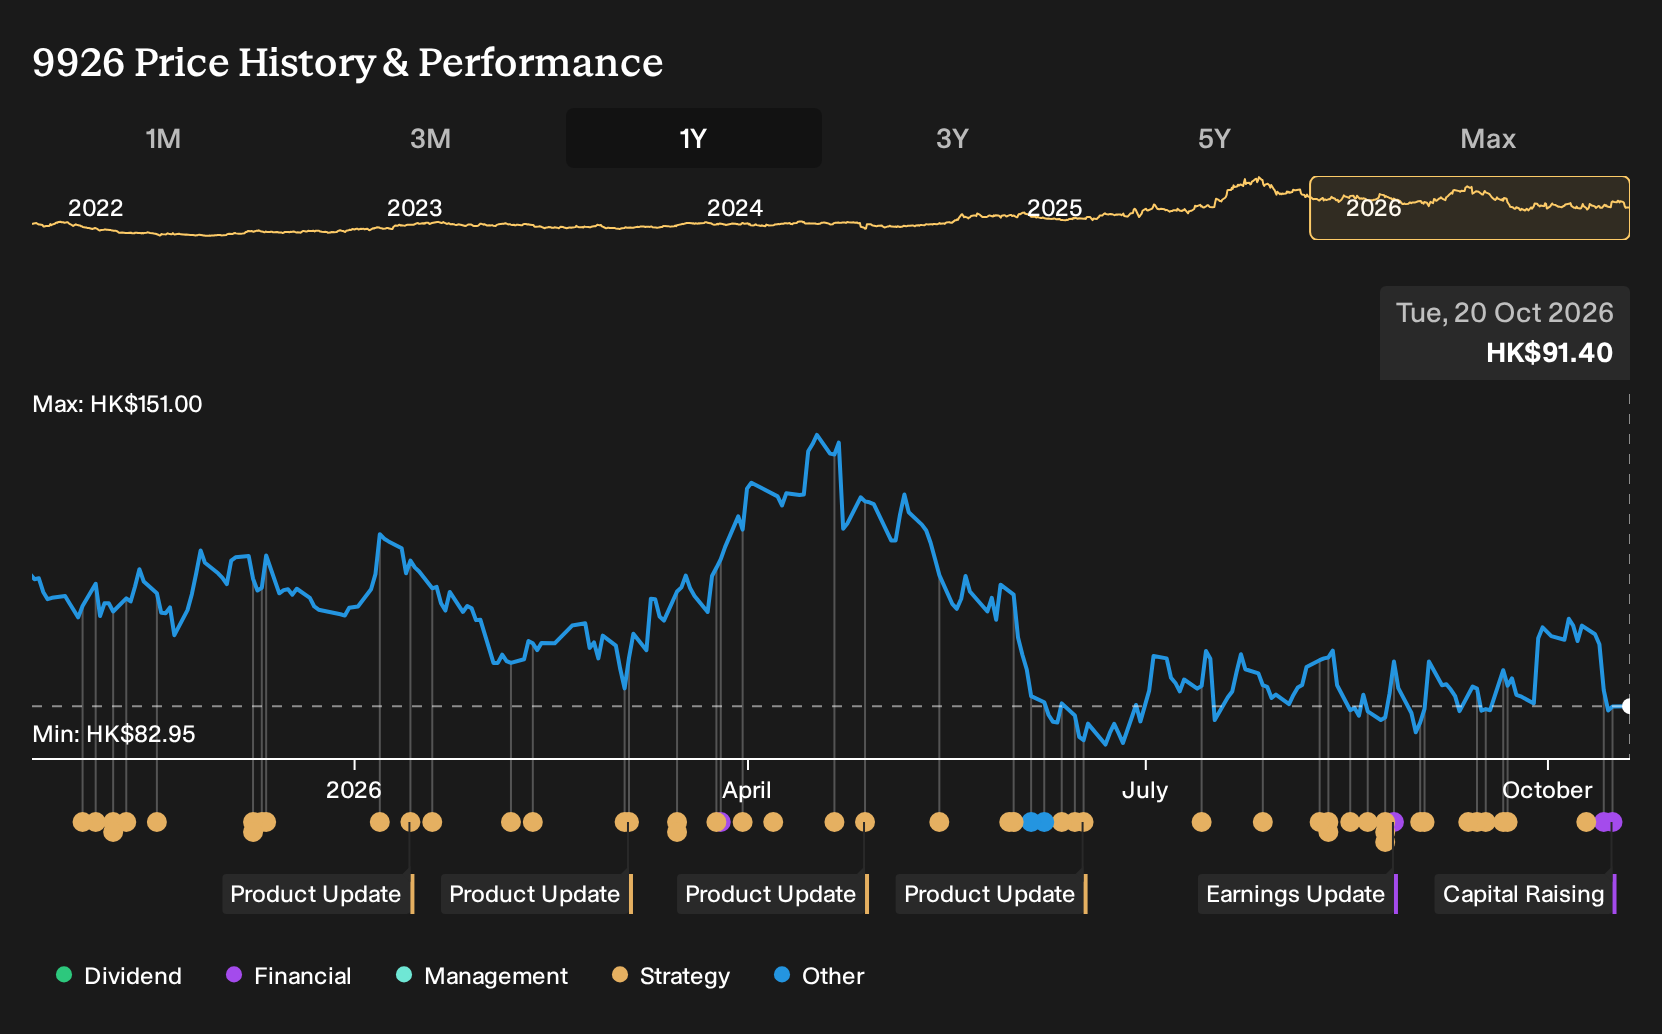
- Akeso announced a global Phase II trial of ivonescimab in advanced clear cell renal cell carcinoma and dosed the first patient in a Phase III perioperative colon cancer study of cadonilimab, while also completing a HK$1.96b follow on equity raise in October 2026.
- The cluster of late stage trials built around Akeso's bispecific antibodies, funded by fresh equity capital, highlights rising execution demands across clinical development, manufacturing, and future commercialization.
- We will now look at how Akeso's new late stage bispecific trials might reshape the investment narrative around its R&D led growth.
Akeso Investment Narrative Recap
To own Akeso, you need to believe its bispecific antibody platform can support a shift from loss making R&D to a broader, durable oncology franchise. The key near term swing factor is execution on late stage trials for cadonilimab and ivonescimab, plus NRDL driven access. This recent trial cluster raises the operational bar but does not by itself change that core thesis.
The biggest immediate risk still sits in concentration on a few lead assets, layered on top of ongoing operating and EBITDA losses in 2024. Expanding into earlier stage and perioperative settings increases trial complexity, so timelines, regulatory feedback, and any safety or efficacy surprises remain the pressure points to watch.
The new international Phase II study of ivonescimab in advanced clear cell renal cell carcinoma, including combinations with cadonilimab, is the clearest operational link to the current news. It puts Akeso’s two flagship bispecifics head to head against an established nivolumab plus ipilimumab standard, which turns trial execution and data quality into direct commercial and partnering catalysts.
That study also concentrates risk, since more clinical and commercial expectations now rest on a relatively narrow portfolio. Success could support broader use cases and reinforce the Summit collaboration, while setbacks would intensify concerns about dependence on a few products and the pressure that R&D and commercialization spending place on a business still reporting losses.
Akeso's narrative projects CN¥12.0b revenue and CN¥3.2b earnings by 2029. Analysts are assuming revenue will grow by 51.4% annually, and that would mean earnings moving from a loss of CN¥967.2m today to CN¥3.2b, which is an increase of roughly CN¥4.2b.
Uncover why Akeso's fair value indicates a 69% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
Price pressure is the big swing factor that bearish analysts focus on for Akeso. Before this news, the lowest forecasts only had 2029 earnings at about CN¥335.1m on CN¥10.1b of revenue. That is a far more cautious story than consensus. Use this new trial and equity raise to consider which narrative you lean toward.
Explore 3 other Akeso fair value estimates, including one that suggests it could be worth just HK$104.19.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Akeso research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Akeso. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Akeso's overall financial health at a glance.
Looking For More Investment Ideas Beyond Akeso?
Once you have a handle on Akeso, it can help to set it alongside a wider watchlist so you can compare quality, risk, and income potential across the market.
- For investors hunting for future breakouts at lower share prices, scan a focused group of 131 elite penny stocks with strong financials that already show stronger fundamentals than the typical microcap.
- If value and balance sheet strength matter most to you, widen your research with a 198 high quality undervalued stocks that combine healthier cash flows with more resilient financial positions.
- Income focused investors can round out their view by screening for 223 dividend fortresses that aim to pair higher yields with more durable business models.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com