
First Resources (SGX:EB5) Reassures On Fire Risks, But Is The Valuation Now A Bargain
First Resources (SGX:EB5) has moved back into focus after management addressed investor concerns around recent forest and peatland fires in Indonesia, stating that the haze-related disruption is not expected to be financially material.
The reassurance around fire related risks comes after a sharp pullback in First Resources’ share price, which fell 4.83% in the last session and is down 26.23% over the past month. However, the year to date share price return is 79.81% and the 1 year total shareholder return is 126.37%, pointing to strong longer term momentum despite the recent slide.
Compare First Resources’ haze related reset with other agricultural producers under pressure and see which ones screen well on balance sheet strength and fundamentals using our curated list of solid balance sheet and fundamentals (202 results) today.
After a 26% slide in a month, yet with a 35% gap to analyst targets and a much larger intrinsic value discount, First Resources now sits at a crossroads between a bargain thesis and fire risk caution. Which side does the valuation support?
Preferred P/E of 10.3x: Is it justified?
On simple earnings maths, First Resources trades on a P/E of 10.3x, which screens as slightly expensive against some benchmarks but cheaper than others. The last close at S$3.74 sits below analysts’ average price target of S$5.07 and below the SWS DCF estimate of S$15.10, so the market is clearly pricing this palm oil producer more cautiously than those reference points.
The P/E ratio compares what investors pay today for each dollar of annual earnings. For a group like First Resources, with plantation and downstream processing operations, that figure reflects how the market views its profit resilience, commodity exposure, and execution across its refining and biodiesel activities.
Relative signals pull in different directions. The stock is described as expensive versus its estimated fair P/E of 9.6x, which points to some premium on near term earnings compared to what the fair ratio model suggests the multiple could revert toward. It is also called expensive versus a peer average P/E of 9.2x, so investors are paying more than for similar sized comparables. Yet compared to the broader Asian Food industry P/E of 14.6x, First Resources trades on a clear discount, which implies the broader sector carries richer earnings expectations than this specific counter.
Explore the SWS fair ratio for First Resources.
Result: Price-to-Earnings of 10.3x (ABOUT RIGHT)
Still, the recent haze related disruption and any prolonged weakness in palm product pricing could challenge the bargain argument for First Resources and limit a quick rerating.
Find out about the key risks to this First Resources narrative.
Another View on First Resources' value
The P/E scorecard paints First Resources as roughly fairly priced on earnings, but the SWS DCF model tells a very different story. At S$3.74 against an estimated future cash flow value of S$15.10, the stock screens as heavily undervalued. Is this a genuine mispricing or simply a model running too hot?
Look into how the SWS DCF model arrives at its fair value.
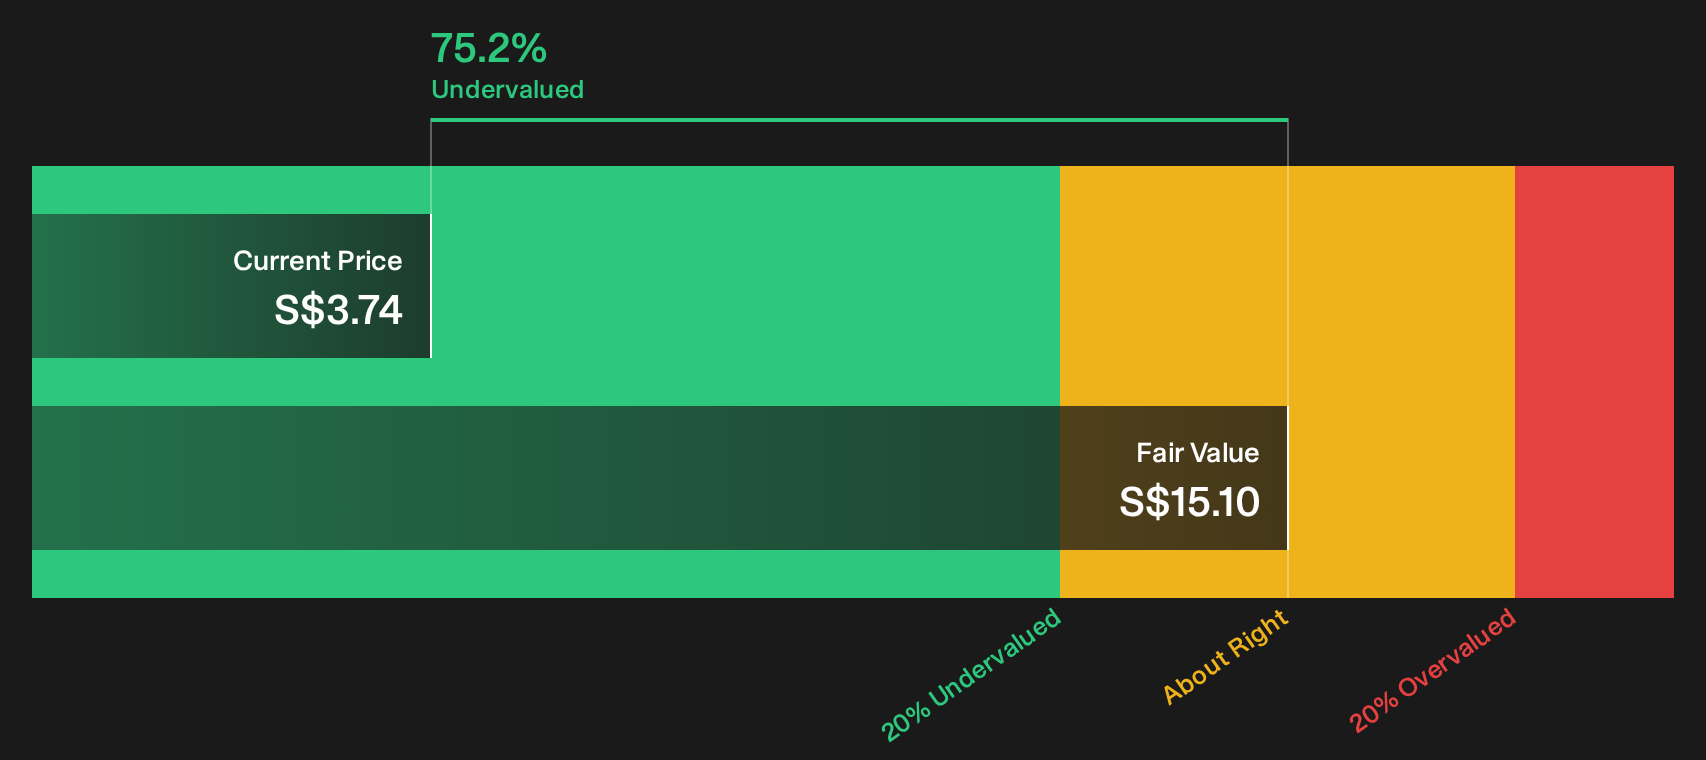
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 198 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on First Resources' valuation and risk profile do not need to leave you on the fence. Move quickly, check the underlying data, and weigh both the concerns and potential upside through the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond First Resources?
Do not stop at First Resources. Use the Simply Wall Street Screener to uncover fresh ideas that match your risk tolerance, income goals, and value preferences.
- Target potential mispricings in quality companies by running a focused search through our 198 high quality undervalued stocks.
- Build a more dependable income stream by zeroing in on higher yielding opportunities using the 223 dividend fortresses.
- Dial down portfolio stress and focus on stability by filtering for resilient opportunities with the 230 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com