
Why Navitas Petroleum Limited Partnership (TASE:NVPT) Moved Today
Recent attention on Navitas Petroleum Limited Partnership (TASE:NVPT) stems from Argentina’s move to take the Sea Lion project dispute to an international tribunal. This development raises fresh questions about how secure the partnership’s future income streams really are.
The latest move by Argentina lands on a stock that has already seen sharp swings. Navitas Petroleum Limited Partnership’s share price return is up 12.71% over the past week and 3.73% in a single day, yet it remains down 2.80% over 30 days and 4.21% over 90 days. The 1-year total shareholder return of 16.27% sits on top of very large 3-year and 5-year total shareholder returns. Shorter term momentum appears to be rebuilding after a cooler patch as investors reassess legal and project risks against that premium valuation backdrop.
Compare how markets are pricing legal and project risk by scanning the 230 resilient stocks with low risk scores that may offer steadier exposure than Navitas Petroleum Limited Partnership if tribunal headlines escalate.
Navitas Petroleum’s premium price tag and fresh legal overhang now collide. After this latest jump, does the balance of risk and potential reward still lean toward new buyers, once you line it up against its earnings?
Preferred P/E of 16.9x: Is it justified for Navitas Petroleum?
Valuation now hinges on what you are willing to pay for each shekel of earnings. At a last close of ₪125, Navitas Petroleum Limited Partnership trades on a P/E of 16.9x, which is lower than its direct peer group on this metric but higher than the wider Asian oil and gas sector.
The P/E ratio simply compares the current share price to earnings per unit. For a producer like Navitas Petroleum, it is a quick way to see how much of today’s market value is linked to profits that already exist, rather than hopes tied to undeveloped fields and new wells.
Against its immediate peer average of 21.7x, a 16.9x P/E implies investors are not paying the highest premium in the group for current earnings. That discount sits beside several flags, including earnings that have only recently moved into profit, a high level of non cash earnings, debt that is not well covered by operating cash flow and a dividend yield of 3.09% that is not well covered by free cash flows.
In comparison with the broader Asian oil and gas industry, where the average P/E is 11.4x, the higher multiple suggests the market is attaching a stronger value to Navitas Petroleum’s profit stream than to the typical regional producer. That gap becomes more important when the SWS DCF model indicates the units trade above an estimated future cash flow value of ₪62.6, which points to a rich price tag if cash generation or tribunal risks disappoint.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 16.9x (OVERVALUED)
Still, tribunal uncertainty around Sea Lion and the reliance on a premium P/E for Navitas Petroleum leave the story vulnerable if cash flows or rulings disappoint.
Find out about the key risks to this Navitas Petroleum Limited Partnership narrative.
Another View: What Our DCF Model Says About Navitas Petroleum
The P/E story is only half of it. Our DCF model, which estimates the value of future cash flows, points to a figure of ₪62.6 per unit compared with Navitas Petroleum’s last close at ₪125. That gap frames the stock as overvalued on this lens and raises the question of how much tribunal and cash flow risk is already baked in.
Look into how the SWS DCF model arrives at its fair value.
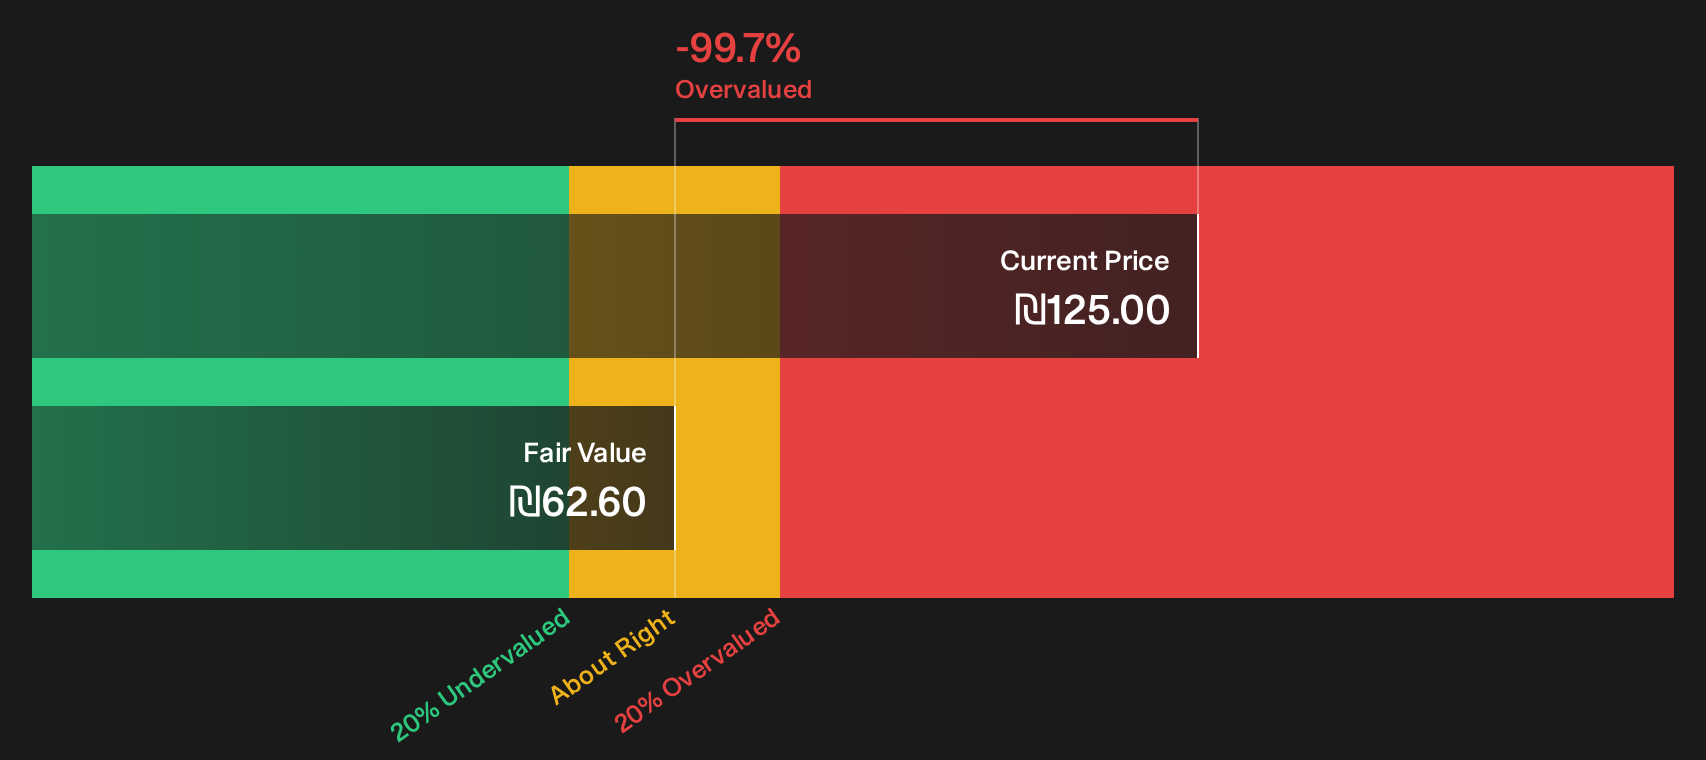
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Navitas Petroleum Limited Partnership for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 198 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of rich valuation and tribunal risk around Navitas Petroleum leaves you on the fence, move quickly to test the data against your own tolerance for swings and income. To weigh both sides in one place, review the 1 key reward and 3 important warning signs
Looking for more ideas beyond Navitas Petroleum?
If Navitas Petroleum leaves you questioning concentration risk, broaden your watchlist with other candidates that fit clearer income, quality and volatility preferences.
- Target resilience by scanning a 230 resilient stocks with low risk scores that can help you focus on businesses with steadier risk profiles when headlines turn unpredictable.
- Hunt for value by reviewing a 198 high quality undervalued stocks that highlights companies where price and fundamentals may line up more attractively than crowded favourites.
- Strengthen your income stream by assessing a 223 dividend fortresses that surfaces higher yield opportunities with the potential for more reliable payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com