
Axfood (OM:AXFO) Could Be 6% Overvalued On City Gross Turnaround Focus
Axfood (OM:AXFO) is back in focus after fresh debate that the share trades below its estimated intrinsic value based on projected cash flows, just as the City Gross turnaround moves toward targeted profitability in the second half of 2026.
Recent trading suggests interest is rebuilding around Axfood. The share price is up 10.06% on a 1 month share price return and 17.53% on a 3 month share price return, while the 5 year total shareholder return of 49.53% points to a steadier long run story despite a modest 1 year total shareholder return decline of 2.01% and year to date share price weakness of 5.20%. Investors are weighing the City Gross turnaround against debate about intrinsic value.
Compare Axfood's setup with a curated 198 high quality undervalued stocks that also shows a gap between market price and estimated intrinsic value based on projected cash flows.
After a sharp rebound in Axfood’s share price, but with a wide gap to estimated intrinsic value based on projected cash flows, the real focus now is on where fair value actually clusters within that range of outcomes.
Most Popular Narrative: 6% Overvalued
Against Axfood's last close of SEK273.50, the most followed valuation narrative centers on a fair value of SEK258.57, which points to a modest premium that investors are currently paying for the stock.
The company's ongoing investments in supply chain automation and logistics (for example, the fully operational Bålsta robotic warehouse and planned capacity expansion in southern Sweden by 2030) are expected to continue driving operating cost reductions and margin improvements, with efficiency gains gradually increasing towards the upper end of targeted savings, positively impacting net margins and long-term earnings growth.
See why 26 investors see Axfood as 6% overvalued.
Result: Fair Value of SEK258.57 (OVERVALUED)
Still, the Axfood narrative could unravel if Swedish grocery price competition keeps pressuring margins or if the City Gross turnaround drags beyond the planned 2026 timeline.
Find out about the key risks to this Axfood narrative.
Another View: Multiples Put Axfood In A Different Light
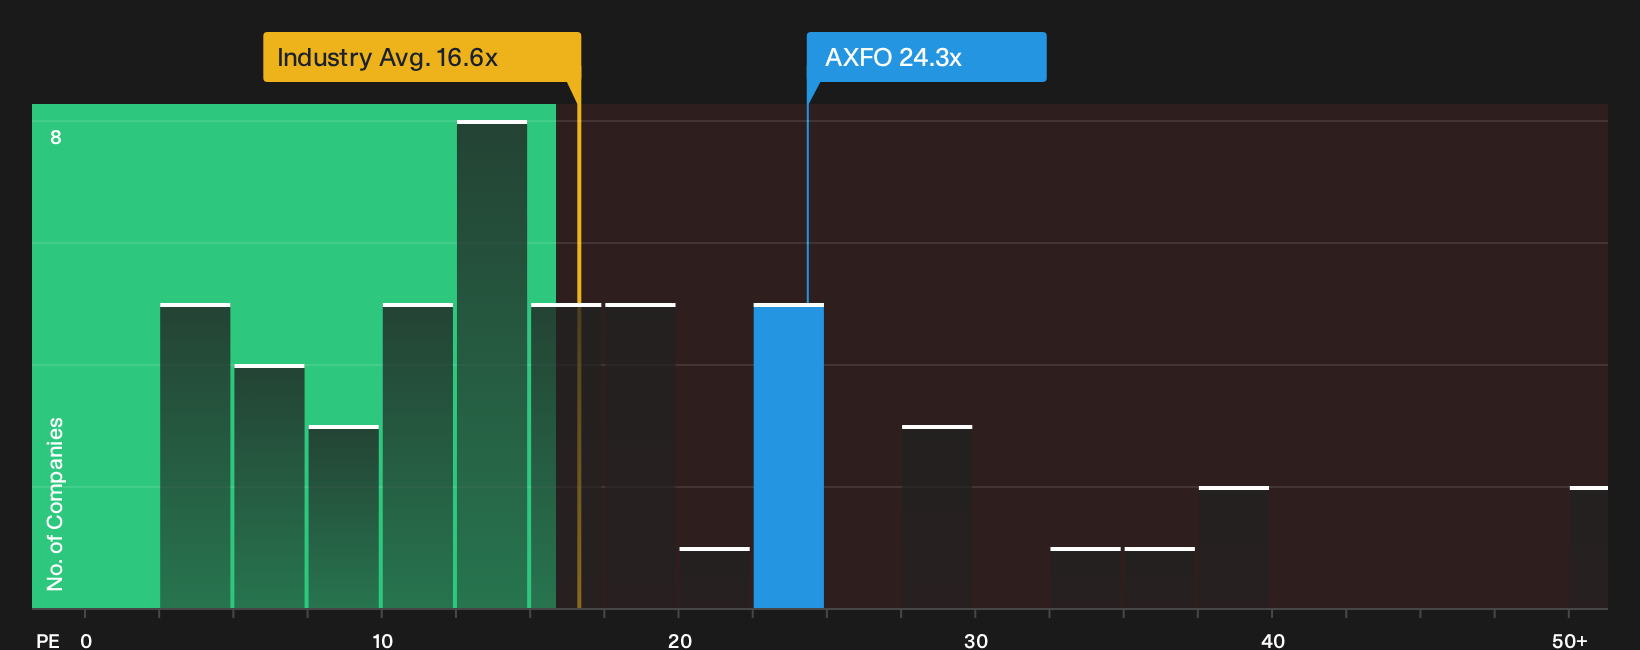
Flip the lens and the picture changes. On a P/E of 24.3x, Axfood trades above both the European Consumer Retailing group on 16.4x and its peer average on 21.1x, even though the fair ratio sits higher at 27.1x. Is that premium comfort or valuation risk?
To see how those relative valuation gaps stack up in practice, and what they might mean if the market moves closer to the fair ratio over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With Axfood's valuation narrative pulling in different directions, the real edge comes from checking the underlying numbers yourself and deciding where you stand. If you want to see the specific positives that current holders are focusing on, start with the 4 key rewards.
Looking for more Axfood style investment ideas?
If you stop with Axfood, you only see one angle. Broaden your watchlist with other potential opportunities that match your risk, income, and quality preferences.
- Target resilient balance sheets by scanning a curated list of solid balance sheet and fundamentals (202 results) that filters for financial strength and fundamental support.
- Hunt for mispriced quality by reviewing a focused 198 high quality undervalued stocks that highlights companies trading below estimated intrinsic value.
- Build a dependable income stream by checking a specialised 223 dividend fortresses that concentrates on higher yielding dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com