
How DCF Undervaluation Could Impact Sanwa Holdings Stock Investors
- Sanwa Holdings has come back into focus after a fresh Discounted Cash Flow review indicated the company’s calculated intrinsic value sits meaningfully above its current market valuation, using moderate free cash flow growth assumptions rather than aggressive expansion cases.
- The key takeaway for investors is that Sanwa Holdings’ cash generation profile and long term shareholder rewards are being weighed directly against present pricing. This raises questions about whether the market is fully reflecting the firm’s underlying cash flow capacity.
- We will now look at how Sanwa Holdings’ investment narrative could shift as investors weigh DCF implied value against current pricing.
Compare Sanwa Holdings' valuation signal with a curated list of other cash rich opportunities by scanning the 13 high quality undervalued stocks that share a similar focus on free cash flow and balance sheet strength.
What Is Sanwa Holdings' Investment Narrative?
To own Sanwa Holdings, you need to be comfortable with a fairly steady, capital intensive construction hardware business that leans on installed base, maintenance work, and replacement demand across Japan, North America, Europe, and Asia. The fresh DCF work that flags a gap between intrinsic value and the current share price really just sharpens the existing thesis around cash generation, rather than changing the operational story. Recent share price performance has been mixed, with long term gains but a weaker 1 year return, which keeps the focus on execution rather than momentum.
In the short term, the key levers are straightforward. You are watching Sanwa Holdings’ ability to convert its ¥660,337 revenue and ¥57,400 net income into ongoing free cash flow while funding growth and paying a 3.63% dividend. Forecast earnings and revenue growth around 3% a year are modest compared with the wider JP market, so catalysts are more likely to come from consistent delivery, pricing discipline, and efficient use of external borrowing. The new DCF signal reinforces that cash flow matters most right now rather than introducing a new risk by itself.
Even so, there is a specific pressure point in this story that only becomes clear once you look at ...
There's only one way to know the right time to buy, sell or hold Sanwa Holdings. Head to Simply Wall St's company report for the latest analysis of Sanwa Holdings's Fair Value.
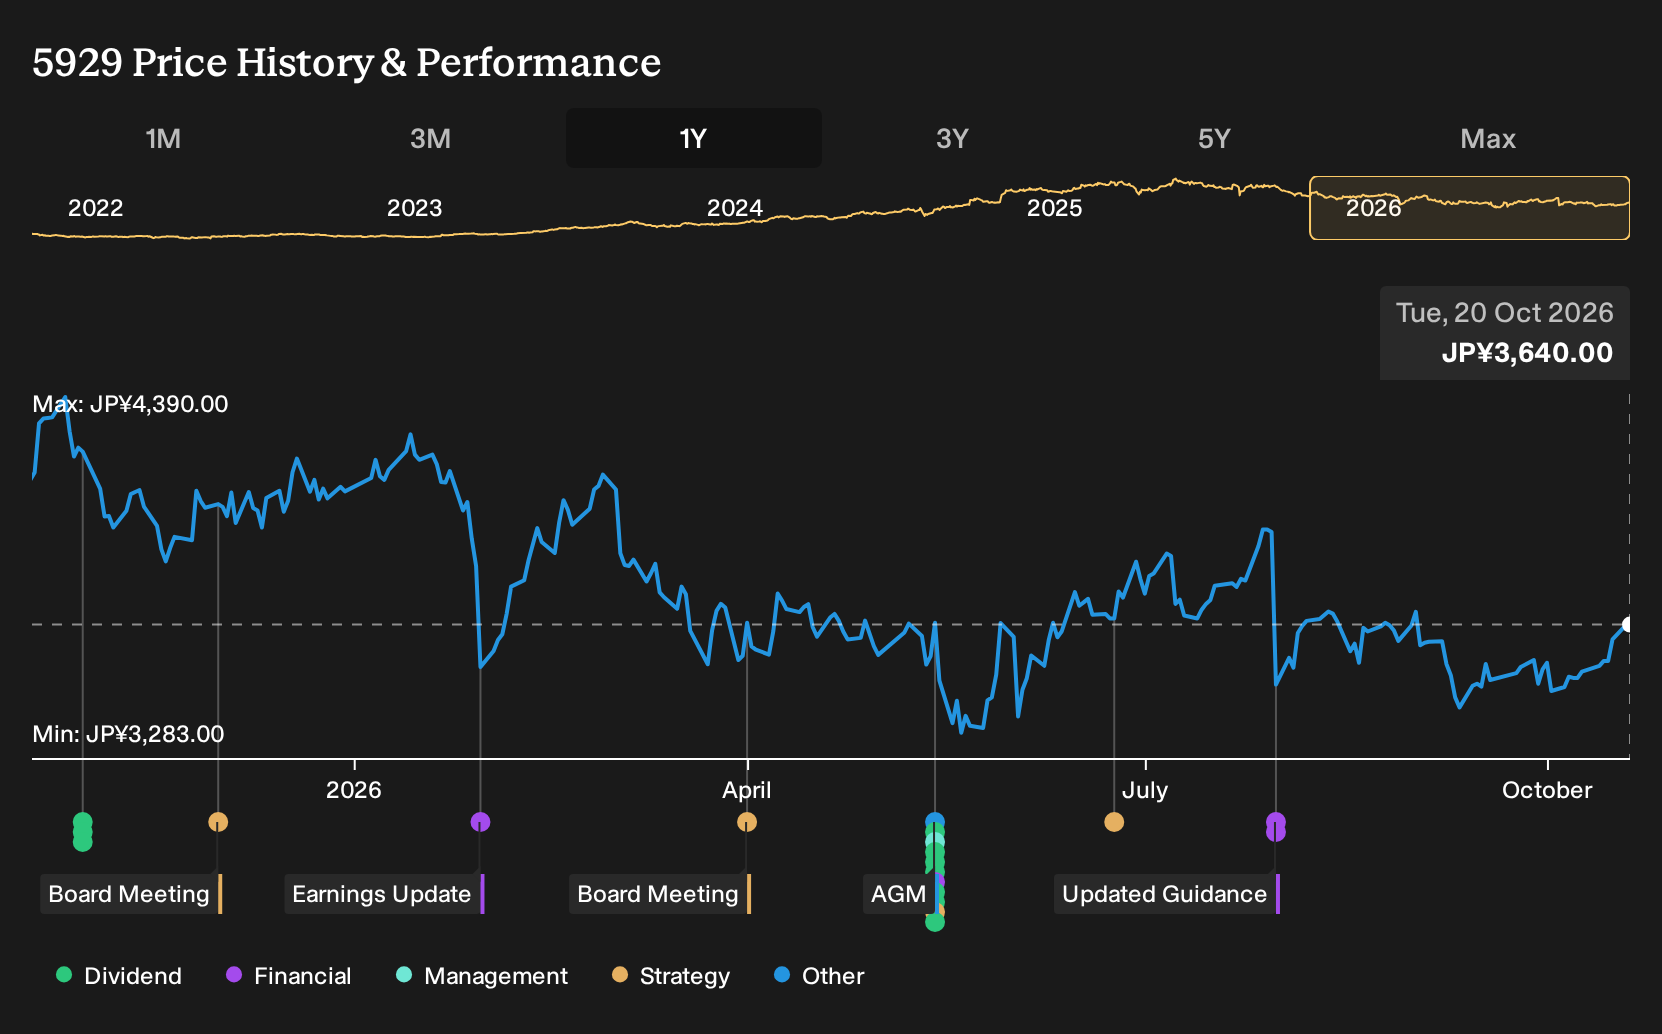
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between ¥4,271 and ¥8,821 per share, so you are seeing a wide span of opinion on Sanwa Holdings. These figures predate the latest DCF work and give you a clear opportunity to compare fresh cash flow analysis with earlier community views.
Explore 2 other Sanwa Holdings fair value estimates, including one that suggests it could be worth just ¥4,271.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sanwa Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Sanwa Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sanwa Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Sanwa Holdings?
Once you have a view on Sanwa Holdings, it can help to cross check that thinking against other opportunities that share similar qualities around cash flow, balance sheets, or income potential. The Simply Wall St Screener lets you filter for those traits directly so you are not relying only on headlines or broad market moves.
Here are a few focused ways to widen your watchlist using different screener angles:
- If capital preservation sits high on your priority list, start with sturdier balance sheets by scanning a list of solid balance sheet and fundamentals (22 results) that may better match a more cautious risk profile.
- For investors trying to pair quality with a margin between price and estimated worth, look across a 13 high quality undervalued stocks that combine solid fundamentals with attractive valuation signals.
- If income is your main filter, anchor your search around yield and payout strength by reviewing a 30 dividend fortresses that focus on stronger dividend profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com