
Man Group And 2 Other Top British Dividend Stocks
Energy prices across Europe are under fresh pressure, with Brent crude parked above $110 a barrel and the International Energy Agency warning that markets may not return to normal next year. That kind of squeeze keeps inflation concerns alive for British households. Reliable dividend payers on the UK market can offer investors a steadier stream of cash. This article highlights three higher yielding dividend stocks from our filter.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding dividend payers with coverage, growth and stability in focus. However, if you want the standouts, these 4 dividend aristocrats stocks are the most outstanding.
Man Group (LSE:EMG)
Man Group brings the Dividend Powerhouses theme into the asset management world, using fee income from its funds to underpin regular cash payouts in a way that can feel very different from the usual banks and utilities in many income portfolios.
"Robust global institutional demand for alternative and customized investment solutions continues to drive strong net inflows (e.g., record $17.6bn in H1 2025, well ahead of industry). This is positioning Man Group for sustained AUM and recurring fee income growth as institutions seek diversification in a low-yield and volatile market environment, positively impacting long-term revenue and earnings."
What ultimately matters for dividend investors is how one quiet shift in this fee mix affects the cash available for those future payouts.
Man Group is a global investment manager that runs long only and alternative funds across equities, credit, real estate, currencies and commodities, paying dividends from the management fees those products earn. All of its reported revenue, about $1.7b from the Investment Management Business, comes from this activity, and the group is valued at roughly £3.7b in the market.
That shift in fee mix is the real hinge for income investors, and the full narrative for Man Group shows how that engine could accelerate or stall future payouts.

Grafton Group (LSE:GFTU)
Grafton Group leans on its merchanting networks like Selco and Woodie’s to turn steady trade and DIY demand into recurring cash flows that can underpin a 3%+ yield. A broader mix of operations adds extra layers of resilience around that income story.
Grafton Group runs builders merchants, DIY retail and some manufacturing across Ireland, the UK and mainland Europe, with around £1.13b of revenue from the Island of Ireland, £746 million from Great Britain, £478 million from Northern Europe and £254 million from Iberia, and carries a market value near £1.85b.
"The strategic geographic diversification, including the new Spanish market and ongoing expansion in existing operations, positions Grafton Group to capitalize on housing shortages and structural demand in Europe, contributing to medium and long-term revenue growth."
What investors really need to watch is how one quiet shift in profitability shapes the cash left over to keep that dividend rhythm intact.
That profitability shift is exactly what the full narrative for Grafton Group unpacks. It reveals how Grafton Group’s expanding footprint could accelerate cash generation while also flagging where that rhythm might briefly stall.

Big Yellow Group (LSE:BYG)
Big Yellow Group runs 115 UK self storage sites, renting out flexible space that generates about £209 million from storage and related services, all in the UK. This rental income underpins its covered, growing 3%+ yield theme, with the stock valued near £1.8 billion.
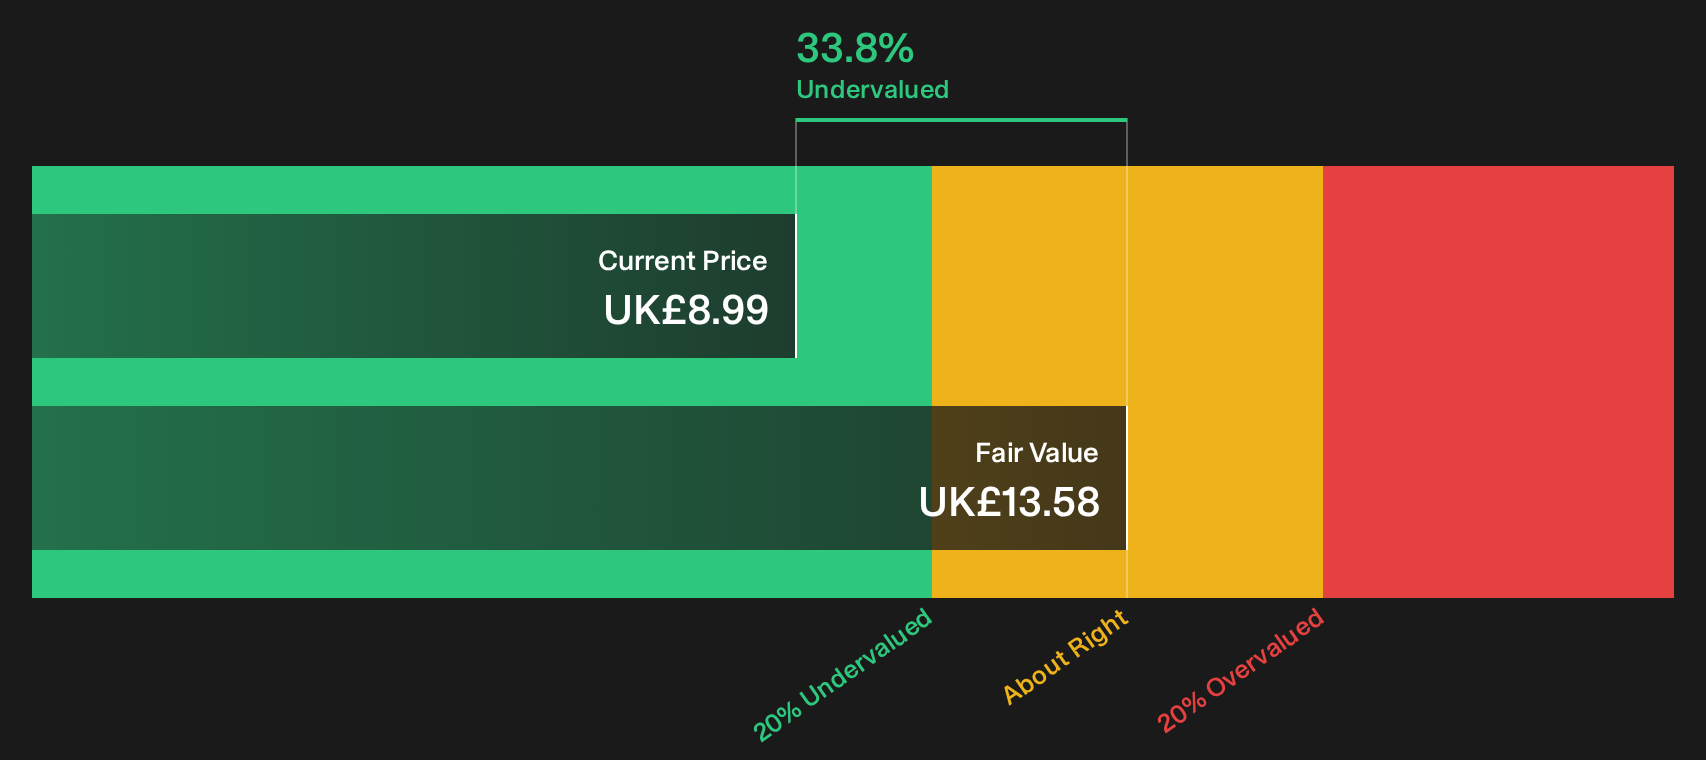
Big Yellow Group offers a self storage portfolio backed by mostly freehold London sites, a 5.25% dividend yield and a valuation that screens as cheap against estimated future cash flows. Income investors get a real estate backed payout stream that still depends on how one unseen pressure on funding costs and cash coverage evolves.
That funding pressure is exactly what the Big Yellow Group financial health report could be masking, especially if Big Yellow Group’s cash coverage starts to decouple from its headline yield.
Seeking Fresh Alternatives Beyond Dividends?
New ideas move first. Fresh themes gain momentum while screens stay quiet, then break out as the crowd catches up. Check these curated lists while it still matters and get in early.
- Spot stronger balance sheets before they fly by reviewing the carefully filtered list of solid balance sheet and fundamentals (9 results) that are built to handle tougher conditions without wobbling.
- Ride structural demand in power and electrification by scanning the hand picked 43 power grid technology and infrastructure stocks supporting grid upgrades, smarter networks and long term infrastructure renewal.
- Lean into automation trends early by tracking curated 92 robotics and automation stocks focused on real world adoption in factories, logistics and everyday services, not just blue sky stories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com