
Enova International (ENVA) Could Be 26% Undervalued Following A 23% Pullback
Enova International (ENVA) has drawn fresh attention after a recent share price move, with the stock retreating about 23% over the past 3 months despite a strong 1 year total return.
Recent trading has cooled, with the 90 day share price return down about 23% and the latest close at US$176.20, even though the 1 year total shareholder return is about 61%. This suggests that momentum has faded after a strong longer term run.
Scan how Enova International compares to other financial stocks that have pulled back after strong multi year runs by reviewing the hand picked 35 high quality undervalued stocks.
After a 23% pullback following a 61% 1 year total return, Enova International now presents a sharper question for investors. Does that reset tip the risk reward balance toward fresh buyers or caution?
Most Popular Narrative: 26% Undervalued
On the most followed view, Enova International screens as undervalued, with a narrative fair value of $238.50 against the latest close at $176.20. This puts recent share price weakness against a much higher long term earnings path.
The scaling efficiencies of Enova International's digital customer base, together with disciplined cost controls and a falling cost of funds from 8.8% to 8.1% over the last year, leave room for further operating leverage that can support adjusted EPS growth if originations and net revenue margins remain within management’s targeted range.
See why 11 investors see Enova International as 26% undervalued.
Result: Fair Value of $238.50 (UNDERVALUED)
Still, the Enova International narrative relies heavily on stable regulation and steady funding access. Setbacks on either front could quickly weaken that undervaluation case.
Find out about the key risks to this Enova International narrative.
Another View: Enova International Through A Cash Flow Lens
The analyst narrative tags Enova International as undervalued at a fair value of $238.50, yet the Simply Wall St DCF model paints a different picture. On that framework, ENVA at $176.20 trades well above an estimated future cash flow value of $94.29, which suggests the cash flows would need to outperform to support today’s price. Which story do you think is closer to how the next few years actually play out?
To see how this cash flow view is built, and what would need to change for the DCF output to move closer to the narrative fair value, Look into how the SWS DCF model arrives at its fair value.
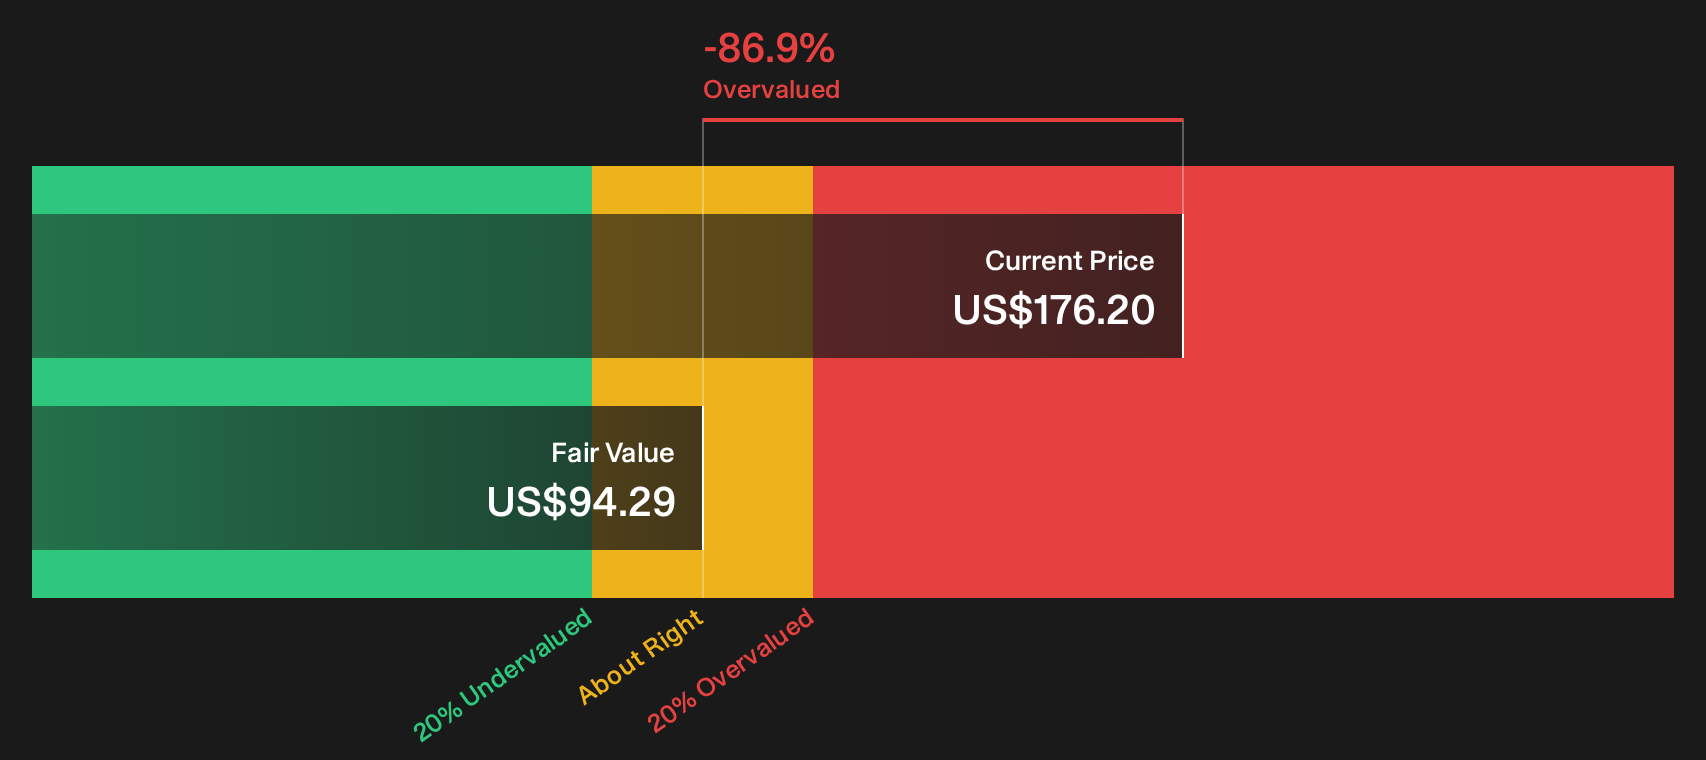
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Enova International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The split between an undervaluation story and a tougher cash flow read creates a real fork in the road for Enova International. Act while sentiment is mixed and pressure test the full picture for yourself with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Enova International?
If Enova International has sharpened your thinking on value and risk, do not stop there. Use the Simply Wall St screener to pressure test new opportunities before the crowd notices.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive valuations through the 35 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with strong financial footing using the list of solid balance sheet and fundamentals (25 results).
- Hunt for underfollowed opportunities by filtering for strong fundamentals in the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com