
Maximus (MMS) Stock May Look Reasonable Following Defense Deal News
Maximus shares have climbed in recent weeks even though the stock is still down sharply for the year. This puts a spotlight on whether the current price lines up with what the business is earning. With fresh headlines around an acquisition in defense and a recent earnings update, the question now is how much of that story is already embedded in the valuation.
- The share price is down 29.1% year to date, so any reassessment of Maximus now hinges on whether the recent rebound is supported by its earnings power.
- The planned purchase of Agile Defense points to a bigger push into defense and national security work, which can shift expectations for future profit streams and the timing of cash flows.
- Your read on Maximus is one view; the desks covering it have another. See what analysts think Maximus's shares could be worth.
The issue now is whether Maximus' current share price around US$61 reflects what its earnings justify today.
If you want to test the same earnings question that hangs over Maximus against a wider field, scan through the 35 high quality undervalued stocks.
Is Maximus Still Cheap on Earnings?
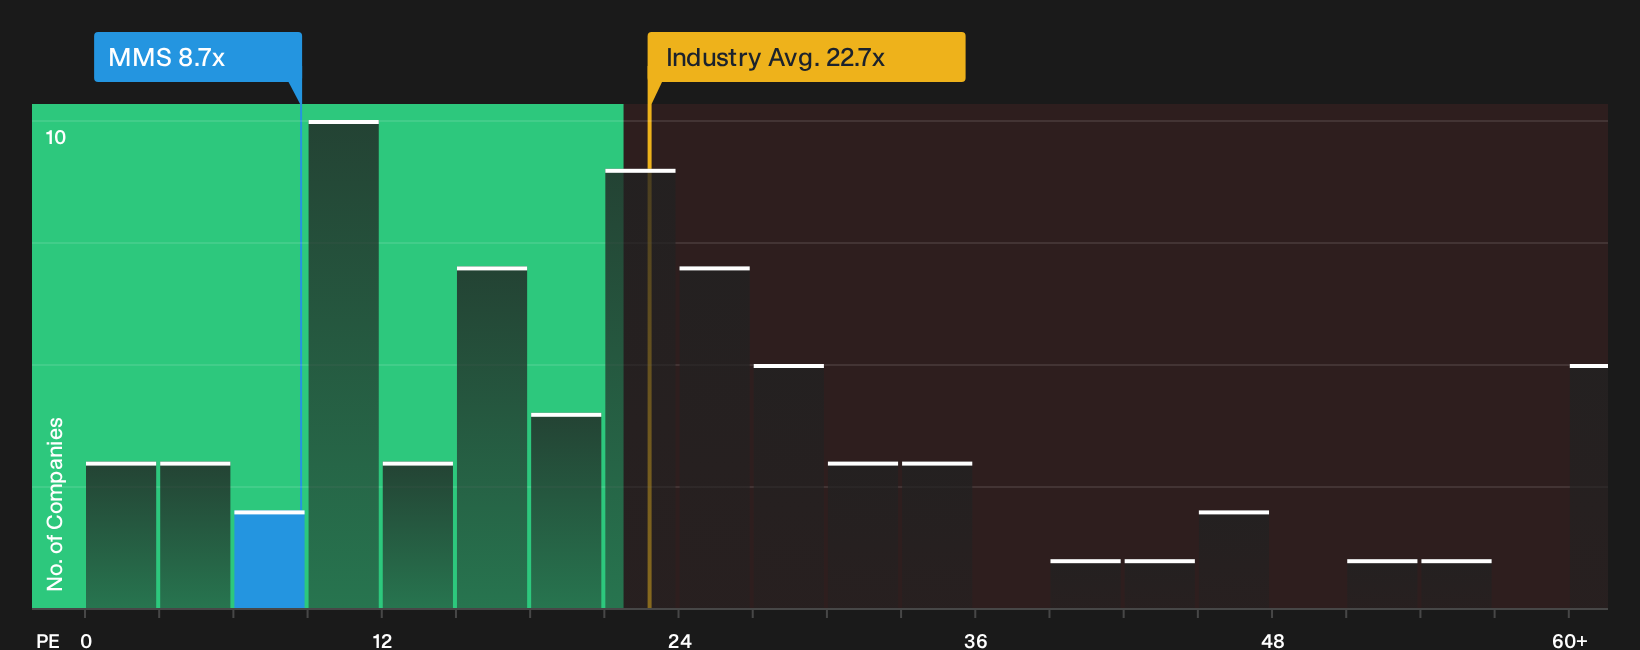
The P/E ratio fits Maximus because earnings are a central lens for contract driven government service providers. On that measure, Maximus trades on roughly 8.7x earnings, which is below both the Professional Services sector average of about 22.7x and the peer group near 13.8x. Because the price sits under the level suggested by a more tailored fair multiple that factors in margins, growth profile, size and risk, the current tag points to an undervalued earnings stream rather than a fully priced one.
Because the planned Agile Defense acquisition pushes Maximus further into defense and national security work, the gap between an 8.7x P/E and broader industry pricing indicates those expansion efforts are not fully reflected in the earnings multiple yet. For anyone weighing the stock, the key question is how durable the current profit base is and whether future contracts can support closing that discount over time. Explore the numbers behind Maximus's P/E valuation.
The Maximus Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Maximus valuation puzzle leaves you by explaining which paths for growth, margins and earnings would need to occur for the stock to appear materially higher or lower than today’s price. Each view links its figures to a clear stance on how Maximus' future profitability and risks might change, giving you something concrete to compare against the next contract win, earnings release or acquisition update.
One of the top community narratives on Maximus: 34% undervalued
"AI enabled automation is now embedded in the majority of Maximus bidding activity, with around 75% to 80% of new bids and rebids containing explicit AI requirements..."
Discover why this Narrative puts Maximus at 34% undervalued.
Maximus valuation is only half the story
Before leaning too hard on the earnings multiple or recent contract news, it helps to know our checks have also surfaced specific areas of concern that could matter just as much for Maximus. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com