
Credicorp (BAP), What Is Drawing Fresh Attention Now?
Credicorp (NYSE:BAP) has entered a quiet period ahead of its third quarter 2026 results, running from October 26 until the scheduled earnings release on November 9. This limits management commentary during that time.
Credicorp enters this quiet period with its shares at US$383.95, after a modest 34.06% year to date share price return and a much stronger 58.76% total shareholder return over the past year, which indicates that recent momentum has been building rather than fading.
Compare Credicorp’s momentum with a curated group of resilient financial stocks that have been screened for balance sheet strength and fundamentals through our list of solid balance sheet and fundamentals (25 results).
After a near 59% total return over twelve months and a share price near US$384, Credicorp still trades below both intrinsic estimates and analyst targets. Is that a margin of safety, or a warning signal?
Most Popular Narrative: 10.2% Undervalued
Credicorp’s most followed thesis points to a fair value of $427.48, above the last close of $383.95. The narrative therefore leans toward a discount that hinges on how well digital growth converts into earnings.
Expansion of Credicorp’s digital financial services like Yape is now tied to a much larger base of more than 16 million monthly active users who transact frequently and already contribute close to 10% of risk adjusted revenues. Further product roll out and higher revenue per user could continue to lift fee income and earnings.
See why 14 investors see Credicorp as 10% undervalued.
Result: Fair Value of $427.48 (UNDERVALUED)
Still, Credicorp’s heavy exposure to Peru and the flagged El Niño risk, which affects around 9% of its loan book, could quickly challenge that undervaluation story.
Find out about the key risks to this Credicorp narrative.
Another View: What Credicorp’s P/E Is Telling You
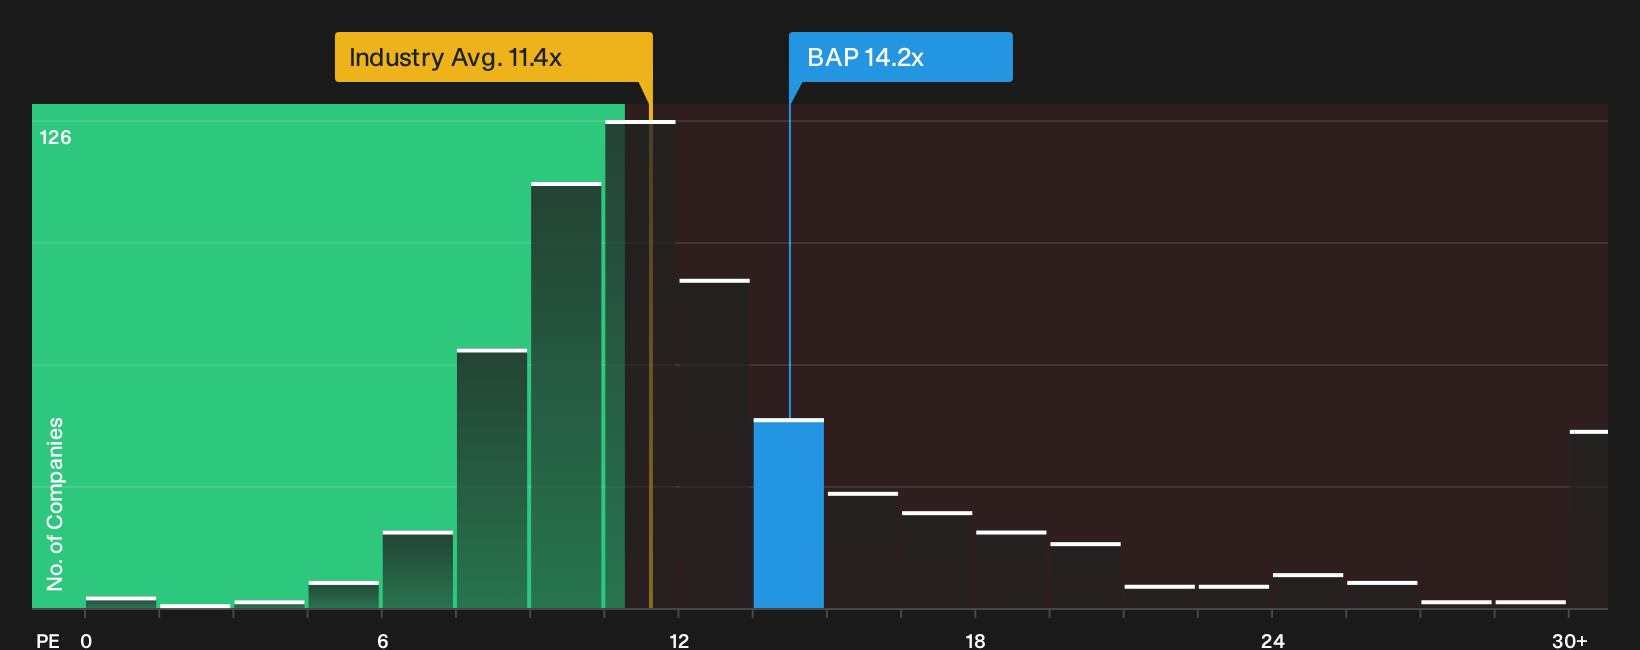
The first narrative leans on fair value and intrinsic estimates. A simple P/E check paints a different picture. Credicorp trades on 14.2x earnings, above both peers at 13.5x and the US Banks industry at 11.5x, and only slightly below a fair ratio of 14.9x. That points to less obvious upside and more room for sentiment to swing the multiple either way. Is that a comfortable entry point when the story already reflects a premium?
For a closer look at how this pricing gap could cut both ways, including where the ratio might drift over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Credicorp can pull you in either direction, so consider stress testing the potential upside and downside using 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Credicorp?
If Credicorp has your attention, use that momentum. Line up a few fresh watchlist candidates and test whether they offer a mix of quality, resilience, and income that suits what you hold today.
- Target potential mispricing by looking for quality at a discount through our 35 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by scanning for resilient businesses in the 32 resilient stocks with low risk scores.
- Track lesser known opportunities with solid fundamentals using the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com