
Roche Holding (SWX:ROP) Could Be 56% Below Fair Value After Fresh Cancer Data
Roche Holding (SWX:ROP) is back in focus after fresh Phase III oncology data at the 2026 ESMO meeting in Madrid, where the group highlighted next generation lung and breast cancer candidates.
That steady run of drug approvals and late stage readouts has coincided with a sharp swing in sentiment, with Roche Holding’s 30 day share price return of 9.28% and year to date gain of 19.78% contributing to a 1 year total shareholder return of 43.10%.
Scan Roche Holding’s oncology momentum against a curated group of peers by checking which companies on our 122 healthcare AI stocks are pairing advanced cancer pipelines with data driven diagnostics.
After a 43.10% one-year total shareholder return and with Roche Holding trading slightly above the average analyst target yet showing a 55.9966% intrinsic discount, where does a reasonable view of fair value land now?
Most Popular Narrative: 10.3% Overvalued
The current Roche Holding share price of CHF389.90 sits above the most followed fair value estimate of CHF353.34. This estimate is built off a detailed cash flow narrative using a 3.944% discount rate and a 20% profit margin assumption.
Roche is a cash-generating, defensive large-cap pharma, with upside driven by pipeline execution.
Roche represents a high-quality, lower-risk pharma investment relative to biotech, supported by strong cash flows, market leadership in oncology, and a deep pipeline, but with upside constrained by loss of exclusivity in key drugs and pipeline uncertainty, particularly in neuroscience.
See why 7 investors see Roche Holding as 10% overvalued.
Result: Fair Value of CHF353.34 (OVERVALUED)
Still, Roche Holding’s story can shift quickly if late stage trial setbacks build up or biosimilar pressure hits key oncology and immunology cash engines harder than expected.
Find out about the key risks to this Roche Holding narrative.
Another View on Roche Holding’s Valuation
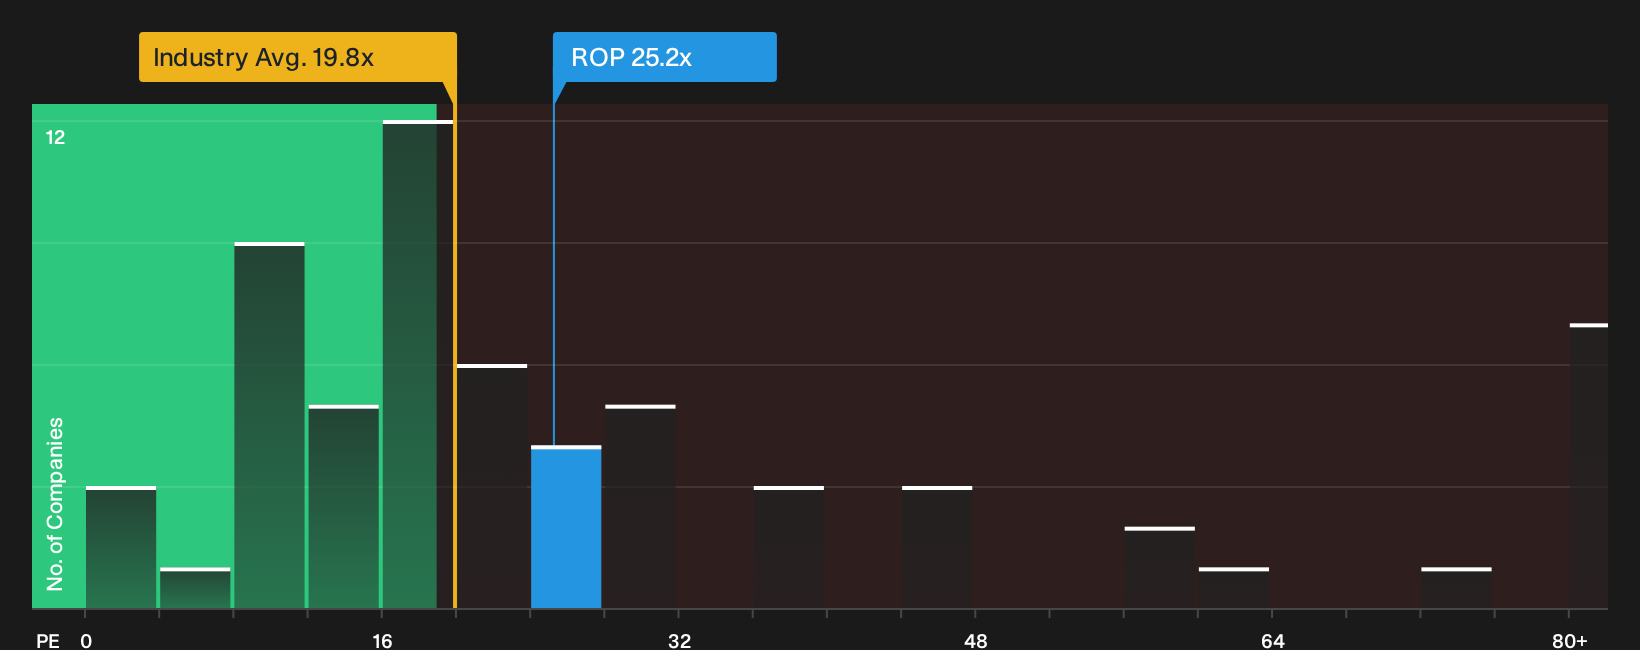
The 10.3% “overvalued” verdict from the cash flow narrative contrasts with a very different signal when Roche Holding is viewed through earnings multiples. The shares trade on a 25.2x P/E, while peers average 44.9x and the fair ratio is 46.7x. This points to a sizeable valuation gap that may represent both risk and potential opportunity for investors to consider. Which signal should carry more weight in your framework?
To see how this earnings-based view compares with other checks on the stock, including how the fair ratio might change if sentiment shifts, have a look at See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Roche Holding’s valuation and outlook call for quick, independent scrutiny. Put the numbers in context for yourself by weighing the 3 key rewards and 1 important warning sign.
Looking for more Roche Holding sized ideas?
If Roche Holding has sharpened your appetite for quality, do not stop here. Fresh opportunities move quickly, and the best setups rarely wait around.
- Target mispriced quality by scanning companies that combine strong balance sheets with attractive valuations using the list of solid balance sheet and fundamentals (202 results).
- Hunt for future compounders by reviewing a curated 614 high quality undiscovered gems before they draw broader market attention.
- Prioritise resilience and sleep-at-night positions through a focused 230 resilient stocks with low risk scores that filters for sturdier business profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com