
AXT (AXTI) Stock Looks Pricey As Its 3 Year Run Continues
AXT has turned into one of the market’s more extreme recent movers, and the pace of that run now raises a simple question for you as a shareholder or potential buyer. Is the current price tag on AXT stock still grounded in what the business actually generates in sales, or has the share chart moved ahead of the revenue story?
- AXT’s share price has delivered an extremely large gain over the past 3 years, which puts a lot of weight on whether today’s valuation can be supported by its underlying sales base.
- The long term indium phosphide supply deal with Lumentum, which runs through 2031 and is linked to a backlog of roughly US$100 million of delayed orders, can shape how firmly investors treat AXT’s future revenue visibility and capacity needs when they look at the stock’s current sales multiple.
- Your read on AXT is one view; the desks covering it have another. See what analysts think AXT's shares could be worth.
The issue now is whether the current AXT share price is adequately supported by its sales when you weigh that rapid share move against the company’s revenue backdrop.
If you want more context on what a move like AXT’s could look like in other parts of the chip space, compare it to 55 AI infrastructure stocks for reference.
Does AXT Look Pricey on Sales?
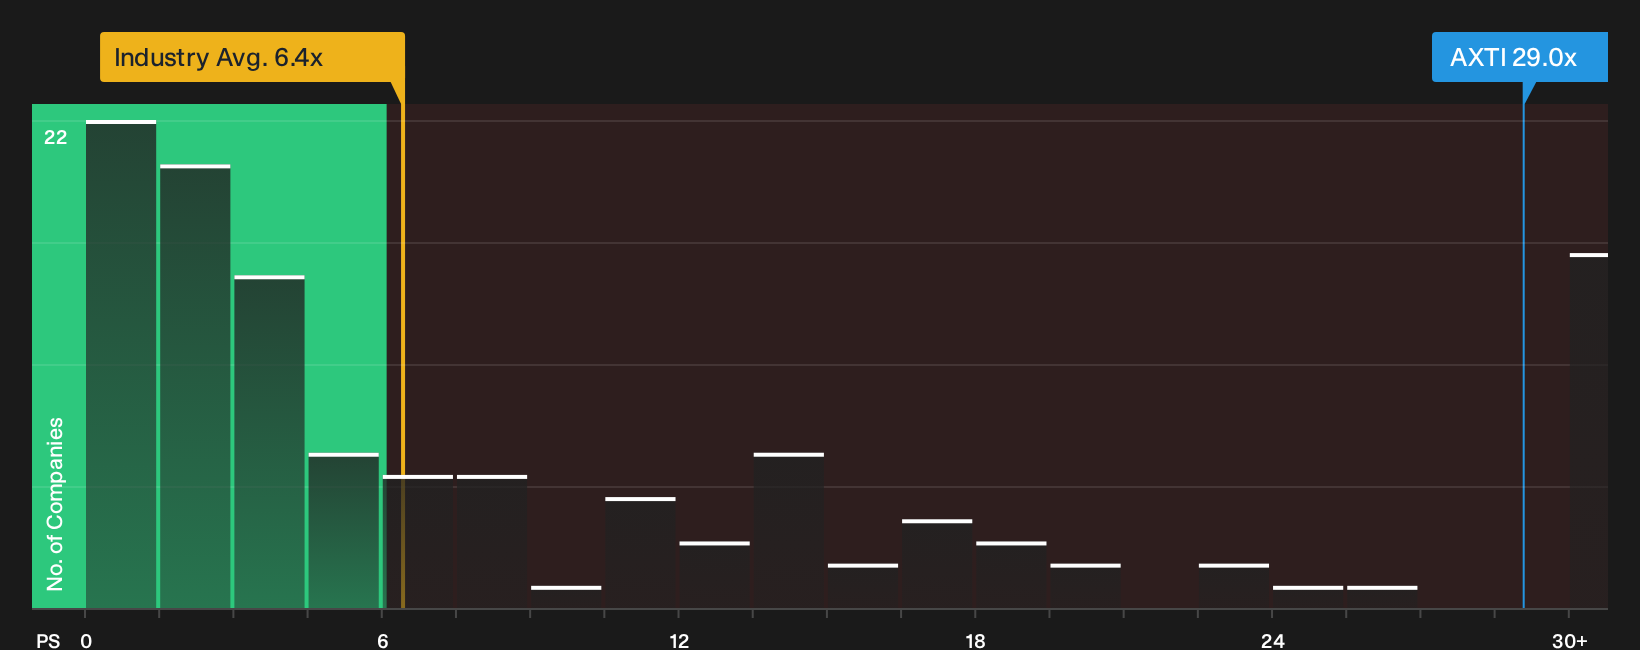
P/S is useful for AXT because sales data is available even while free cash flow and earnings are still uneven. On this metric, the stock trades on a P/S of 29.0x, compared with a Semiconductor industry average of 6.4x and a peer group around 3.4x, so the valuation sits at a steep premium to both broader sector and closer comparables.
Despite the recent jump on the long term Lumentum supply deal, that gap means the current price already assigns a heavy value to AXT’s existing revenue base and future demand for its materials. The fair multiple implied by a more tailored model that weighs the company’s own growth profile, margins, size and risk sits below today’s P/S, so the shares screen as overvalued on this measure. That leaves you needing strong conviction about how durable and scalable AXT’s sales will be from here to feel comfortable with this kind of revenue multiple. Explore the numbers behind AXT's P/S valuation.
The AXT Narrative: What Would Justify Today's Price?
Narratives on AXT pick up where the valuation question leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the share price to look meaningfully higher or lower than today. Each one links its number to a clear view on how AXT's revenue mix, profitability and risk profile might evolve. This gives you a reference point you can revisit as fresh information arrives on Simply Wall St's Community page.
Community views on AXT split between those who see extra upside in the AI materials story and those who think expectations already look full.
Bull case: 38% undervalued
"Accelerating global demand for high-speed data center connectivity and AI infrastructure is driving increased adoption of indium phosphide substrates, where AXT is a top supplier with 40% share..."
Discover why this Narrative puts AXT at 38% undervalued.
Bear case: roughly fairly valued
"Persistent and unpredictable export permit delays and government-imposed trade restrictions in China are likely to restrict AXT's access to key international markets for both gallium arsenide and indium phosphide substrates..."
Explore why this Narrative puts AXT at roughly fairly valued.
Before acting on AXT’s valuation, there is one more angle to check
Price tags get most of the attention, yet the people steering AXT and how they are rewarded can heavily influence what happens next for the business. See who runs AXT and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com