
Whirlpool (WHR) Stock Dropped, So What Is Driving Attention Now?
Whirlpool (WHR) has an upcoming third quarter earnings release on October 26, 2026, followed by a conference call on October 27. This is putting fresh attention on a stock that recently declined 5.13%.
That single session drop sits on top of a longer slide, with Whirlpool’s share price down 17.23% over the past 30 days and 27.39% over 90 days, while the 1 year total shareholder return has declined 62.62% and the 5 year total shareholder return has fallen 83.80%. This points to fading momentum as investors reassess both earnings risk and valuation ahead of results.
Scan beyond Whirlpool and pressure-tested appliance makers to a hand-picked shortlist of beaten-down value ideas in our 35 high quality undervalued stocks while this kind of reset is still playing out across the market.
Whirlpool still sells essential appliances into millions of homes, yet the share price slide and earnings pressure now raise a sharper question: Is this a solid franchise temporarily marked down, or a business correctly cheap for a reason?
Most Popular Narrative: 44% Undervalued
Whirlpool closed at $26.46, while the widely followed fair value narrative points to $47.17. This creates a wide gap that puts execution on cost cuts and pricing in the spotlight ahead of earnings.
Ongoing factory consolidation, automation investments and logistics footprint changes in North and Latin America, including site modernizations and distribution center reductions, are expected to deliver at least $150 million of 2026 cost savings and roughly $180 million of annualized EBIT benefits from 2027 onward. These factors could support higher Whirlpool net margins and earnings as these programs ramp.
See why 30 investors see Whirlpool as 44% undervalued.
Result: Fair Value of $47.17 (UNDERVALUED)
Still, the Whirlpool narrative can break if appliance demand in core markets stays weak and EBIT margins remain stuck well below the 4% guidance line.
Find out about the key risks to this Whirlpool narrative.
Another View: Whirlpool Through The P/E Lens
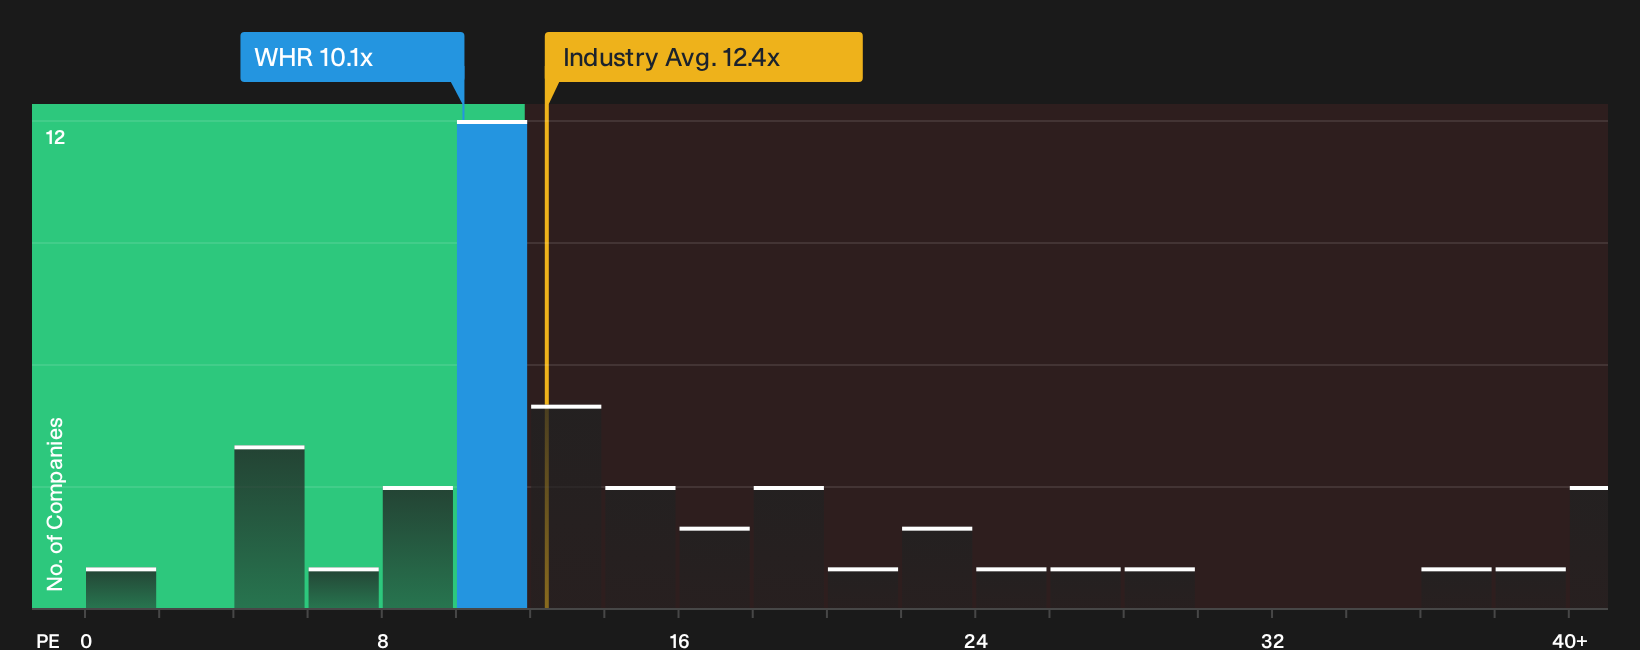
The first fair value story for Whirlpool leans heavily on analyst earnings forecasts and discounted cash flows. A simple P/E check tells a different story. WHR trades on about 10.1x earnings, slightly above close peers at 9.8x, yet below the wider US Consumer Durables group at 12.4x and well under a fair ratio of 20.4x. That mix of a modest premium to direct competitors but a big gap to the fair ratio raises a blunt question for you as an investor: Is the market sensibly cautious, or leaving too much on the table?
To pressure test that P/E gap against underlying earnings power, it helps to move from headline multiples to the nuts and bolts in our valuation breakdown, where you can see what the numbers say about this price in detail, See what the numbers say about this price — find out in our valuation breakdown.
Side by side charts comparing Whirlpool's current P/E with peers, the Consumer Durables average and the fair ratio can make that trade off easier to judge at a glance,
Next Steps
Whirlpool’s recent slide and mixed signals on value create a complex picture. Move quickly, review the data independently and then decide where you stand using the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Whirlpool?
Do not stop your research with Whirlpool. Broaden your watchlist with fresh ideas that match your risk profile and income goals while this reset phase is still unfolding.
- Target potential mispricings by scanning a curated pool of beaten-down quality opportunities through the 35 high quality undervalued stocks.
- Build steadier income by focusing on companies with meaningful yields and resilient payouts using the 8 dividend fortresses.
- Prioritise resilience by filtering for businesses with stronger finances and healthier fundamentals in the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com