
Is Ocado Group (LSE:OCDO) Fully Valued After Analyst Upgrades Turned Sentiment Around?
Ocado Group (LSE:OCDO) has just attracted fresh attention after a cluster of analyst upgrades, including moves to more positive ratings that highlight improving earnings estimates and a fading stream of earlier negative headlines.
Ocado Group’s recent surge has been sharp, with a 30-day share price return of 53.25% and a 90-day gain of 78.41% around the analyst upgrades. However, the 5-year total shareholder return is still down 80.60%, so current momentum contrasts with a weak longer-term record and signals a shift in how investors are pricing its risks and potential cash flow improvement.
Compare Ocado Group’s sharp rebound with other potential turnaround stories by scanning our hand-picked list of 5 high quality undiscovered gems that the market may not be pricing fully yet.
After a £2.6b valuation swinging sharply higher on upbeat analyst sentiment, the real tension now is simple: Does Ocado Group still offer enough potential reward to justify the risk from here, or has most of the opportunity already been pulled forward?
Most Popular Narrative: 50% Overvalued
Ocado Group last closed at £3.49, which sits well above the most followed fair value estimate of £2.33 that uses an 8.6% discount rate. That gap reflects a narrative where the share price leans heavily on future cash flow improvement and contract execution that are not yet visible in current earnings.
Despite operational efficiencies and cost savings, the belief that Ocado will rapidly achieve and maintain long-term profitability may overlook ongoing fixed R&D and technology spending requirements, especially as customization for new geographies and product variants increases, risking weaker net margins and lower earnings than modeled.
See why 31 investors see Ocado Group as 50% overvalued.
Result: Fair Value of £2.33 (OVERVALUED)
Still, Ocado Group’s narrative could be challenged if online grocery adoption slows, or if clients favour cheaper, hybrid fulfilment options over full automation.
Find out about the key risks to this Ocado Group narrative.
Another View: Ocado Group And The Cash Flow Lens
The analyst-led fair value of £2.33 paints Ocado Group as overvalued, yet the SWS DCF model points in the opposite direction and suggests the shares trade below an estimated future cash flow value of £4.76. That split frames a simple question for you: Which set of assumptions feels more realistic?
Look into how the SWS DCF model arrives at its fair value.
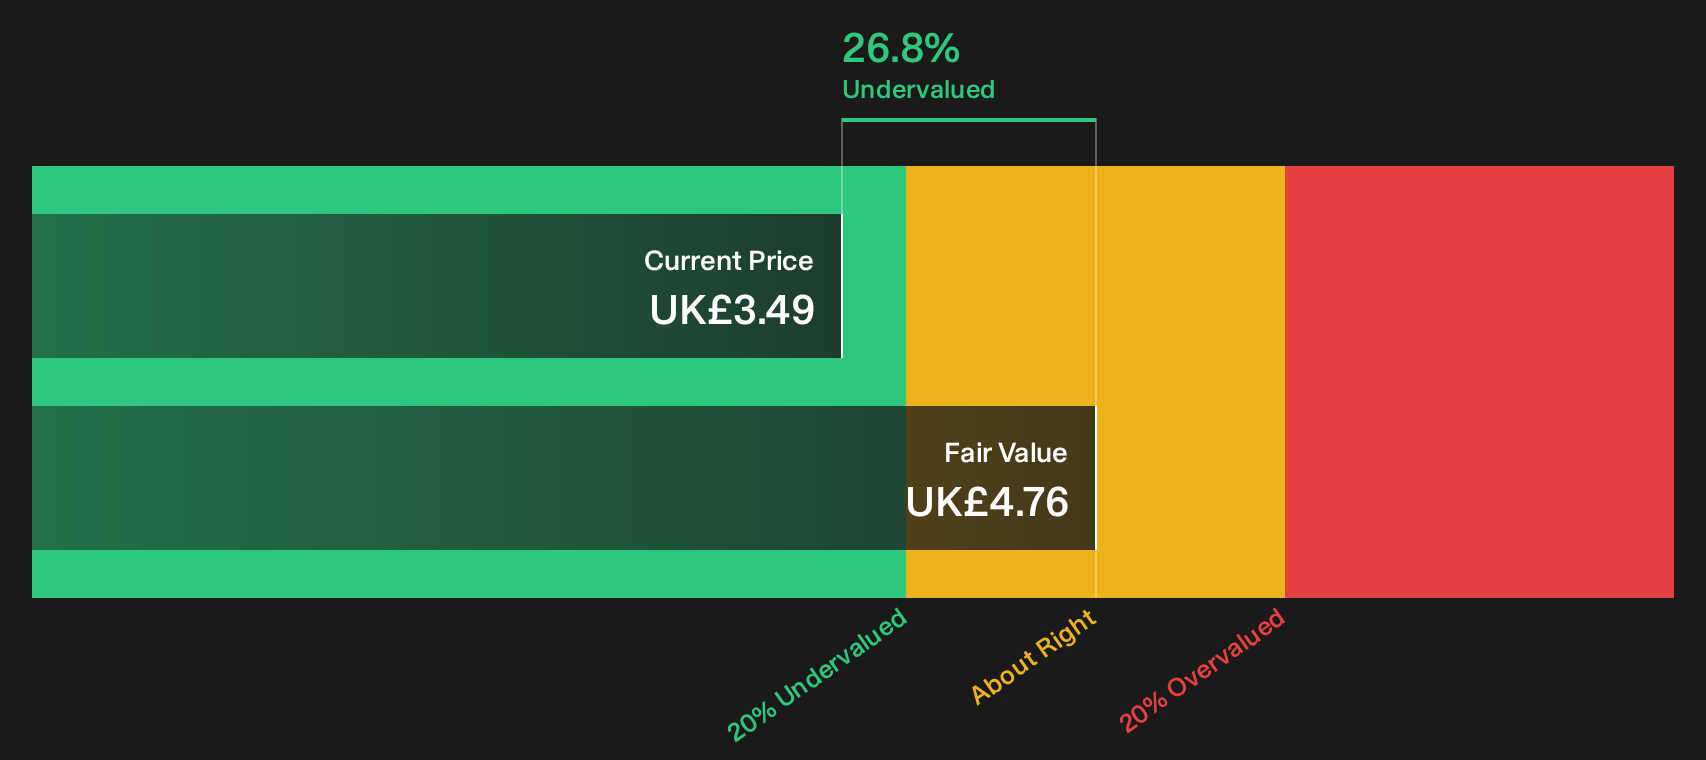
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ocado Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Ocado Group is clearly split. This is exactly why it pays to move quickly, test the numbers yourself and decide where you stand with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Ocado Group?
If Ocado Group has sharpened your focus on risk and reward, do not stop here. Broader opportunity often sits just outside the headlines.
Use the Simply Wall St Screener to pinpoint fresh ideas tailored to how you like to invest.
- Target potential mispricings by scanning a curated set of 7 high quality undervalued stocks that pair quality fundamentals with discounted market expectations.
- Protect your downside by reviewing a 4 resilient stocks with low risk scores that filters for resilient businesses with steadier risk profiles.
- Strengthen portfolio resilience by checking a list of solid balance sheet and fundamentals (9 results) that highlights companies with cleaner debt levels and stronger financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com