
Samsung (KOSE:A005930) Stock May Trade Below Fair Value On AI Spending Fears
Samsung Electronics has delivered a powerful multi year share price run, and the recent pullback now puts a sharper spotlight on whether that climb is still supported by its earnings. With the stock recently closing at ₩211,500, the question for anyone watching Samsung is how much of its future profit story is already embedded in that figure.
- Over the past 5 years the share price has gained 227.7%, which puts a lot of past optimism about Samsung’s profit potential on trial against what the business is actually earning today.
- Recent headlines around AI infrastructure spending, memory demand and geopolitical risk highlight how quickly expectations for Samsung’s earnings power can change, which feeds directly into what investors may be willing to pay for each won of profit.
- There is a second opinion on Samsung Electronics worth weighing. See what analysts think Samsung Electronics's shares could be worth.
The issue now is whether Samsung’s current share price is adequately supported by its earnings when set against a Fair Ratio benchmark.
If you want more context around AI related semiconductor swings like Samsung Electronics is experiencing, a focused starting point is a screen of 55 AI infrastructure stocks.
Does Samsung Electronics Look Undervalued on Earnings?
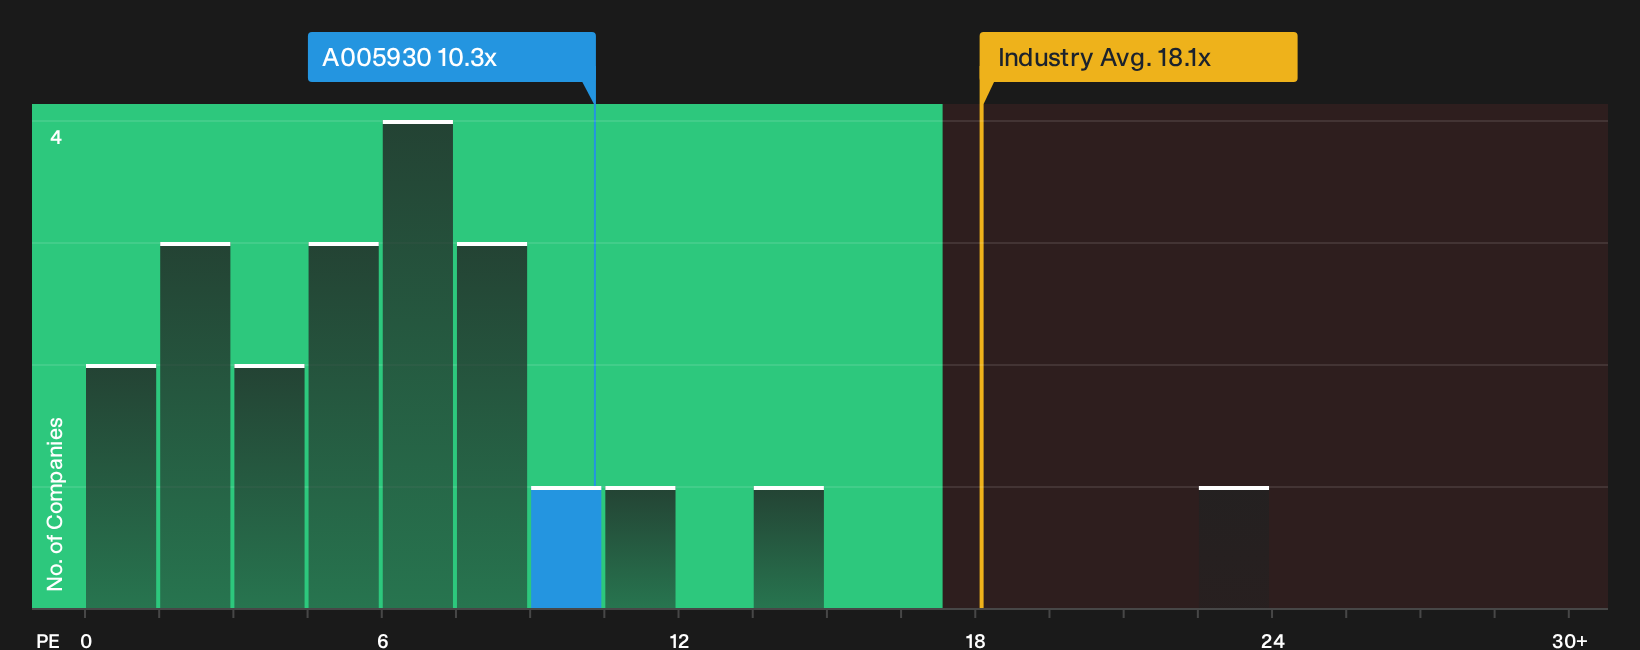
A P/E lens suits Samsung Electronics because profit-based ratios speak directly to what investors are paying for its current earning power. At a P/E of 10.3x, the stock trades far below the broader tech sector on 19.1x and even further below a peer group closer to 50.0x. The Fair Ratio model, which blends factors like growth expectations, margins, size and risk profile, points to a higher multiple than where the shares are today, so the current level screens as undervalued on this framework.
Recent selling pressure around AI spending worries and Chinese competition has pulled sentiment back, yet the 10.3x P/E still sits at a discount to both sector norms and that Fair Ratio yardstick. For anyone assessing Samsung Electronics, the key question is whether current earnings and the risks highlighted in recent news justify that gap or whether it reflects an opportunity that the market is reluctant to price in fully. Explore the numbers behind Samsung Electronics's P/E valuation.
The Samsung Electronics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Samsung Electronics pick up where the valuation puzzle leaves off and spell out the specific growth, margin and earnings paths that would need to play out for the shares to be worth materially more or less than today’s price. Instead of a single model output, they outline the future that number leans on, so you can watch how Samsung Electronics' actual progress lines up with those assumptions on the Community page over time.
Community views on Samsung Electronics are split between those who see extra upside left in the AI and memory story and those who think today’s price already reflects most of it.
Bull case: 58% undervalued
"Samsung's competitors like TSMC, SKHY, MU, and INTC are not capable of what Samsung can…"
Discover why this Narrative puts Samsung Electronics at 58% undervalued.
Bear case: roughly fairly valued
"The main risk is that memory is highly cyclical…"
Explore why this Narrative puts Samsung Electronics at roughly fairly valued.
Samsung Electronics’ valuation still hinges on one crucial unknown
Price tags and profit multiples only tell part of the story for Samsung Electronics, because the people steering the business and how their pay is structured can tilt outcomes in ways the numbers never show on their own. See who runs Samsung Electronics and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com